
What Essential Properties Realty Trust Shares Credit Facility Reset Means For Shareholders
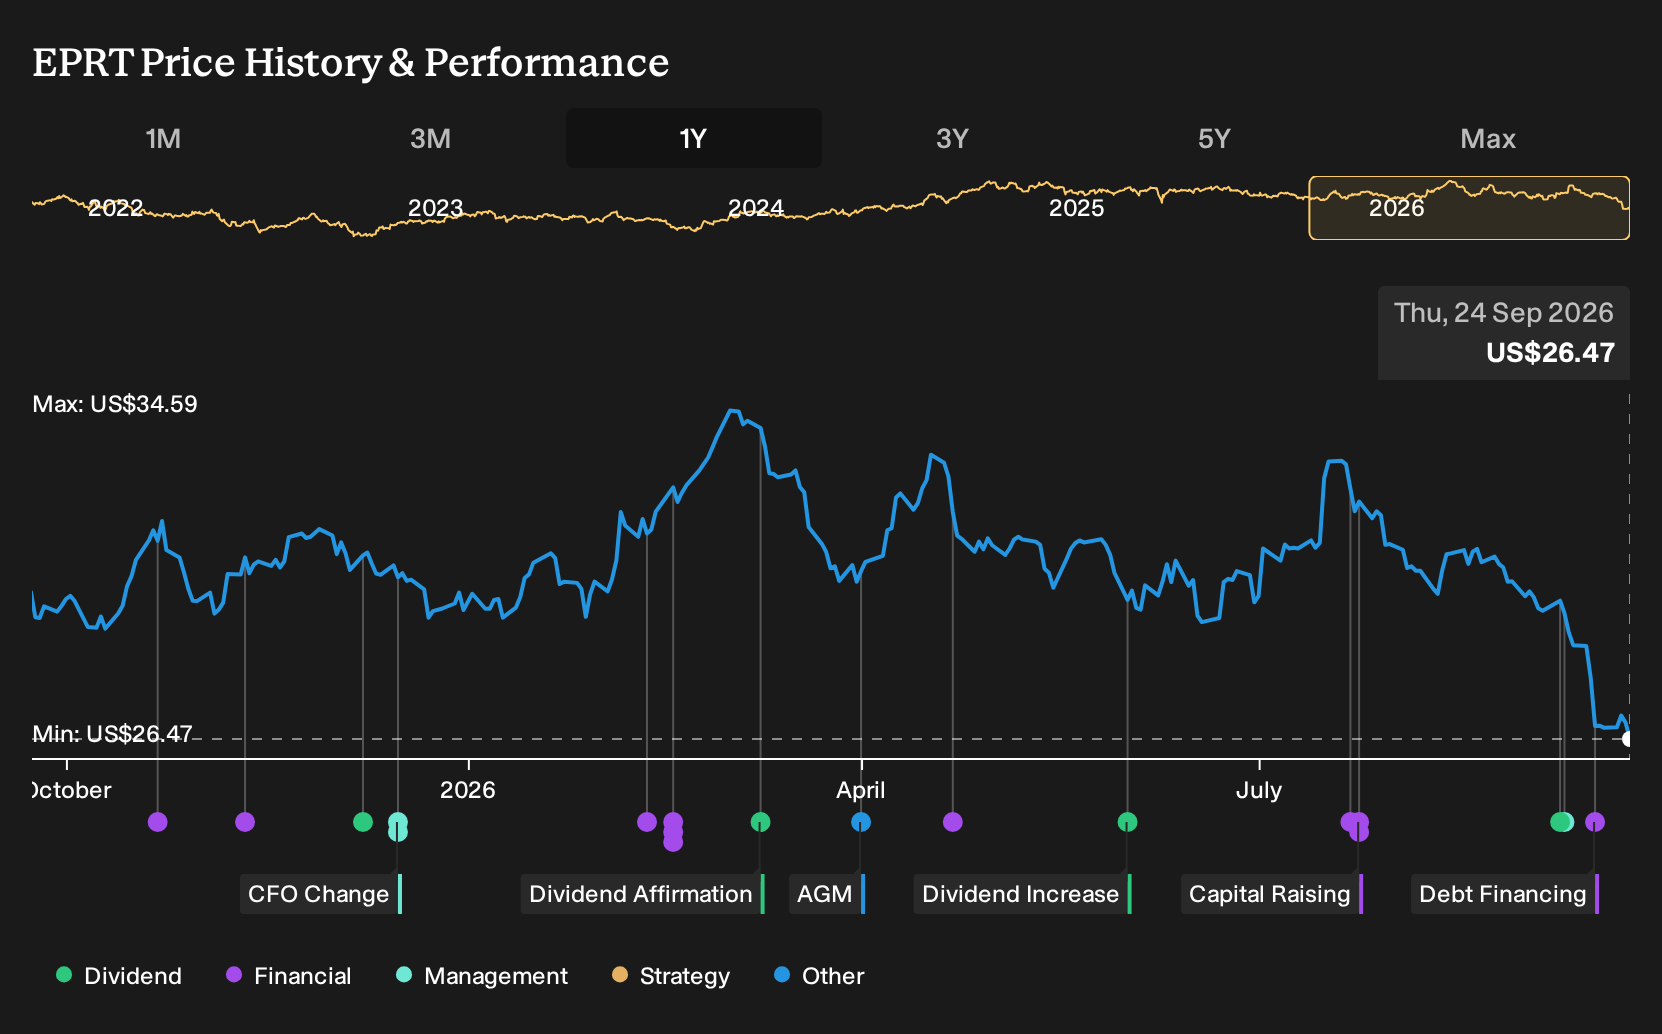
- Essential Properties Realty Trust amended its credit agreement in September 2026, lifting revolving credit commitments from $1.0b to $1.3b, resetting a $700.0m accordion feature, and cutting pricing on its revolving facility and term loans while also releasing subsidiary guarantors.
- The company used this expanded and cheaper revolving capacity to fully repay and terminate its Capital One Credit Agreement. This consolidated funding under a single larger facility that may simplify liquidity management and acquisition funding.
- We will now look at how Essential Properties Realty Trust's investment narrative interacts with this larger revolving credit facility capacity.
Essential Properties Realty Trust Investment Narrative Recap
To own Essential Properties Realty Trust, you need to be comfortable with a REIT built on long net leases to service focused tenants and a heavy use of external financing to grow. The key short term swing factor is how effectively management can convert its investment pipeline into accretive deals while keeping occupancy near current levels. The refreshed credit facility looks helpful but does not on its own change that operational equation.
The biggest near term risk still sits around tenant quality and sector concentration in areas like car washes and restaurants, particularly if middle market operators come under pressure. Higher G&A, sale leaseback exposure to non investment grade tenants, and debt that is not well covered by operating cash flow already pull investor attention toward execution discipline rather than balance sheet fireworks.
The September 2026 amendment to Essential Properties Realty Trust’s credit agreement is the announcement that ties closest to the current narrative. Larger revolving capacity at US$1.3b, a reset US$700m accordion and lower margins on the facility and term loans all point to cheaper and more flexible funding. The release of subsidiary guarantees also changes how lenders share risk.
For you as a shareholder, the practical question is whether that extra liquidity supports sensible, service based net lease acquisitions without stretching tenant risk or leverage. The company’s history of sale leaseback deals with middle market operators and its focus on long leases with rent escalators make access to low cost credit a clear operational catalyst. It also raises the bar on underwriting discipline if competition squeezes yields or sector specific issues hit portfolio cash flows.
Essential Properties Realty Trust's current narrative centers on analysts expecting revenues of US$891.9 million and earnings of US$369.4 million by 2029, which implies 14.7% yearly revenue growth and an earnings increase of about US$113.7 million from US$255.7 million today.
Discover how Essential Properties Realty Trust's fair value indicates a 40% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly US$29.5 to US$97.4 per share, so some retail investors see Essential Properties Realty Trust as deeply undervalued while others mark it far higher. Consider that wide range alongside the risks around tenant concentration and competition compressing cap rates, and explore several alternative viewpoints before forming your own stance.
Explore 3 other Essential Properties Realty Trust fair value estimates, including one that suggests it could be worth just $29.53.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Essential Properties Realty Trust research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Essential Properties Realty Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Essential Properties Realty Trust's overall financial health at a glance.
Looking For More Investment Ideas Beyond Essential Properties Realty Trust?
Once you understand how Essential Properties Realty Trust uses its balance sheet, it can help to compare that profile with other businesses that share some of the same traits. Use the Simply Wall St Screener to pressure test your thesis against a wider set of companies that might better fit your risk tolerance, income goals, or preference for financial strength.
- If capital preservation and steadier profiles matter most to you, scan through a 30 resilient stocks with low risk scores that may better align with a lower volatility approach.
- If value is your anchor, review our 30 high quality undervalued stocks that combine quality fundamentals with prices that some investors may see as appealing.
- If income is a priority, check out a 8 dividend fortresses that focus on higher yields for investors who want regular cash returns from their holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com