
Starwood Property Trust (STWD) Stock May Look Rich As Earnings Face Closer Scrutiny
Starwood Property Trust has seen its share price fall this year, which naturally puts the focus squarely on whether the current valuation still lines up with what its earnings can support. For a stock built around income from real estate credit and related investments, that is the question that matters most for long term holders.
- The share price is down 22.0% year to date, which puts extra weight on whether the market is now asking too much or too little of the earnings stream behind Starwood Property Trust.
- The business relies on earnings from loans and property related assets, so any shift in credit quality, funding costs or rent collection can reshape what investors are willing to pay for each dollar of profit.
- Your read on Starwood Property Trust is one view; the desks covering it have another. See what analysts think Starwood Property Trust's shares could be worth.
The issue now is whether Starwood Property Trust's current share price is justified by its earnings when set against the Fair Ratio benchmark.
If you want a broader yardstick alongside Starwood Property Trust while you assess earnings support and valuation, consider a focused stock screen built around 30 high quality undervalued stocks.
Does Starwood Property Trust Look Pricey on Earnings?
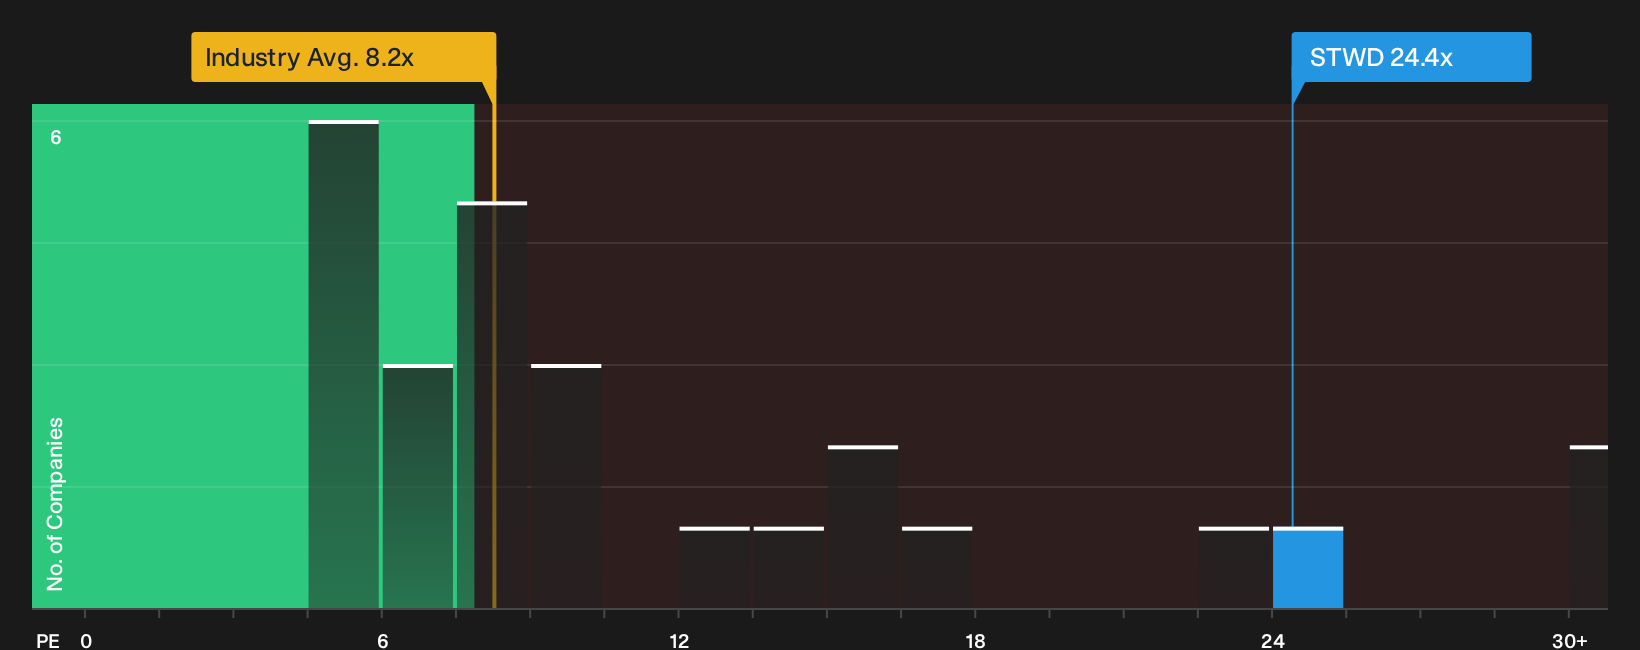
The P/E ratio tends to matter most for Starwood Property Trust because earnings power is what ultimately backs its real estate credit payouts. On this lens, the stock trades on roughly 24.4x earnings, which is well above the Mortgage REITs sector average of about 8.2x and also below the broader peer group on roughly 41.4x. That tells you the market is already paying a meaningful premium to the sector for each dollar of Starwood Property Trust earnings, while still valuing it at a discount to some alternative income focused lenders.
The Fair Ratio model, which blends the company’s own profitability, risk profile and scale rather than relying only on raw averages, points to a lower multiple than where the shares change hands today. That gap suggests the stock screens as overvalued on this earnings benchmark, so an investor would need to be comfortable that Starwood Property Trust can keep justifying a richer P/E than the sector in order to feel confident paying this kind of earnings price tag. Explore the numbers behind Starwood Property Trust's P/E valuation.
The Starwood Property Trust Narrative: What Would Justify Today's Price?
Starwood Property Trust's valuation puzzle sets the stage for Simply Wall St Narratives, which map out what would need to happen to future growth, margins and earnings for the stock to be worth materially more or less than today's price on the Community page.
Each scenario links its number to a clear view on how profitability, expansion prospects and risk might evolve, giving you a concrete set of expectations you can return to as new information comes through.
One of the top community narratives on Starwood Property Trust: 28% undervalued
"Systematic workout and recycling of roughly US$1.9b of nonaccrual and REO assets provides a pipeline of capital that can be redeployed..."
Discover why this Narrative puts Starwood Property Trust at 28% undervalued.
One more Starwood Property Trust check that belongs next to the valuation work
Price and earnings only tell part of the Starwood Property Trust story, because separate research checks have flagged specific risk signals that deserve your attention before you decide what comes next. Take a closer look at 4 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com