
Should Half Year Earnings Require Action From Peugeot Invest Société anonyme (ENXTPA:PEUG) Investors?
- Peugeot Invest Société anonyme reported half year 2026 results with revenue of €148.94 million, net income of €135.85 million and basic earnings per share of €5.47.
- The business generated higher earnings on a smaller revenue base, which points to shifts in Peugeot Invest Société anonyme’s cost discipline and portfolio mix.
- We will look at how Peugeot Invest Société anonyme’s stronger earnings on lower revenue may reshape its investment narrative for long term holders.
What Is Peugeot Invest Société anonyme's Investment Narrative?
To own Peugeot Invest Société anonyme, you need to be comfortable owning an investment holding vehicle where portfolio decisions, cost control and capital allocation drive most of the story rather than classic revenue growth. The latest half year figures fit that picture. Earnings and EPS moved up even as revenue fell sharply, which suggests a very lean cost base and a concentrated source of gains. For a holder, the near term narrative is about whether that mix of assets can keep throwing off high quality income without relying on one off wins.
In the short term, the key swing factors look operational rather than macro. Management has produced very high profit margins, while the share price has fallen about 30% year to date and the stock trades on a P/E of 5.5x. The new results do not erase existing concerns though. Forecasts still point to declining earnings, the dividend is not well covered by free cash flow and funding leans fully on higher risk sources such as external borrowing.
Yet there is one pressure point behind this capital allocation story that deserves a closer look once you start asking how sustainably the current profile can be maintained over time...
There's only one way to know the right time to buy, sell or hold Peugeot Invest Société anonyme. Head to Simply Wall St's company report for the latest analysis of Peugeot Invest Société anonyme's Fair Value.
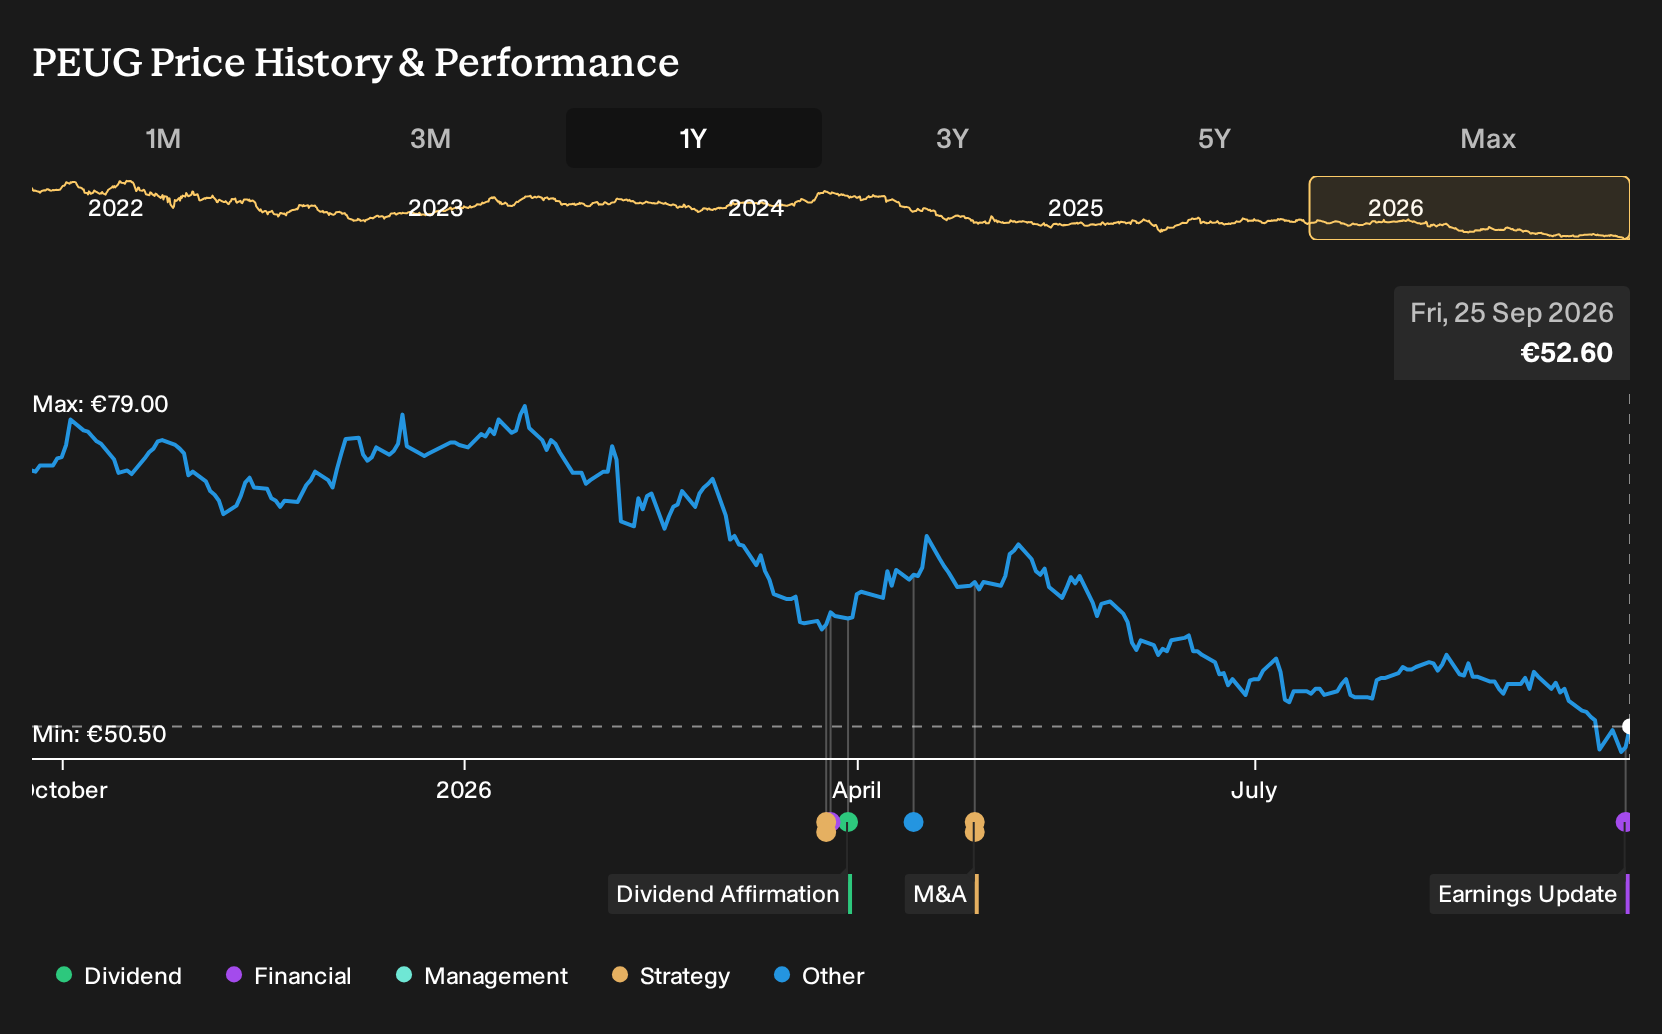
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community place Peugeot Invest Société anonyme between €52.58 and €86.25 per share, which already shows how far apart private investor opinions can be. These assessments were set before the latest half year earnings release, so the fresh profit profile may prompt you to revisit several alternative viewpoints.
Explore another Peugeot Invest Société anonyme fair value estimate, including one that suggests it could be worth just €52.58.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so rely on your own analysis.
- A useful starting point for your Peugeot Invest Société anonyme research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Peugeot Invest Société anonyme. The report includes a fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Peugeot Invest Société anonyme's overall financial position at a glance.
Looking For More Investment Ideas Beyond Peugeot Invest Société anonyme?
If Peugeot Invest Société anonyme has put quality and valuation on your radar, it can help to compare it with a wider set of companies that share similar financial traits but sit in very different corners of the market.
- If income strength is your priority, you could scan for resilient payout candidates by reviewing 162 dividend fortresses that match your yield and stability preferences.
- For investors who care most about balance sheet resilience, a helpful next step is to sift through our list of solid balance sheet and fundamentals (202 results) and see which businesses pair financial strength with fundamentals that suit your approach.
- If you are hunting for underfollowed opportunities, consider comparing Peugeot Invest Société anonyme with a curated 620 high quality undiscovered gems that show solid underpinning metrics but attract less market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com