
Synopsys (SNPS) Could Be 22% Undervalued As AI Chip Design Ties Deepen
Synopsys (SNPS) is back in focus after expanding its work with TSMC and Alchip on AI powered chip design tools, multi die packaging flows, and ultra high density data center interconnects that target demanding AI and HPC workloads.
Synopsys has been in the headlines for its AI and chip design partnerships, yet the share price, now at US$424.91, still shows a year to date share price return of down 11.55% and a 1 year total shareholder return of down 12.79%. At the same time, the 1 week share price return of 11.48% and 1 day move of 2.87% point to momentum rebuilding in the short term after a softer 90 day share price return of down 6.48% and a 3 year total shareholder return of down 7.77%, set against a much stronger 5 year total shareholder return of 41.92%.
Scan for other AI infrastructure plays showing similar demand signals by using our curated list of 87 AI infrastructure stocks as Synopsys deepens its ties with TSMC and Alchip.
After a sharp bounce, Synopsys still trades at a double digit discount to both intrinsic estimates and the average analyst target. Is that caution a bargain opportunity, or a sign the market is pricing risks correctly?
Most Popular Narrative: 22% Undervalued
On the most followed view, Synopsys screens as undervalued, with a fair value estimate of $545.93 set against the last close at $424.91. This frames the current discount as a debate over how much of the AI and Ansys story is already reflected in the price.
The acquisition and integration of Ansys positions Synopsys as the global leader in engineering solutions from silicon to systems, and new data showing Q3 FY26 Ansys revenue of about US$711 million and an expected FY26 contribution of about US$2.98 billion supports the view that this expanded portfolio can continue to influence top line growth and operating earnings as cross sell opportunities scale.
See why 161 investors see Synopsys as 22% undervalued.
Result: Fair Value of $545.93 (UNDERVALUED)
Still, the Synopsys story hinges on clean Ansys integration and a healthier IP mix, and setbacks on either front could undermine the current undervaluation case.
Find out about the key risks to this Synopsys narrative.
Another Angle On Synopsys Valuation
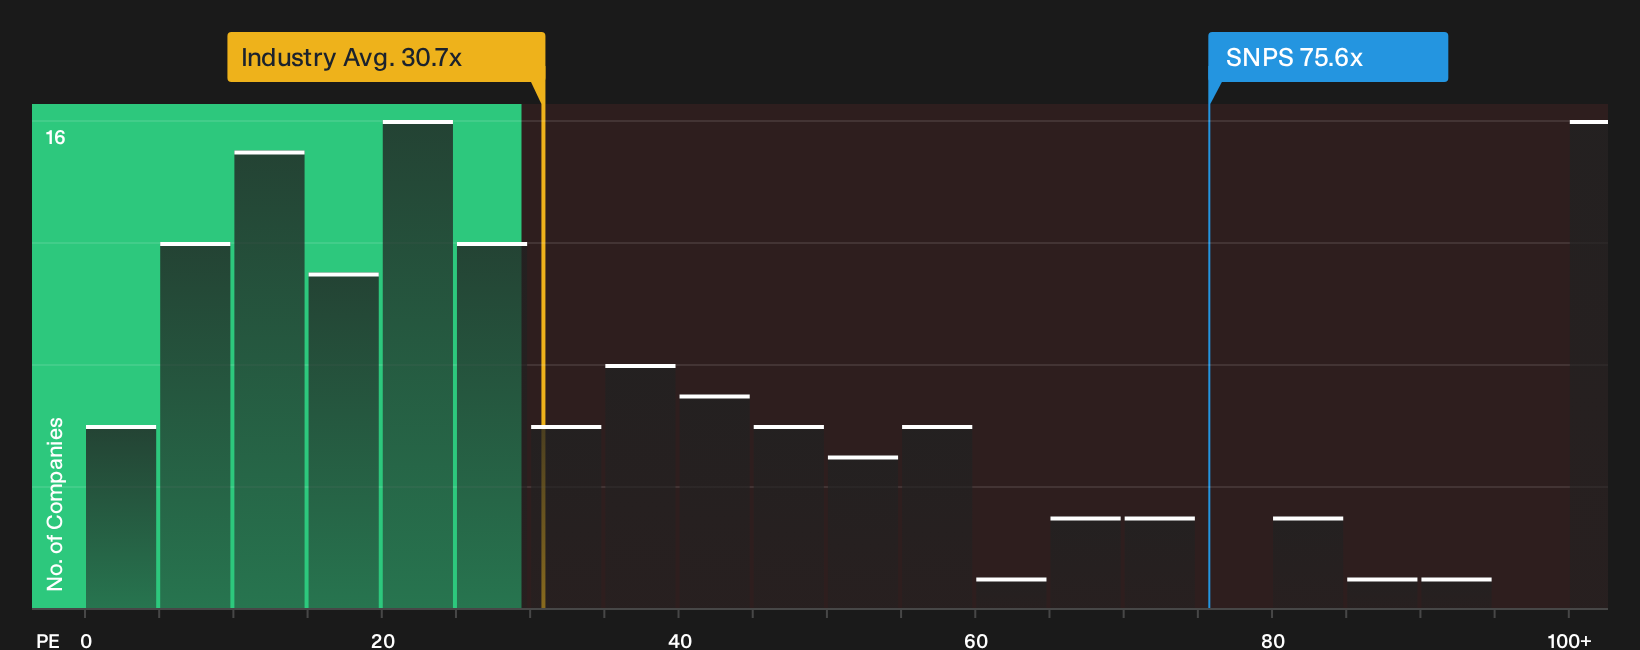
The first view leans on fair value estimates and analyst targets that point to Synopsys as undervalued. Using the earnings multiple tells a different story. At a P/E of 75.6x, the stock trades at more than double the US Software industry on 30.7x and ahead of peers on 32.5x. The fair ratio of 45.5x suggests the market could move toward a lower earnings multiple. Is that rich pricing a warning flag, or simply the cost of owning a premium AI and EDA platform?
Investors who want to see how this earnings based picture ties back to detailed valuation work can review the full breakdown in our valuation analysis See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Synopsys is split, with both concern and optimism in play. Investors may wish to move quickly, review the data, and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Synopsys?
If Synopsys has your attention, do not stop your research here. Broader opportunity hunting with a focused screener can reveal setups you might otherwise miss.
- Target potential mispricings by scanning a curated set of 30 high quality undervalued stocks that pair quality fundamentals with compressed expectations.
- Build a cash flow focused watchlist by filtering for 8 dividend fortresses that aim to combine income with balance sheet strength.
- Protect the downside first by concentrating on 30 resilient stocks with low risk scores that emphasise resilient financial profiles and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com