
Yelp (YELP) Stock Trades At A Discount On Its 56% Slide
Yelp has been under pressure, with a falling share price putting fresh focus on whether the current valuation matches what the business earns. With the stock back in the spotlight after recent declines, the core question is how well its earnings profile supports today's price.
- Over the past 3 years the share price has declined 55.8%, which puts a lot of weight on whether the earnings record can still justify the current market tag.
- Recent selling followed concerns that Meta's new AI assistant, Muse, could redirect product discovery away from traditional listings. This may affect how investors think about Yelp's future advertising income and the durability of its earnings base.
- Your read on Yelp is one view; the desks covering it have another. See what analysts think Yelp's shares could be worth.
The stock's next move may depend on whether these earnings are strong and resilient enough to support Yelp's current market valuation.
If you want to stress test how this same earnings question looks across a broader set of companies affected by AI shifts, scan the 30 high quality undervalued stocks.
Is Yelp a Bargain on Earnings?
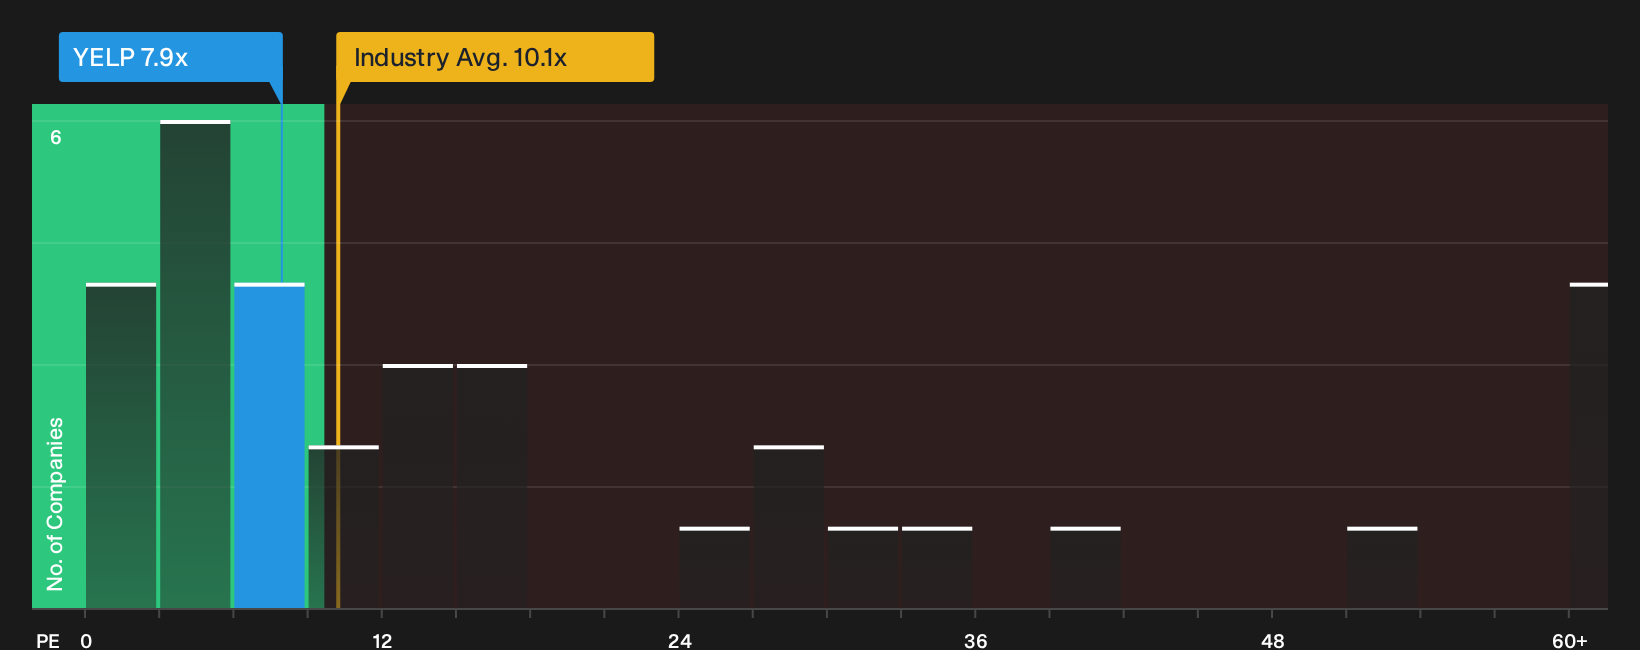
The P/E ratio is a useful yardstick for Yelp because earnings are a key driver of how investors weigh an ad supported platform. On this measure, the stock trades on about 7.9x earnings, which is below both the Interactive Media and Services industry average of roughly 10.1x and the peer group at about 8.9x. That gap suggests the market is assigning a lower earnings multiple to Yelp than to many comparable platforms with similar business models.
Because the fair value framework points to a higher P/E than where Yelp currently trades, this gap indicates the shares screen undervalued relative to what that model implies the business could support. Despite the sell off linked to Meta's Muse assistant and the concern that AI product discovery may weigh on ad demand, the current multiple still prices Yelp at a discount to both peers and the modelled fair level on earnings. Explore the numbers behind Yelp's P/E valuation.
The Yelp Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Yelp leaves off by spelling out which future paths for growth, margins and earnings would need to hold for the stock to look meaningfully cheaper or more expensive than today's price. Each one frames Yelp's fair value as a thesis about how the business might develop that you can revisit over time, rather than a single frozen snapshot, and they sit on the Community page for ongoing discussion.
One of the top community narratives on Yelp: roughly fairly valued
"Shifts toward AI-driven search, vertical integration by tech giants, and rising privacy rules threaten Yelp’s user engagement and core advertising-based business model..."
Discover why this Narrative puts Yelp at roughly fairly valued.
One more angle on Yelp that could change how you see the stock
There is a separate lens on Yelp that sits outside backward looking earnings altogether, where professional coverage sketches out what the next few years might look like and lets you compare that view with today's pricing. Explore where analysts expect Yelp to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com