
Seagate Technology Holdings (STX) Could Be 22% Undervalued As Buybacks Come Into View
Seagate Technology Holdings (STX) has completed a multi year balance sheet cleanup by settling its remaining 3.50% exchangeable notes due 2028, and has indicated that it plans to significantly increase share repurchases starting in 2027.
Recent enthusiasm around Seagate Technology Holdings’ role in AI and hyperscale cloud storage has coincided with a sharp move in the stock, with a 7 day share price return of 12.8% and a year to date share price gain of 215.1%. The 1 year total shareholder return of 315.8% and very large 3 and 5 year total shareholder returns suggest momentum has been building over both short and long horizons, despite a 1 day share price decline of 1.9%.
Spot similar AI infrastructure momentum by scanning our hand picked 87 AI infrastructure stocks that, like Seagate Technology Holdings, are tied directly to hyperscale cloud and data heavy workloads.Seagate Technology now appears to be a financially cleaner, AI-linked storage powerhouse trading at a premium share price after a substantial run. The key question is whether that quality is already fully reflected in the valuation.
Most Popular Narrative: 21.8% Undervalued
Seagate Technology Holdings closed at $905.92, while the most followed valuation story on the stock puts fair value closer to $1,158.73. That gap is built on a view that the supply and cost structure of nearline hard drives gives Seagate a very specific kind of pricing power.
The arithmetic of that shows up in the supply gap. Nearline HDD supply is expected to fall roughly 300 exabytes short of demand in 2026, a 10 to 15% shortfall, widening to something like 400 exabytes in both 2027 and 2028. Blended nearline pricing has been running near $14.30 to $14.90 per terabyte against scenarios that put it meaningfully higher over the next two years.
See why 4 investors see Seagate Technology Holdings as 22% undervalued.
According to isidrohg, who authored the most widely followed Seagate Technology Holdings narrative, that shortfall sits alongside a cost curve the business controls through HAMR based Mozaic drives. The narrative applies an 8.39% discount rate to those projected cash flows and arrives at a fair value that suggests the current price embeds a steep P/E multiple but not the full cash generation implied by the model.
That story leans heavily on three ingredients. First, earnings growth that was very large over the last year and has averaged 13.7% per year across five years. Second, profitability that currently carries a 26.1% net margin after moving higher from 16.3% a year ago. Third, an assumption that Seagate Technology Holdings can keep turning that margin profile into free cash flow without expanding capacity in a way that would erode the duopoly.
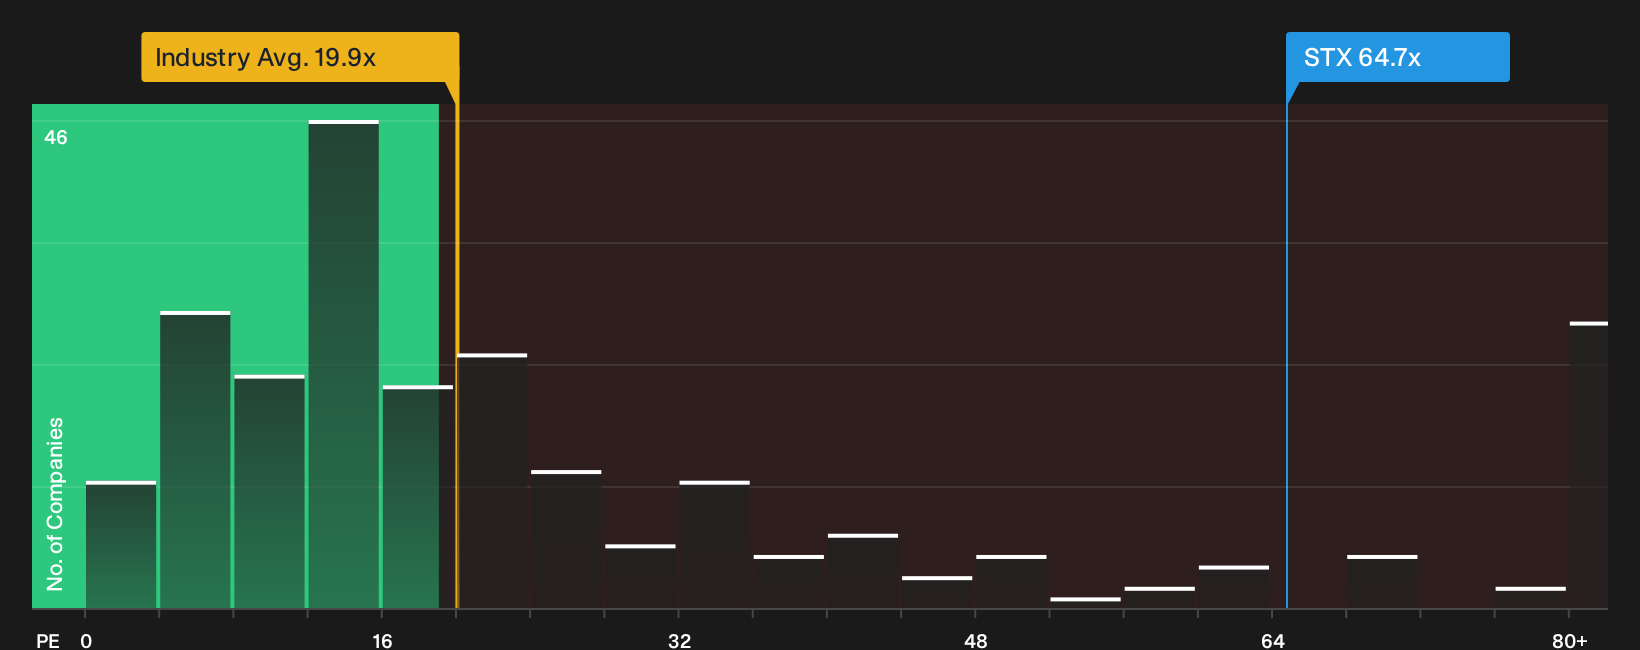
The same framework flags obvious tension points. The stock trades on a 64.7x P/E against an estimated fair P/E of 54.8x, which means the narrative asks investors to look past headline multiples and focus on discounted future cash flows instead. It also acknowledges a high level of debt that inflates return on equity to 146.93%, along with significant insider selling in recent months and an analyst target that sits more than 20% above the current quote without tight agreement among those analysts.
For readers weighing that story against the recent share price move of more than 300% on a 1 year basis, the key question is whether the current mix of earnings momentum, AI linked demand and balance sheet risk lines up with a fair value near $1,158.73 or something closer to today’s market price. The narrative leans toward the higher figure, but it also spells out what could break the thesis, including any sign that the HDD duopoly loses discipline or that Western Digital compresses the HAMR lead faster than expected.
Result: Fair Value of $1,158.73 (UNDERVALUED)
Still, Seagate Technology Holdings faces clear pressure points if Western Digital narrows the HAMR lead more quickly than expected or if either side breaks HDD capacity discipline.
Find out about the key risks to this Seagate Technology Holdings narrative.
Another View: What Seagate’s Rich P/E Is Telling You
There is a very different message coming from simple P/E math. Seagate Technology Holdings trades at 64.7x earnings compared with 25.4x for peers and 19.9x for the broader Global Tech group, and even above its own 54.8x fair ratio. That gap points to valuation risk if sentiment cools or growth expectations slip.
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Big swings in sentiment around Seagate Technology Holdings cut both ways, so move quickly to inspect the full picture and shape your own view. To see how the upside and downside stack up side by side, review the 3 key rewards and 3 important warning signs
Looking for more Seagate Technology investment ideas?
If Seagate Technology Holdings has sharpened your focus on AI infrastructure, do not stop here. Use the Simply Wall Street Screener to pressure test and broaden your watchlist.
- Spot potential mispriced opportunities by working through our hand picked 30 high quality undervalued stocks that combine quality fundamentals with discounted market prices.
- Strengthen capital preservation by scanning a curated 30 resilient stocks with low risk scores designed to highlight resilient businesses with lower risk profiles.
- Unearth lesser known prospects by reviewing a focused 16 high quality undiscovered gems that filters for strong fundamentals before wider attention arrives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com