
Top 3 Australian AI Stocks To Watch In September 2026
Bill Ackman argues that artificial intelligence could rewrite the usual rulebook for interest rates and demand. That debate matters for Australian AI shares that may be priced as if nothing is changing. When big money questions old models, re-rating risk grows on both sides. This article walks through three stocks from an Australian AI value screener to show where opportunity may sit for long term investors.
The three AI stocks below are just a sample from the wider opportunity set, and the full screen surfaced 0 more companies with equally detailed stories that are not covered here. To identify your own high conviction angles in this theme, head straight into the Undervalued Artificial Intelligence/ AI Stocks screener to filter and analyze the broader group of undervalued AI plays.
COSOL (ASX:COS)
Overview: COSOL provides AI enabled asset lifecycle and enterprise intelligence services that help asset heavy industries manage, maintain, and govern critical infrastructure data.
Operations: COSOL generates about A$54.9 million from Australian Consulting, A$30.7 million from Asset Management Services, and A$12.9 million from the Americas, largely across Asia Pacific.
Market Cap: A$35.5 million
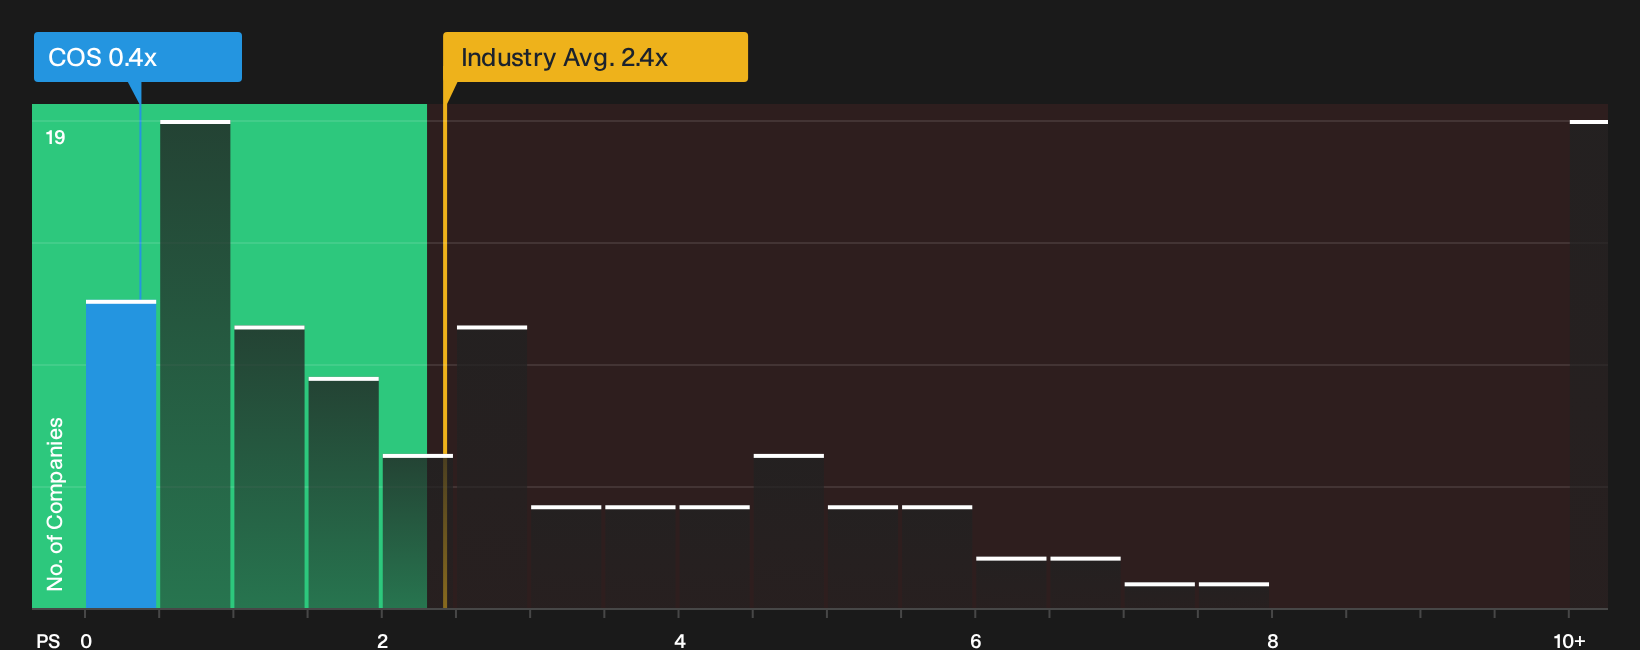
COSOL plugs AI directly into asset maintenance and data governance for utilities, resources, and infrastructure clients. It trades on a low P/S multiple and remains loss making after its 2026 result. Investors interested in AI that lives inside real world equipment may find upside here, depending on how one unseen pressure plays out.
That hidden pressure is exactly what the COSOL financial health report could help you unpack, before balance sheet realities swamp the AI story.
CAR Group (ASX:CAR)
Overview: CAR Group runs online vehicle marketplaces across multiple countries, using AI powered data, valuations and inspection tools to sharpen automotive buying and selling.
Operations: CAR Group earns about A$517.6 million from Australia, A$326.9 million from North America, A$252.9 million from Latin America, A$144.8 million from Asia, and A$11.2 million from Investments.
Market Cap: A$8.2 billion
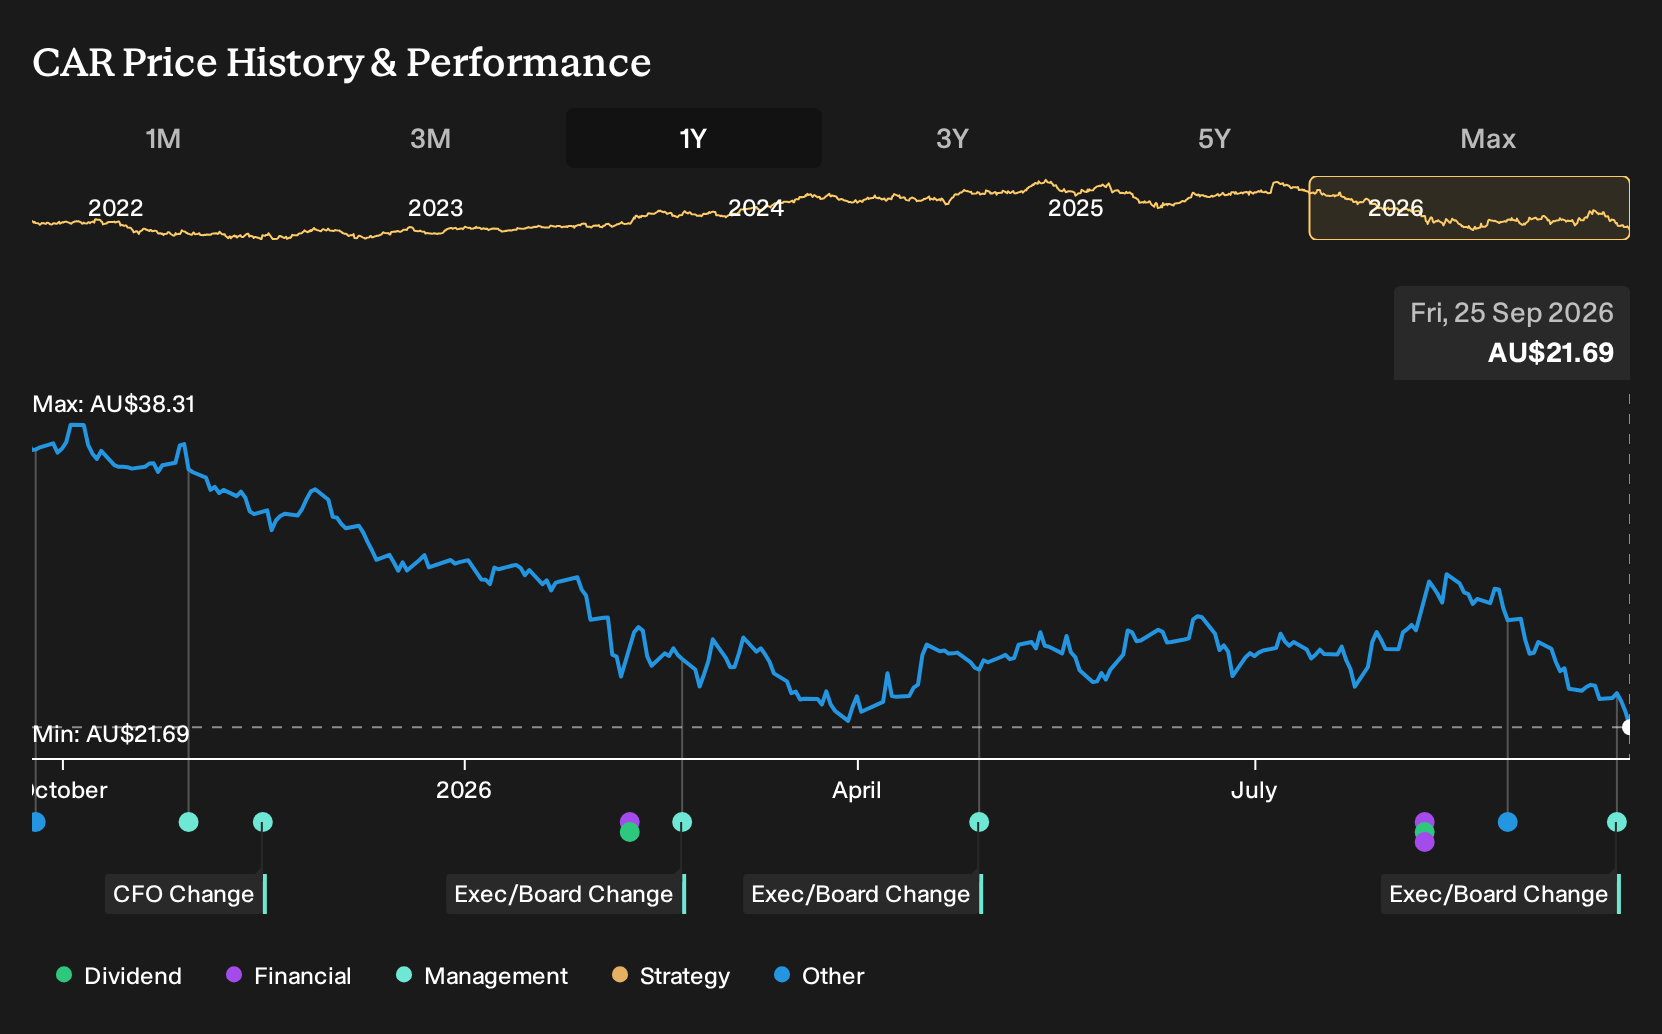
CAR Group matters for this AI screener because its classifieds engine is already wired into valuation algorithms, inspection tools, and marketplace analytics that lean on applied machine learning rather than blue-sky concepts.
"Per-share compounding as Encar / webmotors / US non-auto scale intrinsic; continuous."
What happens to that compounding profile if one unresolved funding and payout trade off starts to squeeze future AI build out?
That funding tension is exactly where the story gets interesting, so read the full narrative for CAR Group to see how CAR Group’s AI build out could accelerate or stall next.
Ai-Media Technologies (ASX:AIM)
Overview: Ai-Media Technologies delivers AI powered captioning, transcription, and translation services through its LEXI suite alongside traditional human captioning offerings.
Operations: Ai-Media generates about A$60.2 million from Internet Software & Services, with roughly A$41.4 million from North America, A$13.2 million from APAC, and A$5.7 million from EMEA.
Market Cap: A$53.6 million
Ai-Media Technologies matters for this AI screener because its LEXI engine brings real time speech recognition, translation, and captioning into everyday broadcast, streaming, and enterprise workflows.
"The transition from human-in-the-loop services to an AI-native workflow with the LEXI suite and encoders is increasing the share of higher margin SaaS in the mix, which directly supports gross margin and EBITDA outcomes."
What happens to Ai-Media’s earnings profile if a single assumption about future customer uptake of its AI language tools breaks?
That single assumption is what could flip Ai-Media Technologies from gradual shift to accelerating SaaS story, and the full narrative for Ai-Media Technologies unpacks how that risk and upside really balance.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities do not sit still. Breakout trends can gain momentum fast while older ideas may lose appeal. Scan these under the radar for now stock pools and consider where they might fit in your strategy.
- Identify cash rich businesses before momentum headlines catch up by running the list of solid balance sheet and fundamentals (12 results) and focusing on companies built to withstand real world shocks.
- Look for income focused companies with yields that could matter in a range of interest rate environments by reviewing the curated list of 3 dividend fortresses.
- Explore AI operators that are already generating revenue from their technology using the hand picked set of 37 profitable AI stocks that aren't just burning cash rather than those primarily focused on speculative narratives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com