
How UAE Launch Plans Will Impact Archer Aviation (ACHR) Investors
- Archer Aviation has been expanding its Midnight eVTOL commercialization push, including a UAE focused Launch Edition program and extended US flight testing with public demonstrations such as the California International Air Show.
- The mix of international regulatory work with the UAE aviation authority and real world tour routes such as Salinas to Hollister highlights how Archer Aviation is testing both infrastructure readiness and customer use cases at the same time.
- Attention now turns to how Archer Aviation's investment narrative could be affected by this international Midnight rollout and expanded demonstration activity.
Archer Aviation Investment Narrative Recap
To own Archer Aviation, you need to believe electric air taxis can move from test flights to scaled services across several regions, and that regulators will keep progress on certification and airspace integration on track. The Midnight tours in the US and the Launch Edition work in the UAE feed directly into that belief, but they do not change the core short term swing factor. The near term hinge still looks like certification timing and how that lines up with launch customers and infrastructure.
Where this recent news matters is operational proof. More flights, more routes and more regulators in the mix help stress test the aircraft and ground ecosystem in real conditions. The biggest risk does not really move, though. Archer is still spending heavily while being unprofitable, so any slippage in defense awards, launch edition activity or software adoption could keep cash burn high relative to income.
The UAE focused Launch Edition program is the clearest link between the tour headlines and the deeper story. That push into a high profile early adopter market connects Midnight certification work with real route planning, vertiport preparation and airspace coordination. For you as a shareholder, the interesting part is how this might shorten the path from a backlog of interest to actual service entry, if regulators and partners stay aligned.
That same announcement also ties directly into the main catalysts analysts highlight, including the global backlog and preparations for large, event driven operations such as the 2028 Olympics. Aligning with the UAE aviation authority gives Archer another regulatory track in parallel to FAA progress. It also increases exposure to geopolitical, public acceptance and policy risks in those launch regions, which sit alongside execution on hybrid defense aircraft and software as key pillars of the long term story.
Archer Aviation's narrative projects revenues of US$716.0 million and earnings of US$62.9 million by 2029. This reflects revenue growth assumptions of 622.3% per year and an earnings swing of about US$805.4 million, from a current loss of US$742.5 million to the forecast profit.
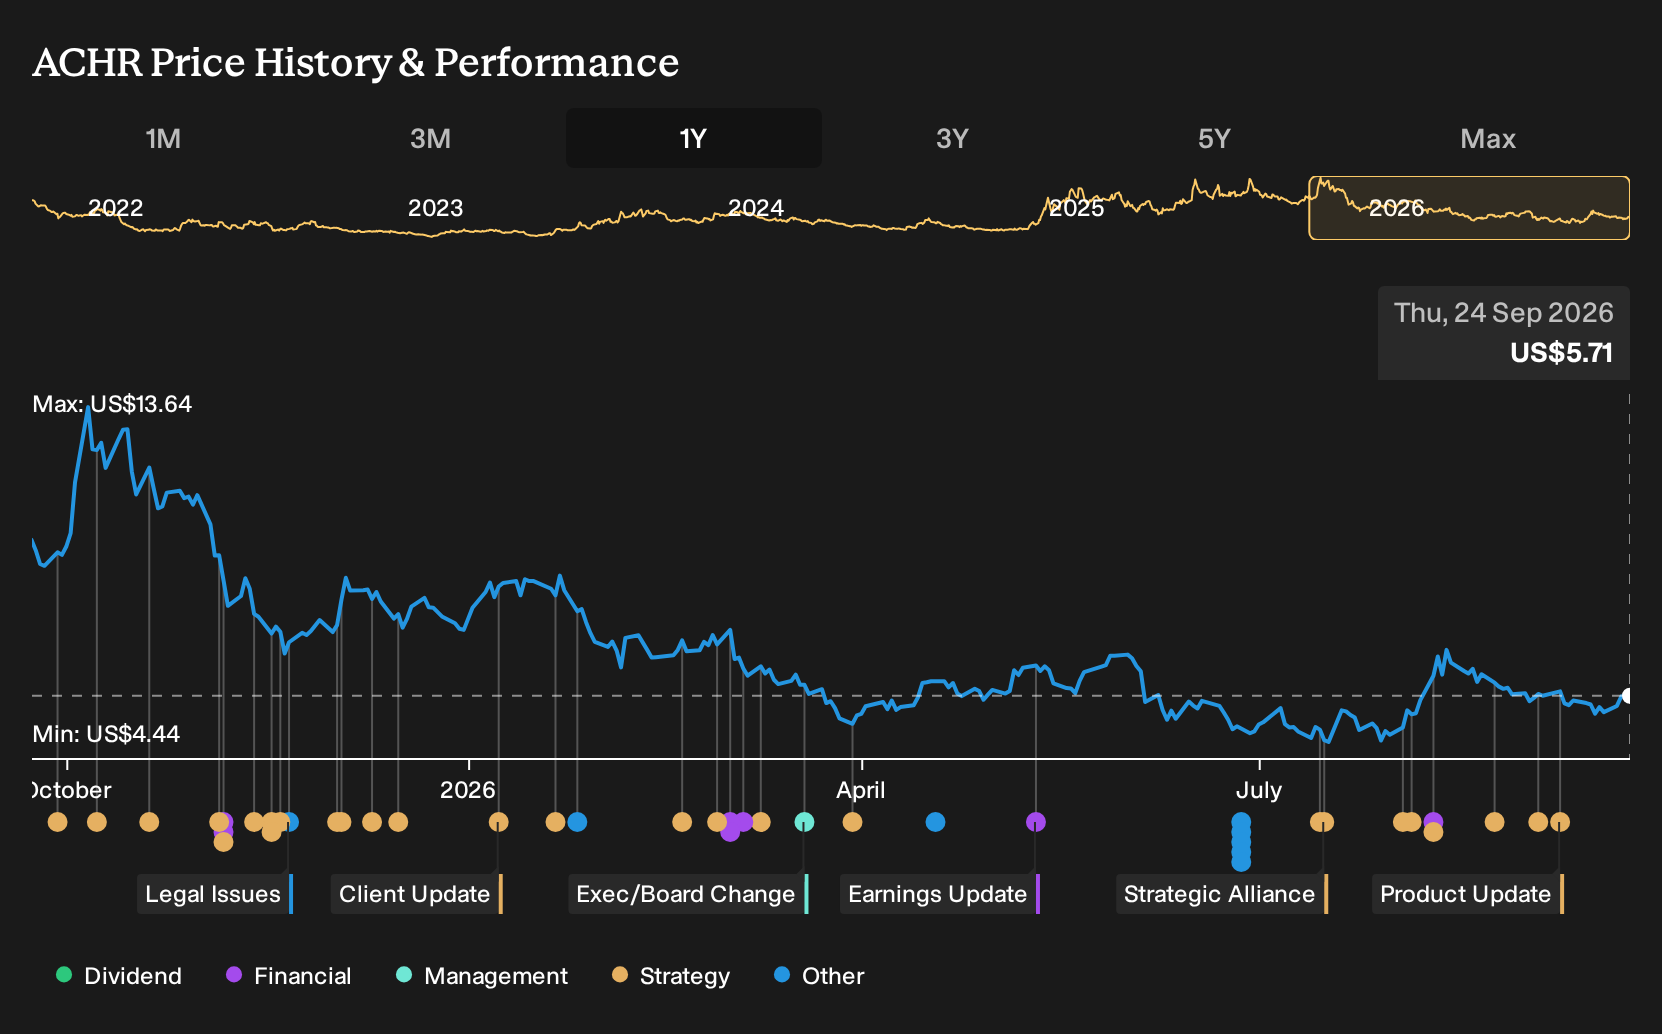
Uncover why Archer Aviation's fair value indicates an 86% potential upside to its current price. This discount could close more quickly than many investors expect.
Exploring Other Perspectives
One alternate view focuses on public acceptance risk. While Archer Aviation’s air show tours aim to excite future riders, the most cautious analysts worry that comfort with low altitude aircraft could stay limited. Before this news, they were working with 2029 revenue around US$199.7 million and earnings of US$17.0 million, pointing to a far more restrained story that could shift as these demonstrations play out.
Explore 9 other Archer Aviation fair value estimates, including one that suggests it could be worth just $10.61!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Archer Aviation research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Archer Aviation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Archer Aviation's overall financial health at a glance.
Looking For More Investment Ideas Beyond Archer Aviation?
If Archer Aviation's story has sharpened your thinking about risk, reward and timing, it can help to line it up against a wider watchlist. The Simply Wall St Screener lets you quickly filter for different traits so you can compare this stock with other businesses that match your preferred mix of quality, value and resilience.
- If you prefer to focus on companies that already generate strong cash flows at a discount to intrinsic value, and want a shortlist that reflects that bias, then start with a 30 high quality undervalued stocks.
- If capital preservation matters more than chasing every big swing, you might appreciate a 30 resilient stocks with low risk scores that filters for steadier balance sheets and calmer risk profiles.
- For readers hunting for less crowded stories with solid fundamentals, a 16 high quality undiscovered gems can surface under-the-radar opportunities that still clear quality checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com