
3 Oil Stocks Investors Are Watching As Brent Pulls Back
Oil markets just got a plot twist. Saudi crude exports have rebounded to 6 million barrels per day while Brent’s spike toward $110 has eased, and that mix of supply relief and lingering risk is reshaping how investors think about integrated energy stocks. If you care about how shipping routes, pipelines and war risk can sway your portfolio, keep reading as this article walks through 3 stocks exposed to this news shock.
The stocks covered below are just a starting sample. The full screen on Simply Wall St surfaced 7 more global integrated oil and gas producers with equally compelling narratives that are not included in this article.
To go beyond the headline names, head straight into the Global Integrated Oil & Gas Producers screener to identify potential fits, analyze their fundamentals, and focus on the opportunities that best match your own conviction level.
GeoPark (GPRK)
GeoPark is one of the purest ways to play the Global Integrated Oil & Gas Producers theme through Latin American barrels that link directly into Brent pricing, giving you a focused upstream story that still taps into global crude flows.
GeoPark Limited is an oil and natural gas exploration and production group active across Latin America, with its business entirely tied to Oil & Gas Exploration & Production that generated about US$507 million in revenue, primarily from Colombia, and a market value of roughly US$729 million.
"GeoPark is actively implementing new drilling and extraction technologies, optimized well interventions, and modular field developments that are significantly reducing operating costs (for example, more than a 30% cut in average well costs, energy-saving interventions, and innovative water management)."
What happens to GeoPark’s margin profile and cash generation if one key cost pressure in its Latin American projects moves in the right direction.
If that cost pressure is easing for GeoPark, read the full narrative for GeoPark to see how drilling efficiency, contract structure, and capital choices could be quietly accelerating value.

SM Energy (SM)
SM Energy gives this screen pure upstream exposure, with a single focus on drilling and production that is closely tied to global oil benchmarks rather than refining or retail. This puts its operating decisions front and center when crude markets settle into a higher but steadier range.
SM Energy Company is a US based independent producer focused on acquiring, exploring and developing oil, gas and natural gas liquids, generating about US$4.96b from its exploration and production segment, entirely in the United States, and carrying a market value of roughly US$8.2b.
"The company's ability to increase both net proved reserves and net production by over 60% since 2020, while also improving production margins and keeping share count flat, demonstrates ongoing operational excellence and scale, allowing for per-share financial growth and potential improvements in operating margins and earnings."
What happens if a single assumption about how quickly Uinta and Midland wells can keep supporting that progress starts to shift?
If that single assumption is shifting, go straight to the full narrative for SM Energy to see whether SM Energy’s reserve trajectory is accelerating or masking deeper well risk.
Talos Energy (TALO)
Talos Energy plugs directly into the Global Integrated Oil & Gas Producers theme through offshore crude production in the U.S. and Mexico, giving you a Gulf focused upstream operator where execution on its efficiency agenda could matter as much as day to day oil price swings.
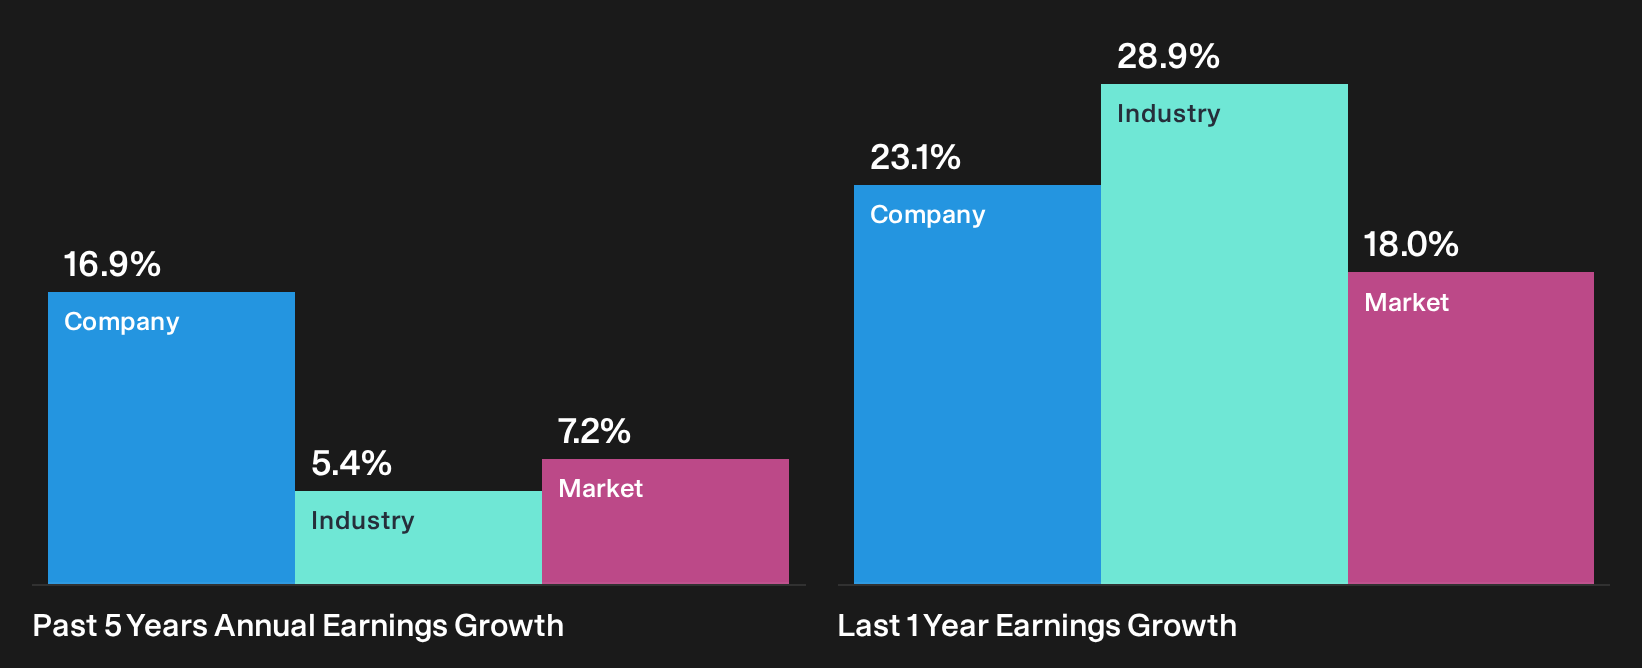
"Talos Energy is executing a targeted $100 million per year initiative in operational efficiencies and cost reductions (capital efficiency, logistics, margin enhancement), expected to have a sustainable, recurring impact on free cash flow starting in 2026, which should enhance net margins and overall earnings."
What happens to Talos Energy’s valuation and balance sheet strength if one unseen pressure on those Gulf projects moves in the wrong direction?
If that unseen pressure is your concern, read the full narrative for Talos Energy to see whether Talos Energy’s efficiency push is accelerating value or quietly masking new risks.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first, and slow research often gets caught chasing prices once momentum is already flying. Scan new themes while they are still under the radar for now and look for opportunities early.
- Spot early uptrends in niche resource players by scanning the curated 36 best rare earth metal stocks before money rotates in and the best entries start dropping away.
- Track cash generating miners with real balance sheet strength using the focused 36 elite gold producer stocks while sentiment is still forming and before any breakout move draws a crowd.
- Target steady cash flows and income resilience through the curated 8 dividend fortresses while yields remain elevated and market attention is elsewhere, then act while it matters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com