
Did Rebrand To Champion Homes Just Shift Champion Homes (SKY) Stock Narrative?
- Champion Homes, formerly Skyline Champion Corporation, has completed a rebrand that sharpens its identity around factory-built housing across the United States and Canada.
- The refreshed Champion Homes branding highlights a clear focus on affordable, off-site construction at a time when housing policy and buyer interest are closely tracking this segment.
- We will now look at how Champion Homes' sharper factory-built housing focus could influence the existing investment narrative around off-site construction.
Compare Champion Homes' renewed factory-built focus with a curated 30 high quality undervalued stocks list that is also tied to structural housing themes and currently trades below intrinsic estimates.
Champion Homes Investment Narrative Recap
To own Champion Homes you need to believe factory-built housing keeps gaining share as buyers and policymakers look harder at affordability. The rebrand sharpens that message but does not change the near term reality. Order softness in some channels, cautious lower income customers and moderating backlogs still look like the key operational swing factors.
The most important short term catalyst remains how Champion Homes converts policy support and builder interest into consistent volumes across U.S. and Canadian plants. The biggest risk is that material costs, tariffs or discounting to move inventory pressure margins while demand in community and independent dealer channels stays uneven.
The recent rebrand from Skyline Champion to Champion Homes is the clearest recent announcement linked to this story. Management is now presenting the business as a pure factory-built housing platform, from single family manufactured units through to modular commercial structures. This tightens the message for customers, communities and regulators.
For you as a shareholder, the question is whether this clearer identity helps Champion Homes execute on its existing catalysts. That includes policy momentum like the ROAD to Housing Act, interest from builders in off site construction and expansion into higher margin multifamily and commercial modular segments, without masking ongoing demand, cost and inventory risks.
Champion Homes' current analyst narrative points to revenue of US$3.3b and earnings of US$278.2 million by 2029. That profile assumes yearly top line growth of 7.2% and an increase in earnings of about US$86.8 million compared to the US$191.4 million reported today.
Uncover why Champion Homes' fair value indicates a 21% potential upside to its current price, which could narrow quickly.
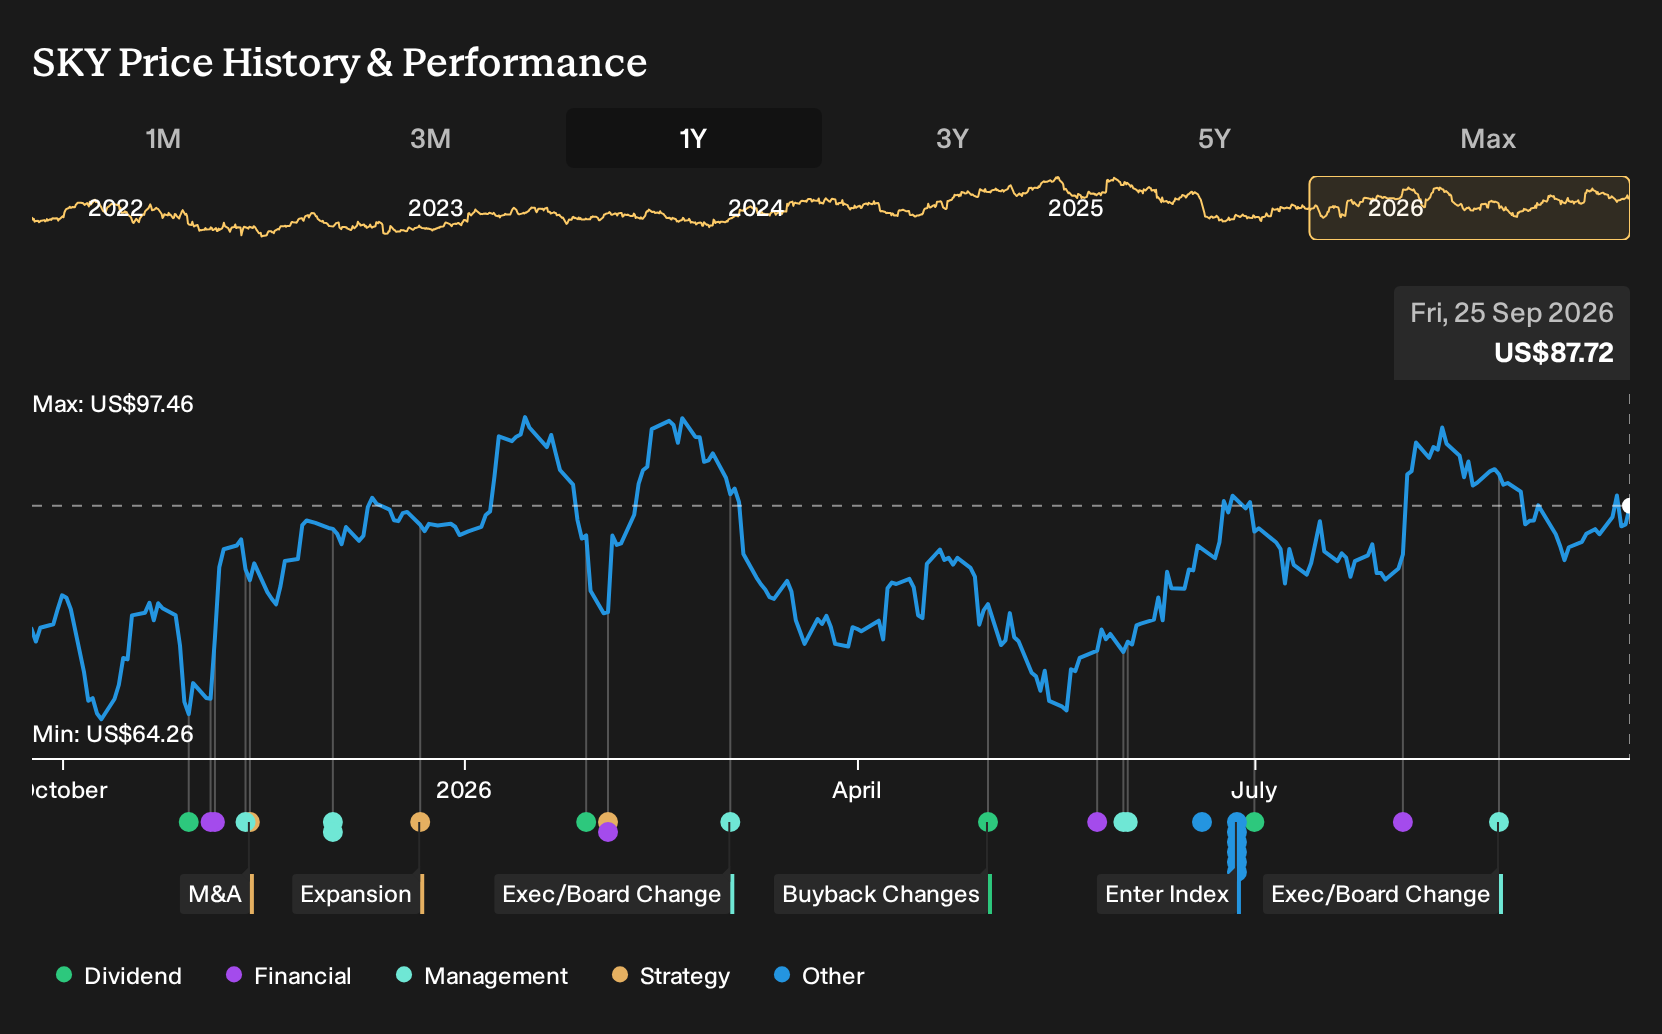
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community cluster between US$85 and about US$104 per share, with one view at the upper edge pointing to materially richer pricing than the low end. These private investors have not yet factored in Champion Homes' rebrand, evolving housing policy support or the risk of softer orders and cautious buyers. Opinions clearly diverge. You can use these contrasting views as a springboard to explore several alternative takes on where Champion Homes might fit in your portfolio.
Explore 2 other Champion Homes fair value estimates, including one that suggests it could be worth just $85.00.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Champion Homes research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Champion Homes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Champion Homes' overall financial health at a glance.
Looking for more investment ideas beyond Champion Homes?
Once you have a view on Champion Homes, it can help to cross check that thesis against other opportunities with similar or contrasting traits using the Simply Wall St Screener.
- If you want a focus on resilience, start with a 30 resilient stocks with low risk scores that filters for businesses where volatility and balance sheet risk scores both look more controlled.
- For income oriented investing, scan a curated 8 dividend fortresses built around companies offering higher yields with an emphasis on stability.
- When you are hunting for potential mispricings, compare your Champion Homes view with a 16 high quality undiscovered gems that highlights under followed stocks showing strong fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com