
SHIFT (TSE:3697) Could Be 41% Undervalued Following FTSE All World Index Removal
SHIFT Inc. (TSE:3697) was recently removed from the FTSE All-World Index, a move that can prompt forced selling by index-tracking funds and reshape how investors think about liquidity and attention on the stock.
For SHIFT, the removal comes after a mixed share price pattern, with a 30-day share price return down 5.83% but a 90-day share price return up 41.75%. Meanwhile, the 1-year total shareholder return declined 33.51%, which hints that recent momentum has picked up even as longer term holders remain under pressure and may be more sensitive to perceived changes in risk.
Spot opportunities other investors may be overlooking by scanning our curated 74 high quality undiscovered gems. Like SHIFT after its index removal, these sit outside the major benchmarks yet remain firmly tied to underlying fundamentals.SHIFT has been hit hard over 1 year yet bounced sharply over 3 months, which leaves you with a practical choice. Step in after the index exit or wait for a cleaner valuation signal in the next section.
SHIFT valuation: is the premium price still justified?
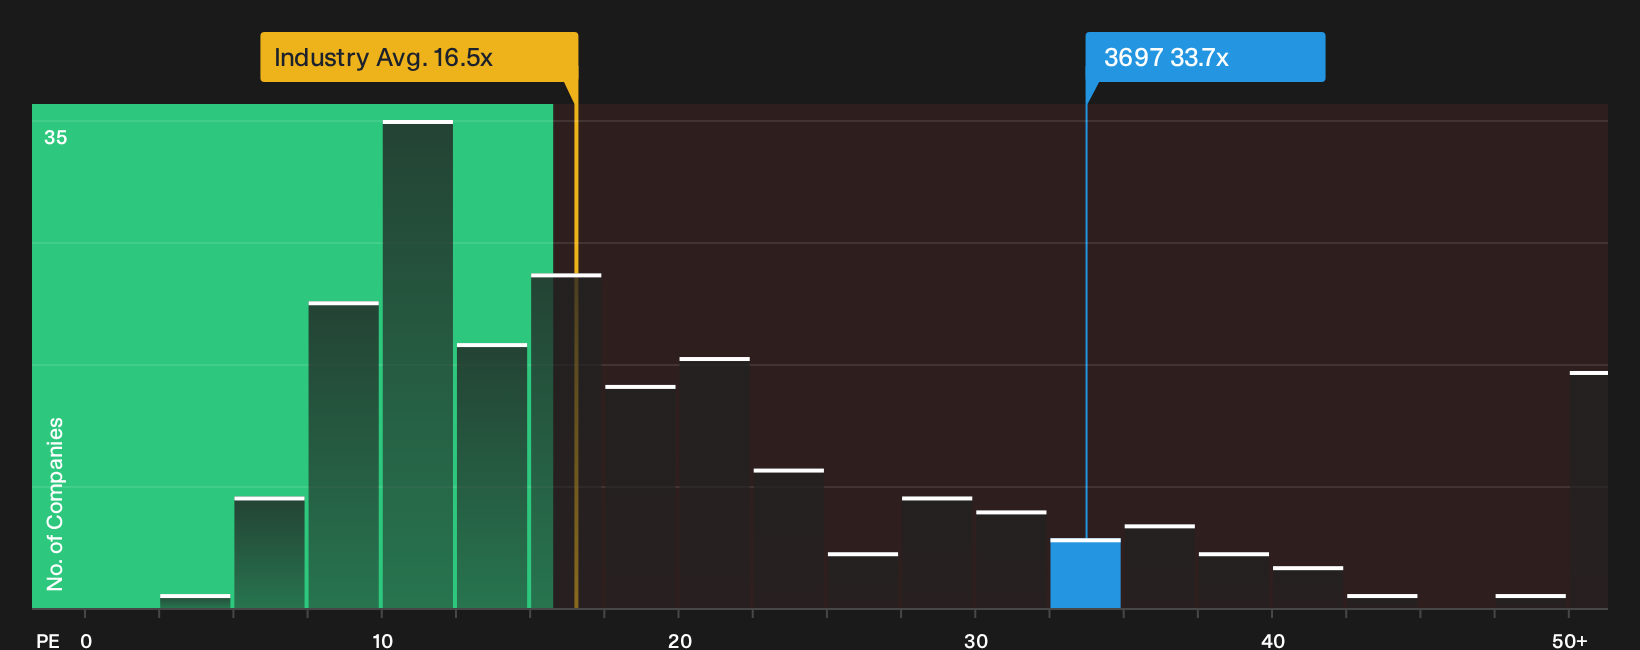
SHIFT closed at ¥874.6 while trading on a P/E of 33.7x, which puts a clear premium on the shares compared with both IT peers and the wider Japanese market.
The P/E ratio compares what you pay today for each unit of current earnings. For a software testing specialist like SHIFT, that multiple often reflects how investors weigh earnings quality, expected profit growth and the predictability of its business model rather than just the latest headline result.
Here the picture is mixed. The stock looks expensive against the JP IT industry on a simple P/E basis, with SHIFT at 33.7x compared with 16.5x for the sector and 18.6x for its peer group average. At the same time, the fair P/E estimate sits higher at 44.4x, which signals a level the market could potentially move toward if the firm delivers on its forecast 41.8% annual earnings growth and maintains what is described as high quality earnings.
Explore the SWS fair ratio for SHIFT.
Result: Price-to-earnings of 33.7x (ABOUT RIGHT)
Alongside the multiple view, the SWS DCF model suggests SHIFT at ¥874.6 is trading below an estimated future cash flow value of ¥1,478.31, implying a 40.8% discount to that internal fair value estimate. The approach projects future cash flows, then discounts them back to today using a required rate of return to account for timing and risk.
For SHIFT, which has forecast annual earnings growth of 41.8% and revenue growth of 15.6%, that framework places more weight on the longer term profit path than on last year's weaker margins and earnings decline. It also helps explain why the model can point to undervaluation even while the near term P/E looks rich versus the IT industry and peer averages.
Look into how the SWS DCF model arrives at its fair value.
Result: DCF Fair value of ¥1,478.31 (UNDERVALUED)
Still, the narrative around SHIFT can quickly change if its 15.6% revenue growth slows or if the 33.7x P/E compresses as sentiment cools after index removal.
Find out about the key risks to this SHIFT narrative.
Another view on SHIFT using P/E and fair ratio
SHIFT screens as expensive on a simple P/E check, at 33.7x versus 16.5x for the JP IT industry and 18.6x for its peer group. The fair ratio of 44.4x sits higher again, which suggests that the market could still re rate the shares if earnings forecasts remain in place.
The gap between today’s 33.7x and the 44.4x fair ratio highlights both potential upside and valuation risk if sentiment weakens or forecasts are revised. For a stock that has already lagged the JP market over 1 year, investors may wish to consider which side of that trade off feels more compelling.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SHIFT for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted on what SHIFT’s mixed signals really add up to right now and whether the recent index exit tilts risk or opportunity more. Move quickly to review the underlying data, then weigh both the potential upside and the pressure points by checking the 2 key rewards and 2 important warning signs
Looking for more SHIFT investment ideas?
If SHIFT has you rethinking where the best risk reward trade offs might lie, broaden your watchlist with a few focused stock ideas built from our screeners.
- Target resilient income first and scan for companies with strong payouts and balance sheets using the 14 dividend fortresses.
- Hunt for quality at a discount by reviewing the 18 high quality undervalued stocks that match strict value and fundamentals filters.
- Protect your capital more aggressively and comb through 21 resilient stocks with low risk scores that score well on financial strength and risk checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com