
Atlanticus Holdings (ATLC) Could Be 31% Undervalued As Conference Focus Returns
Atlanticus Holdings (ATLC) is back in the spotlight after management’s scheduled appearance at the U.S. Bancorp | BTIG Consumer Finance Conference on 17 September 2026 in Boston, putting its specialty lending model under fresh scrutiny.
Recent moves in Atlanticus Holdings reflect that tension between growth hopes and risk worries. The share price is at US$92.50 after a 1-day share price return of 1.21%, while the 90-day share price return is down 16.22%. At the same time, the year-to-date share price return sits at 39.41% and the 3-year total shareholder return reaches about 205%, suggesting longer term momentum remains strong even as short term sentiment cools ahead of the conference and after the Auto Finance sale announcement.
Capitalize on the volatility around Atlanticus Holdings by scanning a hand-picked 16 high quality undiscovered gems that could be setting up for their own conference driven re-rating.Atlanticus Holdings now appears to be a profitable specialist lender with a simplified model and renewed analyst optimism, yet a 16% pullback in 90 days muddies the picture. Are you paying up for quality, or getting it on sale?
Most Popular Narrative: 31% Undervalued
Atlanticus Holdings closed at $92.50 while the most followed narrative framework lands on a fair value around $133.50. As a result, the conference arrives with analysts already treating the stock as discounted against their modelled cash flows and earnings power.
The acquisition and integration of Mercury Financial has roughly doubled the balance sheet to about US$7b and brought a US$3b portfolio under Atlanticus portfolio management methods. Management expects this to support higher yields and return on assets over time, directly influencing revenue and earnings.
See why 5 investors see Atlanticus Holdings as 31% undervalued.
Result: Fair Value of $133.50 (UNDERVALUED)
Still, the Atlanticus Holdings story can change quickly if near prime customers come under pressure or if the Mercury integration takes longer than planned.
Find out about the key risks to this Atlanticus Holdings narrative.
Another View: P/E Signals On Atlanticus Holdings
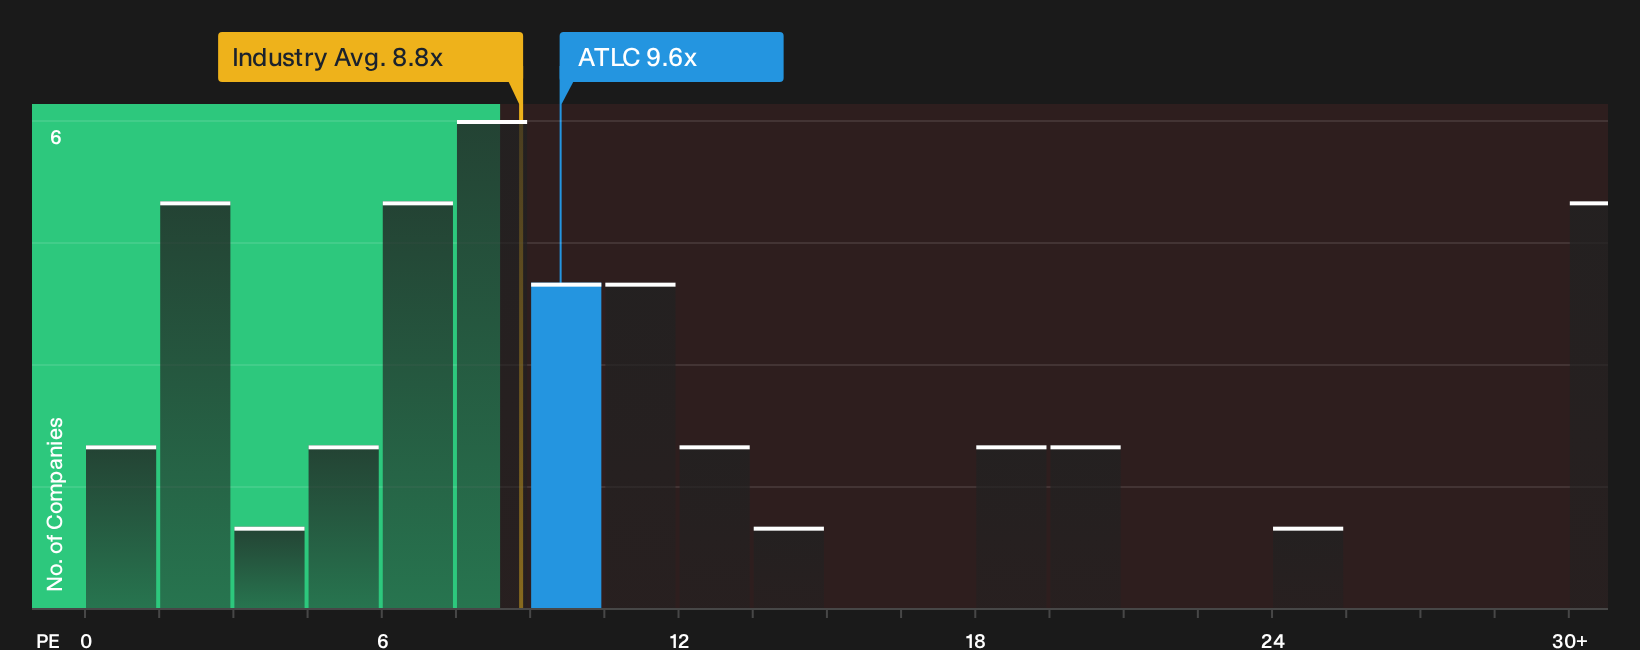
The most popular narrative has Atlanticus Holdings trading at a discount to an implied fair value of $133.50. The P/E picture complicates that. ATLC changes hands at 9.6x earnings, which is below the US market at 18x, yet above the US Consumer Finance industry at 8.7x.
Simply Wall St’s fair ratio for Atlanticus Holdings is 20.1x, more than double the current multiple. That gap highlights potential upside if the market prices ATLC closer to that fair ratio in the future, and also highlights valuation risk if investors continue to treat consumer finance stocks cautiously. Which side of that tradeoff are you more comfortable owning?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Atlanticus Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Atlanticus Holdings can feel confusing, so move quickly from reading to testing the numbers yourself, weighing both optimism and concern. To see how others are balancing those cross currents, review the 3 key rewards and 2 important warning signs
Looking for more Atlanticus Holdings investment ideas?
If Atlanticus Holdings has your attention, do not stop here. Broaden your watchlist now, or you risk missing opportunities sitting in plain sight.
- Target strong value potential early by scanning companies flagged as 30 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect their financial profile.
- Protect your downside by reviewing a 30 resilient stocks with low risk scores that focuses on businesses with more resilient risk scores and fewer red flags in their financial checks.
- Strengthen your portfolio’s foundation by using a list of solid balance sheet and fundamentals (24 results) to focus on companies with healthier leverage, liquidity, and asset coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com