
Hope Bancorp (HOPE) Cuts Funding Costs, Is The Margin Story Still Undervalued?
Recent analysis of Hope Bancorp (HOPE) focuses on how reduced reliance on higher cost brokered deposits, fresh low cost funding from the Territorial acquisition, and portfolio shifts into higher yielding assets could influence its net interest margin.
At a share price of $13.83, Hope Bancorp has logged a 25.96% year to date share price return. Its 1 year total shareholder return of 33.06% and 3 year total shareholder return of 81.56% point to momentum that has been building rather than fading.
Scan for other regional lenders following a similar funding and margin playbook as Hope Bancorp by reviewing the hand picked list of solid balance sheet and fundamentals (24 results).
After an 81.56% three year total return and a 33.06% gain over the past 12 months, the question around Hope Bancorp now shifts: Does the current valuation still compensate you for the funding and margin risks on the table, or has most of the upside already been claimed?
Most Popular Narrative: 9% Undervalued
Against a last close of $13.83, the most followed narrative for Hope Bancorp anchors on a fair value of $15.25, leaving a modest valuation gap that hinges on whether management can sustain margin gains and cost control.
Significant ongoing investment in digital platform enhancements and fintech partnerships is described as likely to improve operational efficiency and customer retention, which in turn could support a lower cost-to-income ratio and stronger net margins over time.
See why 7 investors see Hope Bancorp as 9% undervalued.
Result: Fair Value of $15.25 (UNDERVALUED)
Still, the Hope Bancorp story can change quickly if commercial real estate credit quality worsens, or if integration costs from the Territorial deal stay higher for longer.
Find out about the key risks to this Hope Bancorp narrative.
Another View On Hope Bancorp’s Valuation
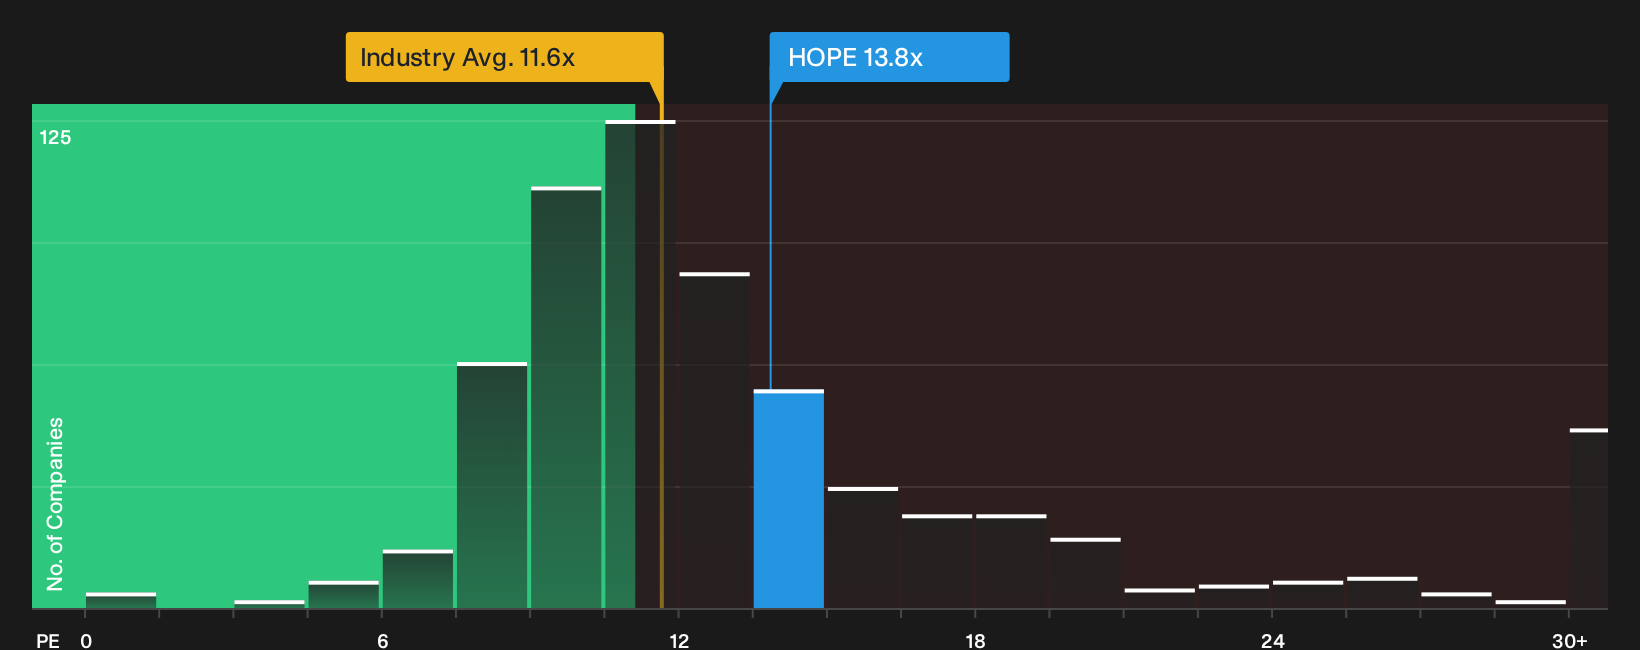
The story looks different once the P/E is front and center. Hope Bancorp trades on 13.8x earnings compared with 11.6x for the US Banks group and a peer average of 19.6x. The fair ratio sits at 16.9x, which suggests some valuation risk if sentiment shifts, but also room if the market edges closer to that fair ratio.
That mix of premium to the sector, discount to peers, and a higher fair ratio keeps the question wide open. Has the easy multiple expansion already played out, or is the P/E just pausing before it moves toward the fair ratio over time?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Hope Bancorp in this piece is mixed, with clear upside arguments alongside pointed concerns. Move quickly and pull the raw data, then weigh both sides yourself by reviewing the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Hope Bancorp?
You have a clear view on Hope Bancorp now. Do not stop there when a few targeted screeners can surface other opportunities that might suit your portfolio mix.
- Target income resilience and stress test your yield strategy by reviewing a focused set of higher yielding payers through the 8 dividend fortresses.
- Hunt for mispriced quality and pressure test your valuation instincts by scanning the curated 31 high quality undervalued stocks.
- Filter for staying power and reduce blow up risk by running your next watchlist through the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com