
3 US Defense Stocks To Watch As Rising Treasury Yields Reshape Income Trades
Higher long-term Treasury yields are pulling investor attention back to “risk-free” income just as Washington weighs heavier fiscal and defense spending. That mix can punish some stocks while creating pockets of resilience in areas like US defense contractors. This piece walks through three large US-listed defense companies exposed to these macro forces and shows how the same bond story can mean very different things for each stock.
The stocks covered below are just a small sample of larger US-listed defense contractors, and the wider screen surfaced 24 more companies with equally compelling stories that are not broken out in this article.
To see the full US defense set in one place, analyze and identify your own highest conviction ideas by going straight to the US Defense Contractors screener.
Hexcel (HXL)
Overview: Hexcel supplies advanced carbon fiber composites and structural components that help make modern military aircraft, missiles, space systems, and commercial jets lighter and more efficient.
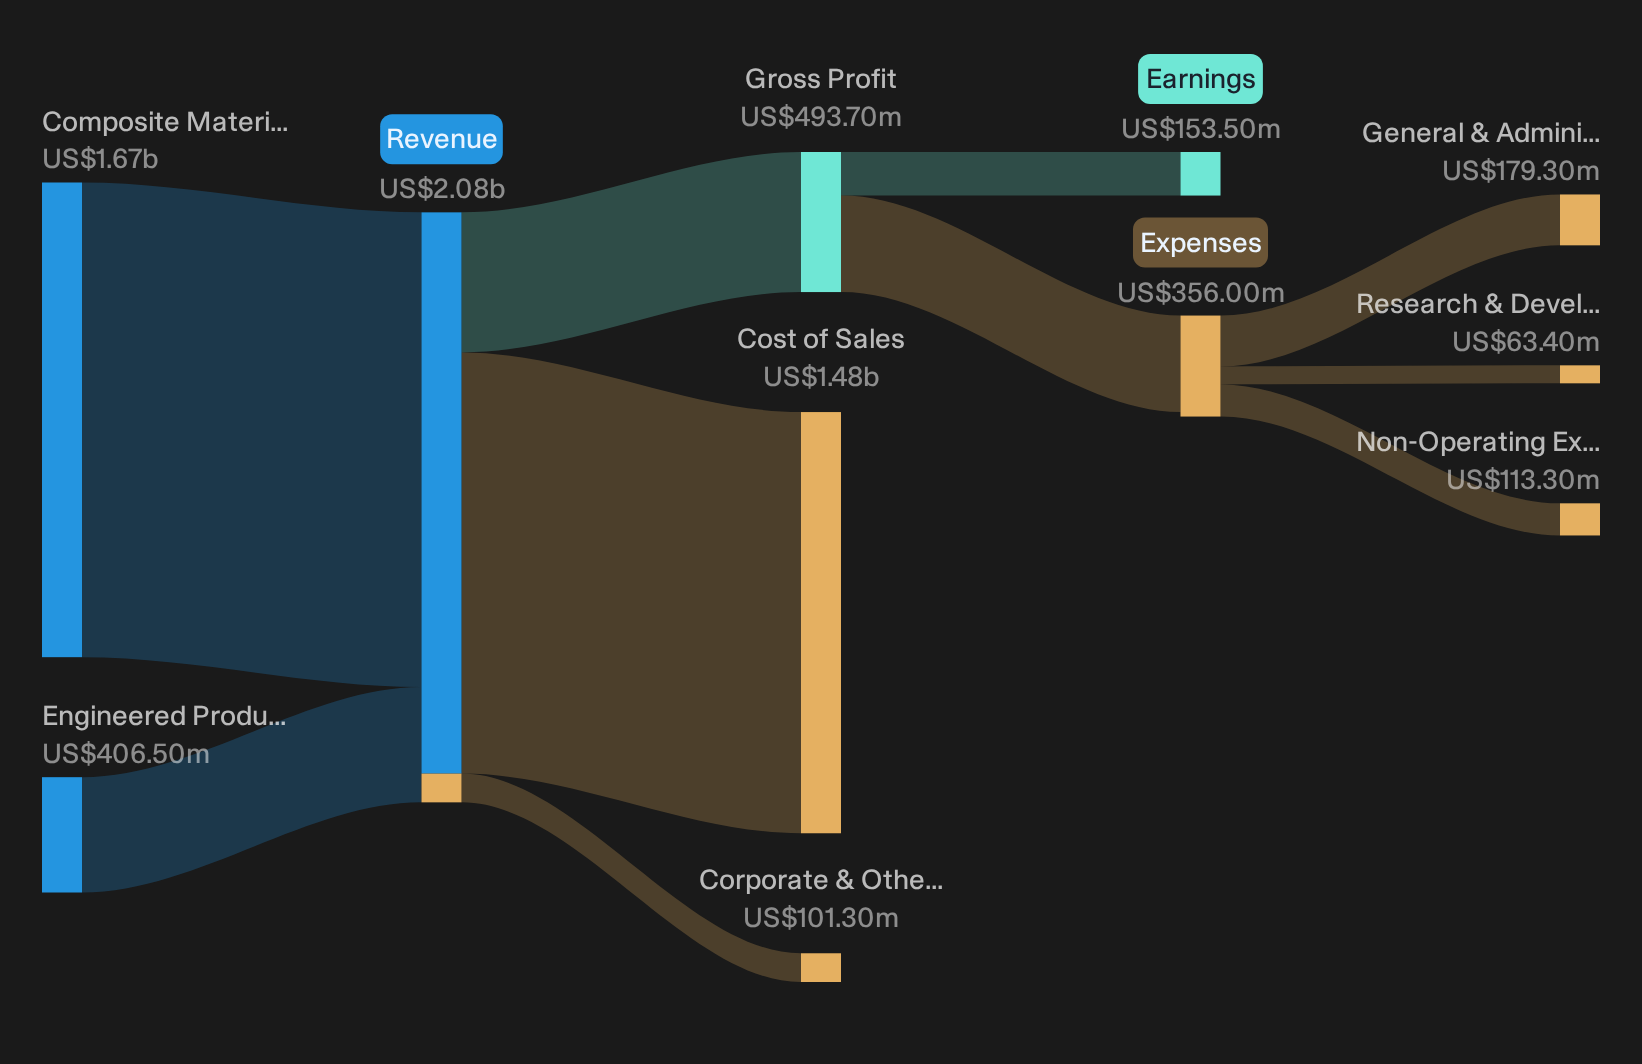
Operations: Hexcel generates about US$1.7b from Composite Materials and US$406 million from Engineered Products, with Corporate & Other reducing reported revenue by US$101 million.
Market Cap: US$6.5b
Hexcel matters for this defense-focused screen because it supplies the lightweight materials that go into many of the platforms benefiting from higher military budgets, which ties its fortunes directly to procurement trends rather than broad market sentiment.
"Rising global defense spending, especially across NATO members and key international markets, is driving orders for a new generation of military aircraft and autonomous systems, platforms with increasing advanced composite content, supporting steady revenue growth and enhanced earnings visibility for Hexcel's defense portfolio."
What really moves the needle next is how one unresolved cost pressure shapes Hexcel's ability to translate that demand into durable margins.
Those margin questions are exactly what the full narrative for Hexcel unpacks, including how cost pressures, contract structures, and defense demand could be quietly reshaping Hexcel's earnings power.
Ducommun (DCO)
Overview: Ducommun provides engineering and manufacturing services for complex electronic systems and aerostructures used in US aerospace, defense, and space platforms.
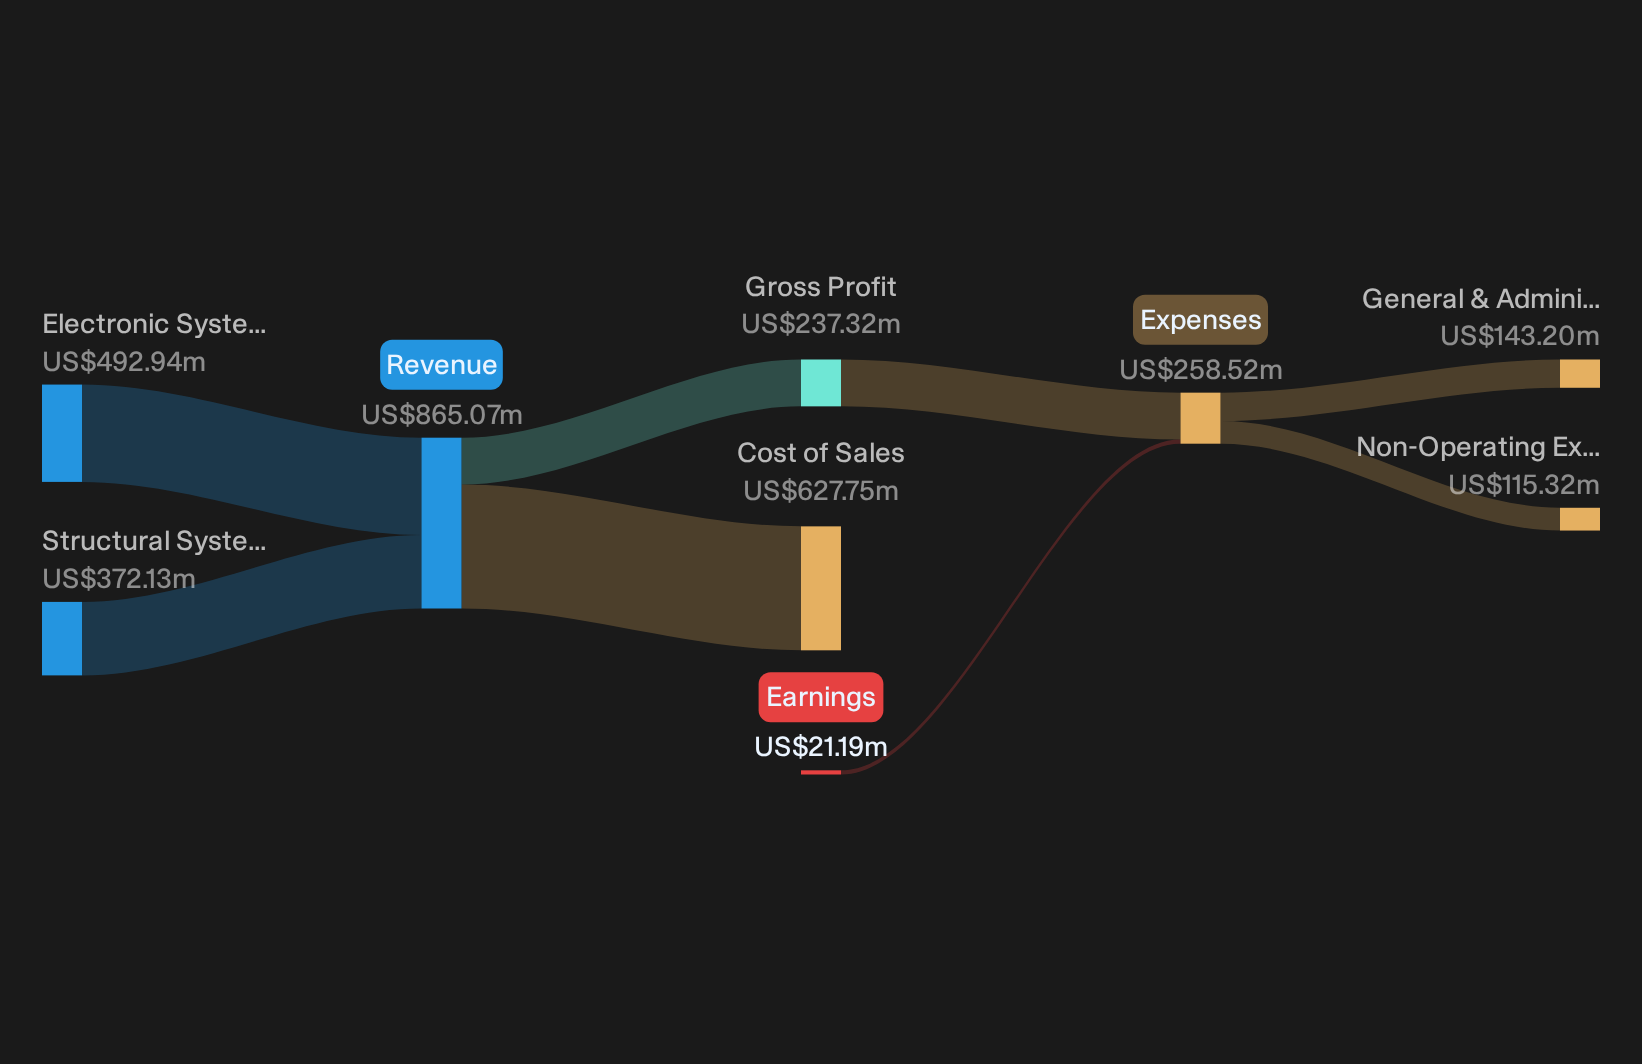
Operations: Ducommun generates about US$492.9 million from Electronic Systems and US$372.1 million from Structural Systems across its aerospace and defense programs.
Market Cap: US$2.6b
Ducommun matters in the US Defense Contractors screen because it sits closer to the hardware of US procurement, supplying mission critical missile, radar, and aircraft content that can run for years once a platform is locked into the Pentagon budget cycle.
"Elevated global defense spending and the replenishment of missile and radar inventories, highlighted by strong double-digit growth in both segments and a 30% increase in missile backlog, positions Ducommun to sustain and expand revenue as defense modernization accelerates over the next several years."
For investors, what happens to Ducommun margins if one cost and mix assumption inside those long-running programs shifts even slightly now becomes crucial.
If that mix shifts faster than expected, the full narrative for Ducommun shows how Ducommun’s backlog, pricing power, and capital choices could be quietly reshaping long term earnings quality.
ESCO Technologies (ESE)
Overview: ESCO Technologies supplies engineered components and systems for aviation, navy, defense, and utilities, tying its business closely to US defense-focused procurement cycles.
Operations: ESCO Technologies generates about US$632.7 million from Aerospace & Defense, US$391.2 million from Utility Solutions Group, and US$266.8 million from Test.
Market Cap: US$6.95b
ESCO Technologies fits this defense-focused screen as a behind-the-scenes supplier. Its hardware and testing gear are embedded across aircraft, submarines, and power infrastructure that governments depend on, which makes the current macro focus on long-term yields and fiscal spending especially relevant.
"Heightened focus on power reliability, grid modernization, and compliance, spurred by stricter regulatory requirements and infrastructure aging, directly boosts demand for ESCO's advanced diagnostic, monitoring, and testing products, enabling margin expansion as utilities prioritize reliability investments and premium solutions."
What really shapes how ESCO Technologies responds to higher long-term rates is how one funding-related pressure interacts with that defense-linked demand.
That funding pressure is exactly what the full narrative for ESCO Technologies unpacks, showing where ESCO Technologies’ defense exposure could be masking accelerating strengths and new rate driven risks.

Seeking Alternatives Before The Crowd Moves
Fresh opportunities do not sit still. Breakout themes gain momentum, quiet winners get caught on screens, and laggards keep dropping while it matters most. Scan these ideas and consider your options.
- Identify dividend engines designed to keep paying as rates and inflation shift by scanning the curated 8 dividend fortresses before everyone starts chasing yield again.
- Follow early movers supplying the picks and shovels for AI infrastructure using the focused 87 AI infrastructure stocks while these enablers remain relatively under the radar.
- Explore potential long-term compounders with resilient finances using the curated list of solid balance sheet and fundamentals (24 results) before new momentum draws broader attention to strong balance sheet stories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com