
3 Japanese Low Risk Stocks With ROE Over 23%
Japanese government bond yields recently reached a 30 year high, reminding investors how quickly borrowing costs can reset and shake confidence. When rates feel unpredictable, companies with strong balance sheets and lower risk profiles can act like the bedrock of a portfolio. This article walks through three low risk Japanese stocks from our quality screener that aim to offer that kind of resilience for long term investors.
The three stocks highlighted next are just a sample from the broader low risk leaders idea, with the full screen surfacing 18 more companies that carry equally detailed stories and balance sheet strength. To go beyond the preview list and immediately filter, analyze, and identify your own highest conviction foundation holdings, head straight into the Low Risk Leaders screener.
ASICS (TSE:7936)
Overview: ASICS is a global sportswear group that designs, makes, and sells running shoes and athletic apparel, anchored by resilient footwear demand.
Operations: ASICS generates revenue across Japan ¥211,067 million, Europe ¥278,636 million, North America ¥161,974 million and Greater China ¥139,530 million, with additional contributions from Oceania and Southeast and South Asia.
Market Cap: ¥2.94t
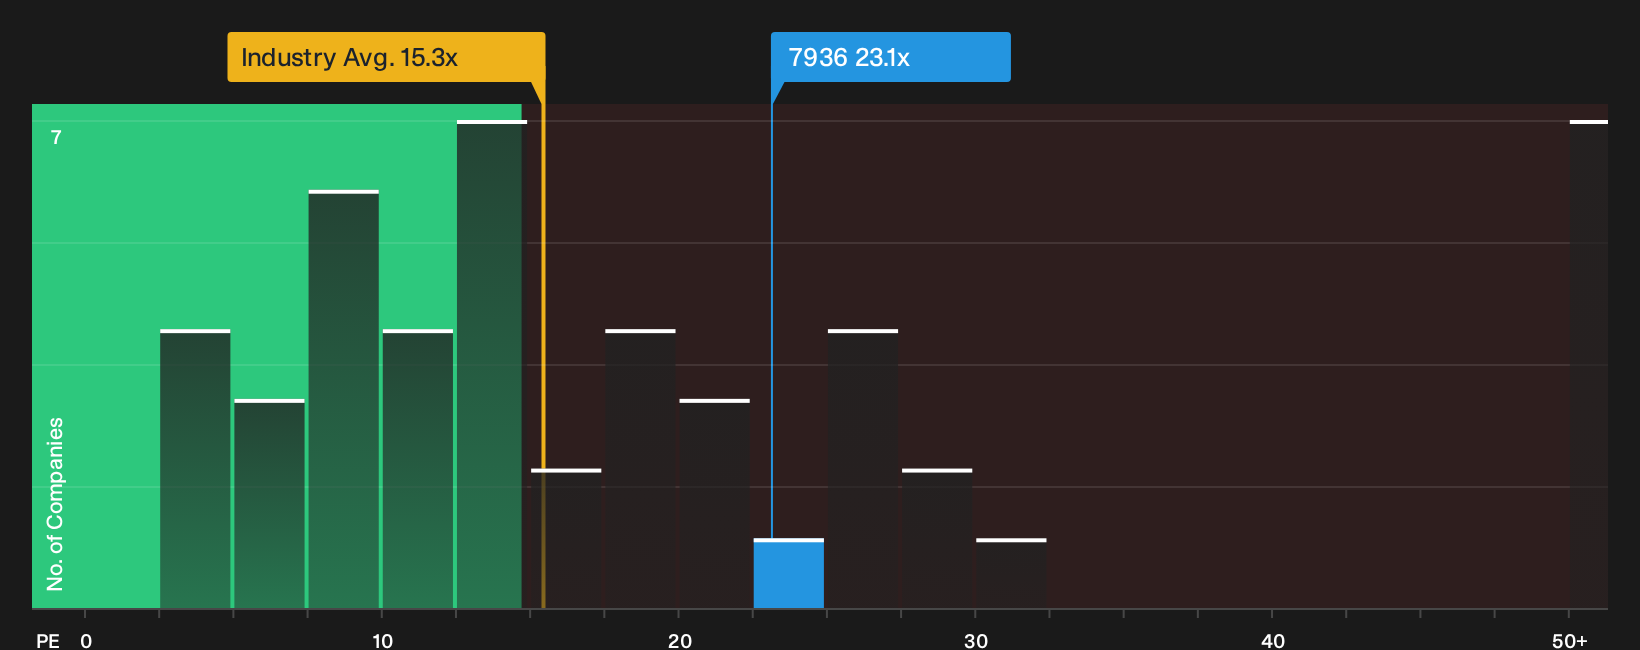
ASICS fits the Low Risk Leaders idea through a core running shoe and apparel franchise that supports a strong balance sheet and high profitability, including recent net margins around 13.5% and a P/E of 23.1x that sits close to estimated fair value. For investors seeking a portfolio anchor, the central consideration is what happens if a single key assumption about that brand driven demand curve breaks.
If that demand curve ever bends, the 4 key rewards and 1 important warning sign shows what could be masking under today’s margins and valuation.
Chugai Pharmaceutical (TSE:4519)
Overview: Chugai Pharmaceutical develops and sells oncology and immunology biologic therapies worldwide, providing recurring cash flows that support its low risk profile.
Operations: Chugai Pharmaceutical generates approximately ¥1.34t in pharmaceuticals revenue, with ¥486,188m reported in Japan and the remainder captured in segment adjustments.
Market Cap: ¥10.89t
For a Low Risk Leaders portfolio, Chugai Pharmaceutical brings something different to the table, with oncology and immunology treatments that behave more like essential infrastructure rather than one off product cycles. This positioning aligns with the screener's focus on dependable cash engines.
"The company's strategic focus on innovative biologics and personalized medicine, including advancements in mid-sized molecules (AUBE00) and a deep monoclonal antibody pipeline, is well aligned with increasing healthcare spending and the push for novel, high-value therapies, likely supporting future earnings expansion."
The real test for Chugai Pharmaceutical is how any future pressure on its flagship franchises affects margins and cash generation.
When that pressure hits, the full narrative for Chugai Pharmaceutical steps through how Chugai Pharmaceutical’s pipeline, partnerships and cash engine could either accelerate or stall from here.

Recruit Holdings (TSE:6098)
Overview: Recruit Holdings is a global HR and marketing services group whose HR Technology platforms connect employers and job seekers through recurring, low-friction recruitment tools.
Operations: Recruit Holdings generates ¥1.75t from Staffing, ¥1.57t from HR Technology, and ¥569.7b from Marketing Matching Technologies, with a small unallocated adjustment.
Market Cap: ¥22.74t
Recruit Holdings matters for the Low Risk Leaders theme because its recruitment platforms behave like subscription utilities for hiring teams. This can turn steady hiring activity into recurring, platform-based cash flows that may help support a sturdy financial profile, while other business lines add extra diversification.
"Recruit Holdings' unique access to large volumes of proprietary matching and conversational data, combined with advanced vertical AI development for specialized HR processes, positions the company to create best-in-class, defensible user experiences that will attract and lock in both employers and job seekers globally, supporting multi-year engagement growth and significant revenue upside."
The real fork in the road for Recruit Holdings is what happens to that steady foundation if a single assumption about those recruitment budgets shifts.
If that hiring spend ever starts to decouple from expectations, the full narrative for Recruit Holdings reveals how Recruit Holdings’ data advantage could still accelerate value for long term holders.

Seeking Fresh Alternatives Beyond These Three
Markets move fast and the next breakout group can start flying while most investors are still watching yesterday’s leaders. Scan fresh ideas before the crowd and act now.
- Target reliable cash generators with resilient balance sheets by running the list of solid balance sheet and fundamentals (22 results). This allows you to focus on businesses built to handle tougher conditions.
- Explore early momentum in specialized AI platforms through the 87 AI infrastructure stocks before attention fully shifts and valuations reflect that changing demand.
- Monitor future materials demand by tracking the 35 best rare earth metal stocks to identify producers that may benefit if supply remains tight while interest continues to build.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com