
10x Genomics (TXG) Stock Could Look Pricey Against Its Current Sales Base
10x Genomics has seen its share price move sharply over the past year, which naturally puts the focus on whether that move is supported by its sales. With the stock now closing at US$85.71, the key issue is how much revenue investors are effectively paying for at today's level.
- Over the past 12 months, 10x Genomics has delivered a share price return of about 6x, so anyone looking at the stock now is meeting a very different valuation backdrop than a year ago.
- The business model leans heavily on selling instruments and consumables tied to its single cell and spatial biology platforms. This can support recurring sales but also ties valuation closely to how effectively those systems translate into ongoing revenue per installed unit.
- The analysts covering 10x Genomics have run their own numbers. See what analysts think 10x Genomics's shares could be worth.
The stock's next move may depend on whether the current share price can be squared with the sales base that 10x Genomics is generating today.
If you want more ideas built around revenue driven stories like 10x Genomics, a focused stock screen can be a smart next step. You can start with 31 high quality undervalued stocks.
Does 10x Genomics Look Pricey on Sales?
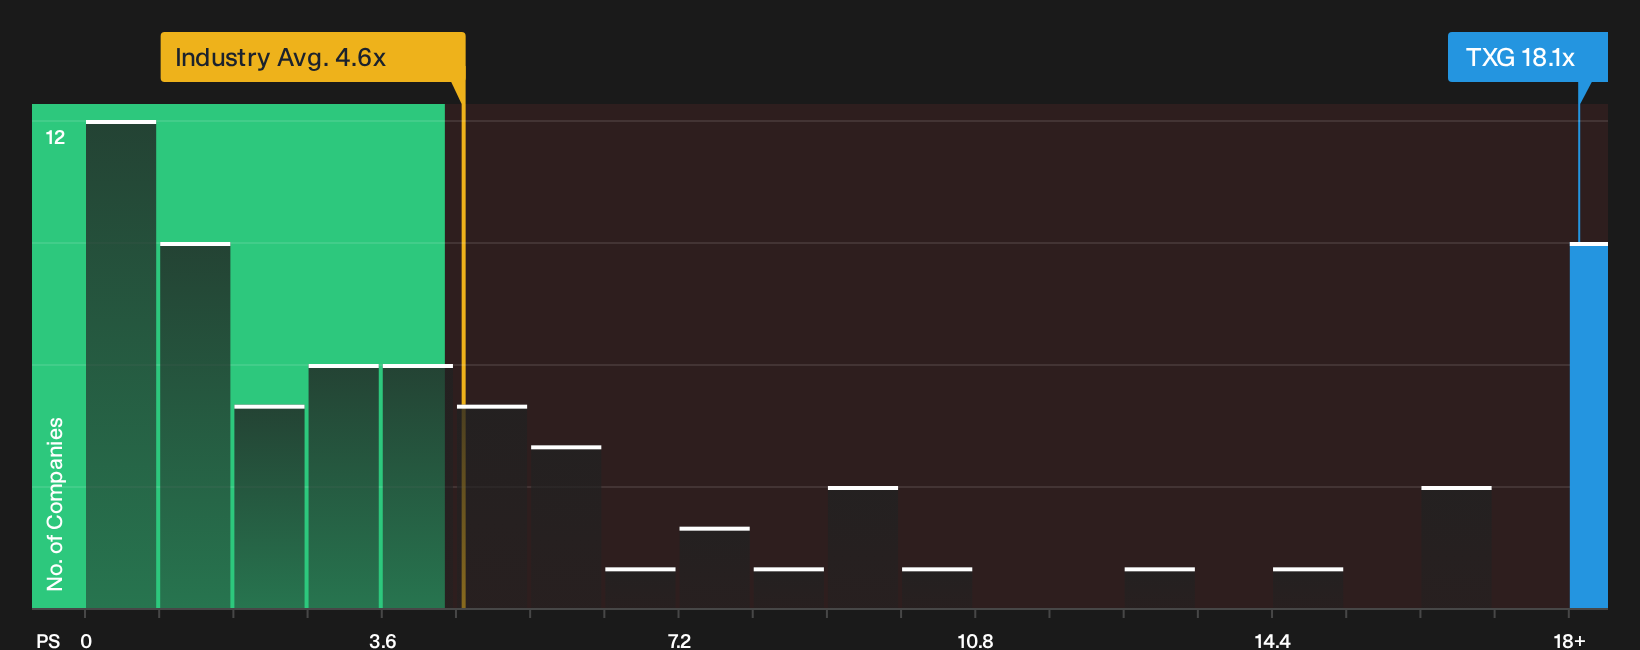
P/S is a useful lens for 10x Genomics because the company’s valuation is still more anchored to revenue than to earnings. On this measure, the stock trades on a P/S of about 18.1x, which is far above the Life Sciences industry average of roughly 4.6x and also well ahead of the peer group around 7.8x. That is a significant premium for each dollar of current sales.
The fair multiple implied by the valuation model, which blends the company’s growth profile, margins, size and risk, sits meaningfully below where the P/S ratio is today. This gap indicates that 10x Genomics screens as overvalued on sales, so anyone buying at this level is paying a high price for the existing revenue base and whatever progress they expect from here. Explore the numbers behind 10x Genomics's P/S valuation.
The 10x Genomics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for 10x Genomics pick up where this pricing puzzle leaves off and spell out what growth, margin and earnings paths would need to play out for the stock to be worth meaningfully more or less than it is today, based on today’s revenue base and business model. Rather than a single multiple or model output, each Narrative lays out the key inputs behind its view of fair value so you can compare those assumptions with actual results over time.
One of the top community narratives on 10x Genomics: 114% overvalued
"The rapid commoditization and competitive encroachment in the single-cell and spatial genomics space, coupled with falling instrument average selling prices..."
Discover why this Narrative puts 10x Genomics at 114% overvalued.
One more 10x Genomics check before you stop at the share price
All the ratios in the world matter less if the people steering 10x Genomics and the way they are rewarded pull the business in a different direction than shareholders expect. See who runs 10x Genomics and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com