
Fox (FOXA) Stock Looks Reasonable Based On Future Cash Flow
Fox has delivered a powerful run over the past few years, which now puts the spotlight squarely on whether the current share price lines up with the cash the business is expected to generate. With the stock pulling back in recent weeks, the key issue is how that recent move sits against what its cash flows may be worth on a Discounted Cash Flow (DCF) basis.
- Over the last 3 years Fox has returned 109.2%, which puts real weight on the question of whether that performance matches the value implied by its future cash flows.
- The company relies heavily on converting its media operations into steady free cash flow, so any change in content spending, advertising trends or affiliate fees can affect both the level and timing of the cash that anchors a DCF style intrinsic value.
- What if you looked at Fox through its earnings instead? See why Fox's 15.8x P/E tells a different valuation story.
For investors, the debate is whether Fox's current share price, after a recent pullback, is adequately explained by the cash flows implied by a Discounted Cash Flow (DCF) estimate.
If you are evaluating Fox with a DCF approach, it may be useful to compare it with other companies that are screened for 31 high quality undervalued stocks.
Does Fox Look Fairly Valued on Cash Flow?
The Discounted Cash Flow (DCF) model here is built around Fox turning its media footprint into recurring free cash generation. Over the last twelve months the group produced roughly $1.54b in free cash flow, and the forecast path assumes this moves into the low $2b range in the next stage of the model while then easing back, which points to a business expected to grow its cash flows before settling into a slower phase.
Those cash projections are spread across a 2 Stage Free Cash Flow to Equity framework. The near term years carry more detailed analyst inputs, and the later period leans on more modest estimates. When the discounted cash flows are lined up against today’s share price of $63.06, the DCF projections put Fox's estimated intrinsic value broadly in line with the current share price. Find out what Fox could be worth using our Discounted Cash Flow (DCF) estimate.
The Fox Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the DCF puzzle leaves off by spelling out what combination of future growth, margins and earnings would need to hold for Fox's valuation to shift meaningfully higher or lower than today's share price. Each scenario ties a fair value to a specific view of Fox's potential catalysts and risks so you can track over time which version of the story is actually unfolding.
Community views on Fox are split between those who think connected TV can reshape the business and those who worry that streaming and sports costs will bite harder.
Bull case: 17% undervalued
"The planned Roku acquisition, with guided run rate cost synergies of about US$400 million, anticipated free cash flow per share accretion within two years of closing..."
Discover why this Narrative puts Fox at 17% undervalued.
Bear case: 20% overvalued
"As viewing continues to migrate from traditional pay TV to streaming, FOX One’s stated ambition for only low to mid single digit millions of subscribers risks being insufficient..."
Explore why this Narrative puts Fox at 20% overvalued.
One more Fox question that could matter more than the model
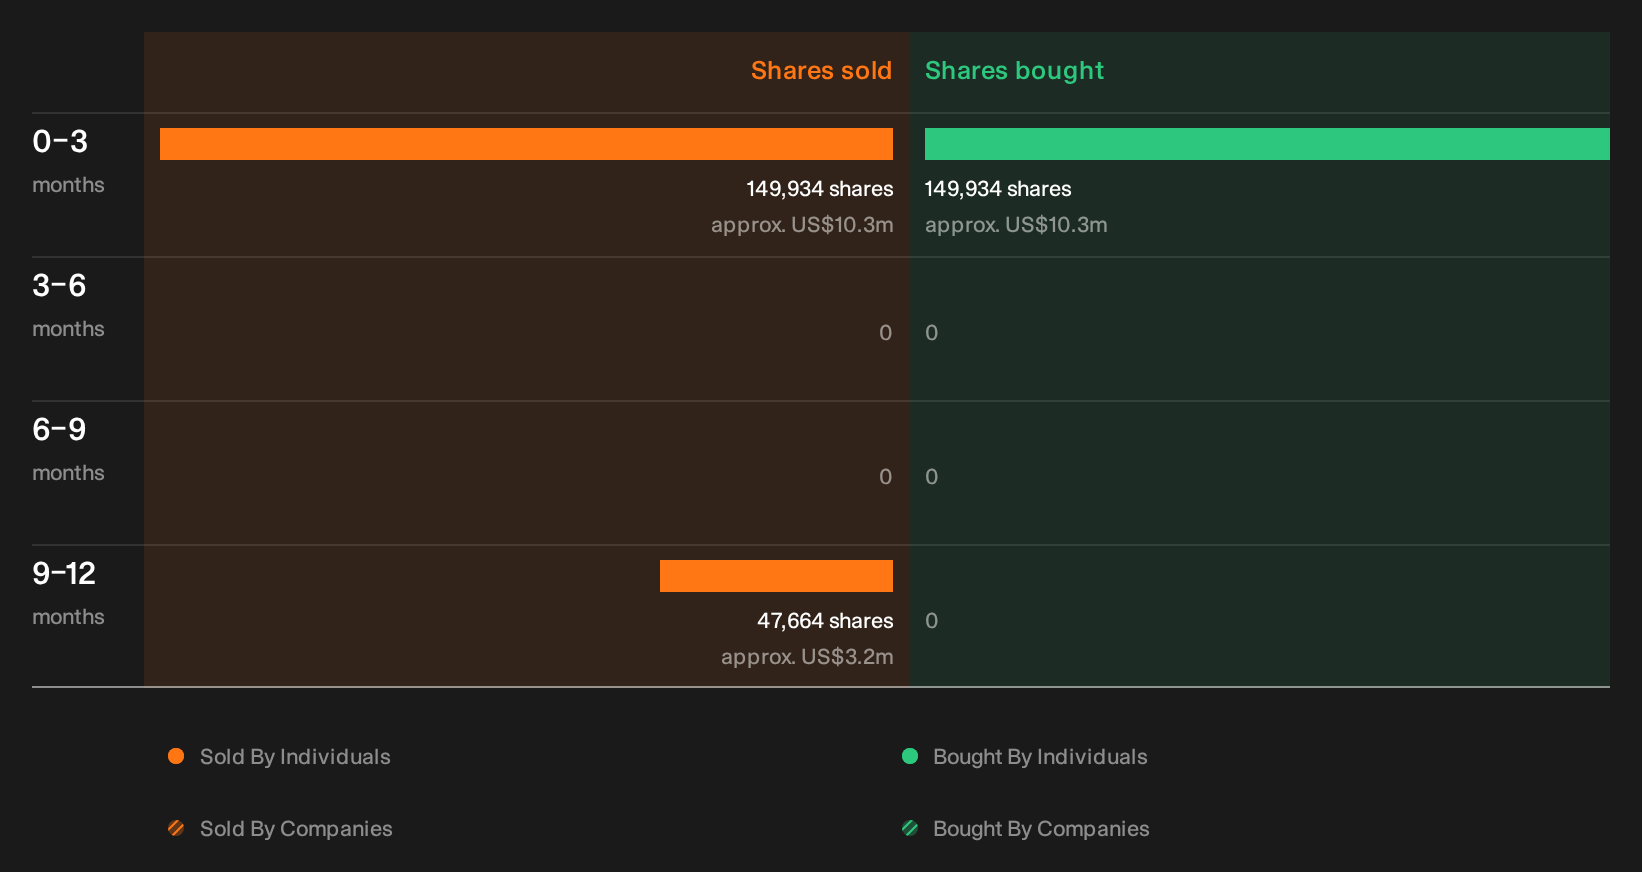
Valuation only tells part of the story, and recent trading activity by Fox insiders is the kind of clue that can reshape how you read everything else. See the recent insider selling flagged for Fox.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com