
Is Stewart Information Services (STC) Undervalued As Housing Recovery Hopes Face A Share Price Slide?
Stewart Information Services (STC) has drawn investor attention after a stretch of weaker share performance, with the stock down over the past month and past 3 months despite positive annual revenue and net income growth.
The recent pressure on Stewart Information Services' share price, including a 1-day share price return of down 0.9% and a 7-day share price return of down 6.3%, comes on top of a year to date share price return of down 15.4%. However, the 3-year total shareholder return of 48.1% still paints a much stronger long run picture.
Compare Stewart Information Services' recent pullback with other insurers by scanning our hand picked list of solid balance sheet and fundamentals (24 results) for potential alternatives in the same space.
Stewart Information Services has been growing its business, yet the share price has retreated sharply in recent months. Is this a solid franchise temporarily marked down, or a fair reflection of what investors are willing to pay today?
Most Popular Narrative: 29% Undervalued
Analysts tracking Stewart Information Services currently anchor on a fair value of $83 per share, which sits well above the recent close around $59, and they tie that gap to a specific set of housing and commercial real estate assumptions.
Stewart Information Services expects improvement in the housing market in the second half of 2025, driven by educated consumers poised to act on changes such as a drop in interest rates, potentially boosting revenue and earnings.
The company is experiencing significant growth in its Title segment, specifically in commercial services and asset classes like retail and energy, which could positively impact revenue and pretax income.
See why 2 investors see Stewart Information Services as 29% undervalued.
Result: Fair Value of $83 (UNDERVALUED)
Still, the Stewart Information Services story could be knocked off course if housing activity stays muted for longer or if elevated data and employee costs continue to squeeze margins.
Find out about the key risks to this Stewart Information Services narrative.
Another View On Stewart Information Services Valuation
Analysts see Stewart Information Services as undervalued based on a future earnings narrative and a fair value of $83. A different lens tells a cooler story. The SWS DCF model estimates the value of future cash flows at $35.58 per share, which is well below the recent price near $59.19. That points to an overvalued signal on this framework and raises a simple question: Which set of assumptions about Stewart Information Services' future cash generation do you trust more?
Look into how the SWS DCF model arrives at its fair value.
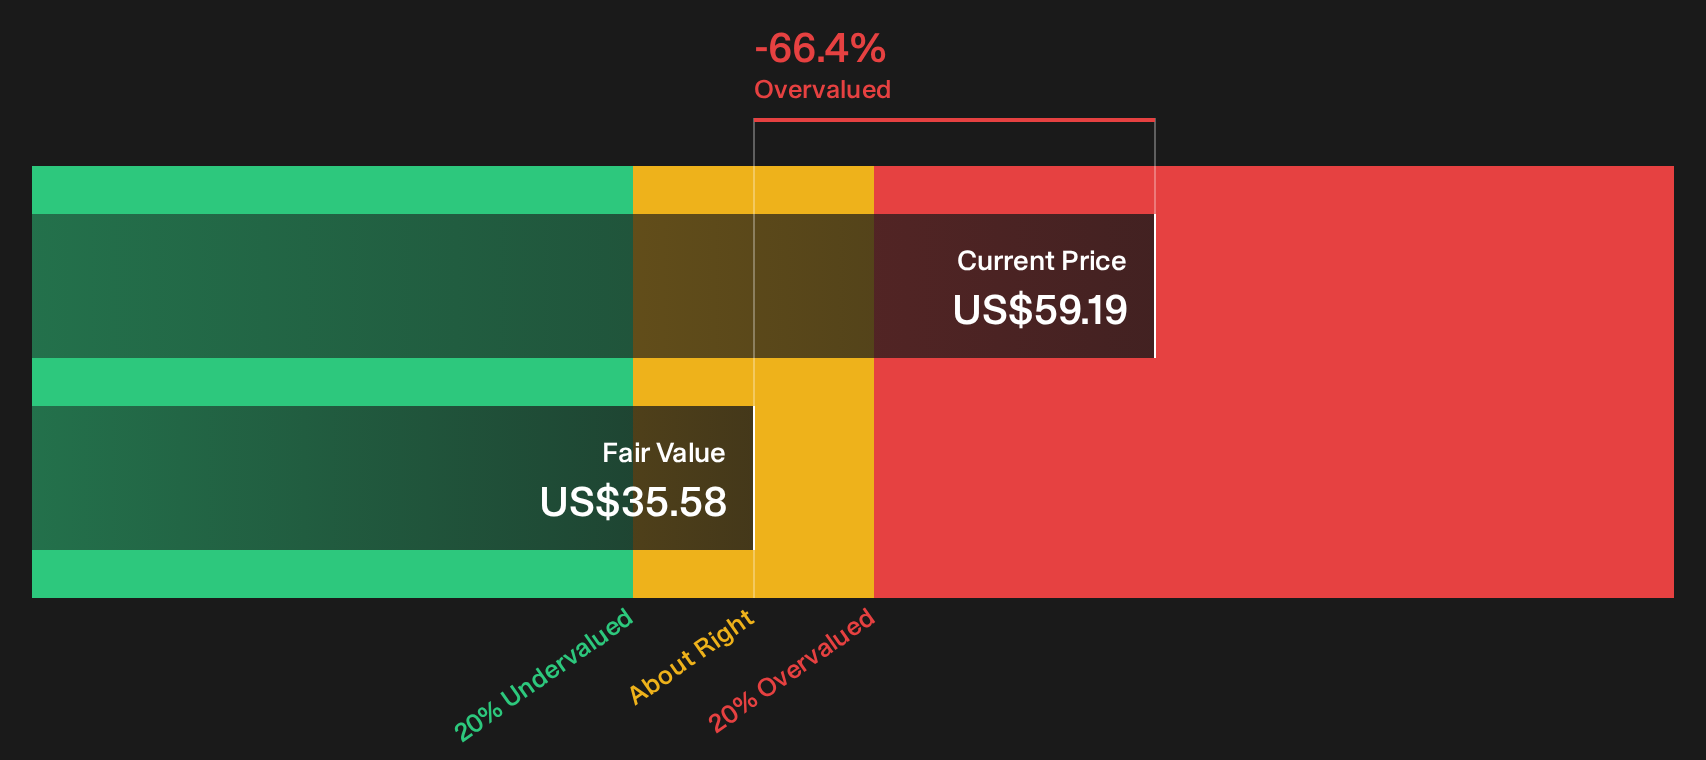
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Stewart Information Services for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Stewart Information Services is mixed, and that is exactly when data matters most. Act quickly on your curiosity and explore the bullish angles for yourself by checking the 5 key rewards.
Looking for more investment ideas beyond Stewart Information Services?
Do not stop with Stewart Information Services. Broaden your watchlist now and give yourself more ways to respond when the next opportunity appears.
- Target dependable cash generators by reviewing the 8 dividend fortresses, which aim to keep income flowing while you focus on long term compounding.
- Hunt for potential mispricings by scanning the 16 high quality undiscovered gems, which many investors may not be watching yet.
- Prioritize capital preservation by running through the 29 resilient stocks with low risk scores so you do not overlook resilient businesses when conditions turn tougher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com