
Delek US Holdings (DK) Stock Looks Overvalued As Earnings Face A Higher Bar
Delek US Holdings has delivered eye catching long term gains, which puts a spotlight on whether the current share price is adequately backed by its earnings power. After that kind of run, the key issue for any holder is what the recent valuation now implies for future profit delivery.
- Over the past 5 years the stock has returned 348.1%, which makes it important to ask how much of that move can be explained by the underlying earnings profile rather than just a reset in market optimism.
- The business model is tightly linked to refining and related energy operations, so profitability, margins and reinvestment needs can heavily influence how much of each dollar of accounting earnings is realistically available to shareholders over time.
- The analysts covering Delek US Holdings have run their own numbers. See what analysts think Delek US Holdings's shares could be worth.
The issue now is whether Delek US Holdings' recent share price level is justified by the earnings that investors can reasonably link to each share.
If you want to stress test whether Delek US Holdings' earnings-based valuation stacks up against other opportunities, compare it with 31 high quality undervalued stocks
Has Delek US Holdings Run Too Far on Earnings?
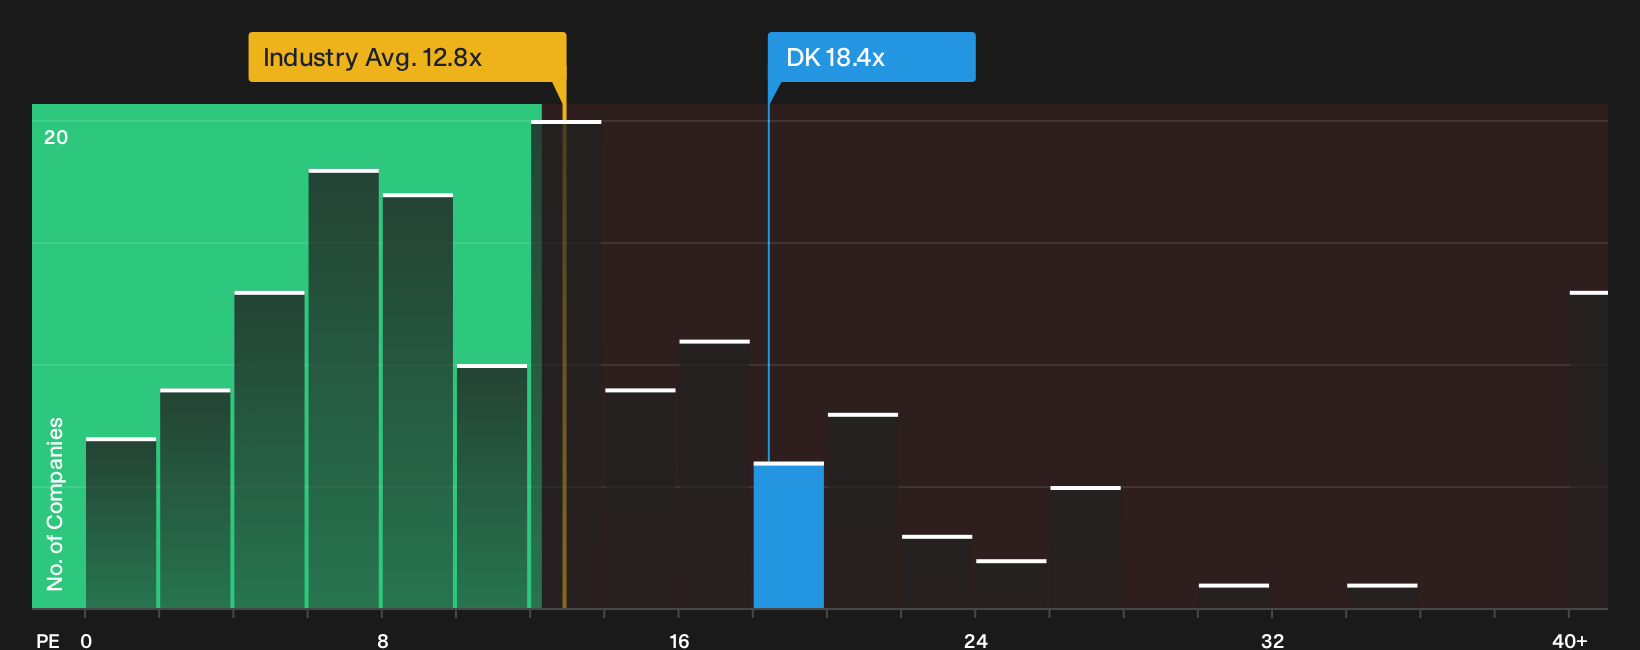
P/E works well for Delek US Holdings because earnings are a key lens for investors trying to judge what they are paying for each dollar of profit. The stock trades on a P/E of roughly 18.4x, which is higher than the Oil and Gas industry average of about 12.8x but below the peer group at roughly 24.5x. That mix suggests the market is pricing Delek US ahead of the broader sector yet not at the top tier of its direct comparables.
The fair multiple implied by a more tailored model, which factors in the company’s own growth profile, profitability and risk, sits below the current 18.4x level. That gap points to Delek US Holdings screening as overvalued on this P/E framework, with investors paying a premium relative to what its earnings characteristics would typically support. The key question for you is whether the business can justify that richer tag over time through the cash flows and returns you expect to see. Explore the numbers behind Delek US Holdings's P/E valuation.
The Delek US Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Delek US Holdings' P/E leaves off, by spelling out which paths for future growth, margins and earnings would need to play out for the stock to be worth materially more or less than today’s share price. Each Narrative sets out Delek US Holdings' implied fair value as a thesis about the business that you can track over time, rather than treating it as a one off snapshot. They are available on Simply Wall St's Community page.
Community views on Delek US Holdings split sharply, with one camp seeing meaningful upside and the other flagging material downside risk.
Bull case: 18% undervalued
"Analyst consensus believes the Enterprise Optimization Plan can deliver $130 million to $170 million in annualized free cash flow improvements, but disciplined execution and a culture shift toward continuous operational efficiencies position Delek to consistently surpass even the top end of these expectations..."
Discover why this Narrative puts Delek US Holdings at 18% undervalued.
Bear case: 82% overvalued
"The accelerating adoption of electric vehicles and increasingly stringent fuel efficiency standards are set to directly erode gasoline and diesel demand in Delek's core Sun Belt and Midcontinent markets, threatening to drive long-term declines in fuel sales volumes and compressing top-line revenue for the company..."
Explore why this Narrative puts Delek US Holdings at 82% overvalued.
For Delek US Holdings, price alone does not tell the full story
Valuation only shows what you are paying for Delek US Holdings today, while a separate set of checks has highlighted potential concerns that careful investors often weigh just as closely. Take a closer look at 4 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com