
Is Dentsu Group (TSE:4324) Fully Valued After Its Kodansha Anime Marketing Deal?
Leadership change and anime deal put Dentsu Group in focus
Dentsu Group (TSE:4324) has moved into the spotlight after securing a marketing partnership with Kodansha Ltd. that centers on major anime franchises and broad brand tie ins across the Americas.
Recent trading suggests interest around Dentsu Group is picking up. The share price is ¥3,585 with a 90-day share price return of 17.43%. The 1-year total shareholder return of 8.67% contrasts with a 3-year total shareholder return that declined 14.16%, hinting at improving momentum after a tougher spell.
Scan how Dentsu Group’s anime push compares with other media players by jumping into a curated list of 74 high quality undiscovered gems that may still be flying under most investors’ radar.
Dentsu Group now trades only slightly below the average analyst target, yet its implied intrinsic value suggests a much wider gap. Is this recent anime fuelled rerating already fair, or still conservative?
Most Popular Narrative: 4% Overvalued
Dentsu Group last closed at ¥3,585, while the most followed valuation storyline points to a fair value of ¥3,442. This implies a small premium and places more emphasis on the company’s execution than on a large pricing gap.
The analysts have a consensus price target of ¥3,442.22 for Dentsu Group based on their expectations of its future earnings growth, profit margins and other risk factors. However, there is a degree of disagreement amongst analysts, with the more bullish reporting a price target of ¥4,000.0, and the most bearish reporting a price target of ¥2,500.0.
See why 1 investors see Dentsu Group as 4% overvalued.
Result: Fair Value of ¥3,442 (OVERVALUED)
Still, investor confidence in Dentsu Group could be tested if international units keep underperforming or if further goodwill write downs reduce already weak net income.
Find out about the key risks to this Dentsu Group narrative.
Another View on Dentsu Group’s Value
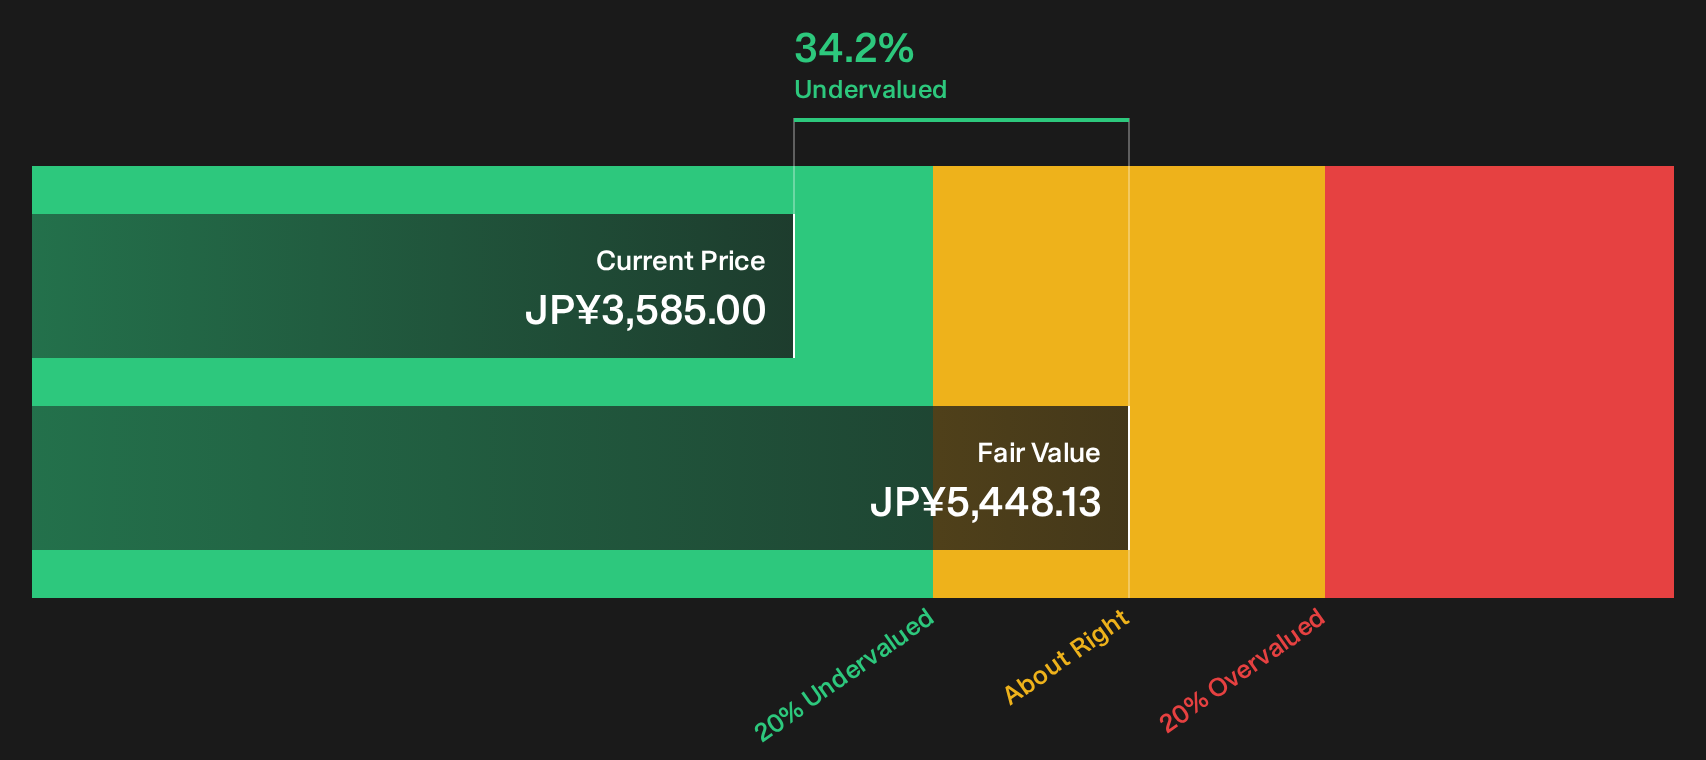
The first storyline presents Dentsu Group as roughly 4% overvalued around ¥3,585 compared with a fair value near ¥3,442. A different perspective using our DCF model suggests the opposite. On that approach, the shares trade about 34% below an estimated future cash flow value of ¥5,448.13.
These two methods send very different signals, so which one better matches your own expectations for cash generation and risk over the next few years?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Dentsu Group is split, which is exactly why your own read of the data matters. If you want to pressure test the optimism and see what has investors excited, take a closer look at the 3 key rewards.
Looking for more investment ideas beyond Dentsu Group?
Do not stop your research with Dentsu Group when a broader watchlist could reveal stronger balance sheets, cheaper valuations, or underfollowed opportunities that better fit your goals.
- Target financial resilience by scanning a list of solid balance sheet and fundamentals (22 results) that can help you focus on companies with room to handle shocks and reinvest with less balance sheet strain.
- Hunt for value by reviewing a 18 high quality undervalued stocks that highlights businesses trading at lower prices relative to their fundamentals, so you are not overpaying from the start.
- Prioritize sleep-at-night holdings by filtering a 21 resilient stocks with low risk scores aimed at resilient operations with lower risk scores, so volatility does not dominate your portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com