
How Investors Are Reacting To Casio (TSE:6952) Limited Edition MR G Launch
- Casio Computer Co. Ltd. released the limited edition MRG-B2100HR G-SHOCK MR-G watch, capped at 800 pieces. The model features a kigumi-inspired lattice dial, a platinum leaf finish, and premium alloys such as COBARION and DAT55G to mark 30 years of the MR-G line.
- The collaboration with metal leaf artist Hiroto Rakusho and the use of structural color technology highlight Casio Computer’s push deeper into high-end, design-led timepieces that emphasize craftsmanship as well as durability.
- The launch of Casio Computer’s premium, ultra-limited MR-G model may be relevant for understanding its broader investment narrative around higher-margin watches.
Scan beyond Casio ComputerLtd and see how other premium watchmakers and niche consumer brands are positioning for pricing power with our hand-picked 74 high quality undiscovered gems.
Casio ComputerLtd Investment Narrative Recap
To own Casio ComputerLtd, you need to believe the timepiece arm can keep pulling more weight, especially through premium lines, while the wider portfolio in calculators, education tech and systems supports steadier earnings. The new limited MRG-B2100HR sits in that premium story, but with only 800 units it barely moves group-level revenue or profit.
The more immediate swing factors remain demand in key regions, tariff exposure on U.S. shipments sourced from China, and whether margin pressure seen in prior periods stabilises. The big operational risk is that uneven performance in China and Europe and price competition in electronics keep earnings volatility elevated.
The MRG-B2100HR launch matters most when set against Casio ComputerLtd’s broader push toward higher margin watches and away from purely volume-driven categories. Management has been leaning into premium SKUs and targeted marketing in markets like India and ASEAN, aiming for better mix rather than chasing low priced competitors.
That tilt intersects directly with existing catalysts and risks. Premium MR-G pieces can help offset weaker demand in traditional segments and support profit quality, while the firm still has to manage tariff costs, slow patches in China and Europe, and a P/E that screens higher than the JP Consumer Durables average if execution on this repositioning underwhelms.
Casio Computer Ltd's narrative projects ¥335.2b revenue and ¥32.7b earnings by 2029, based on analyst estimates. This is based on an assumption of 5.1% yearly revenue growth and an earnings increase of about ¥8.8b from ¥23.9b today.
Uncover why Casio ComputerLtd's fair value is essentially in line with its current price.
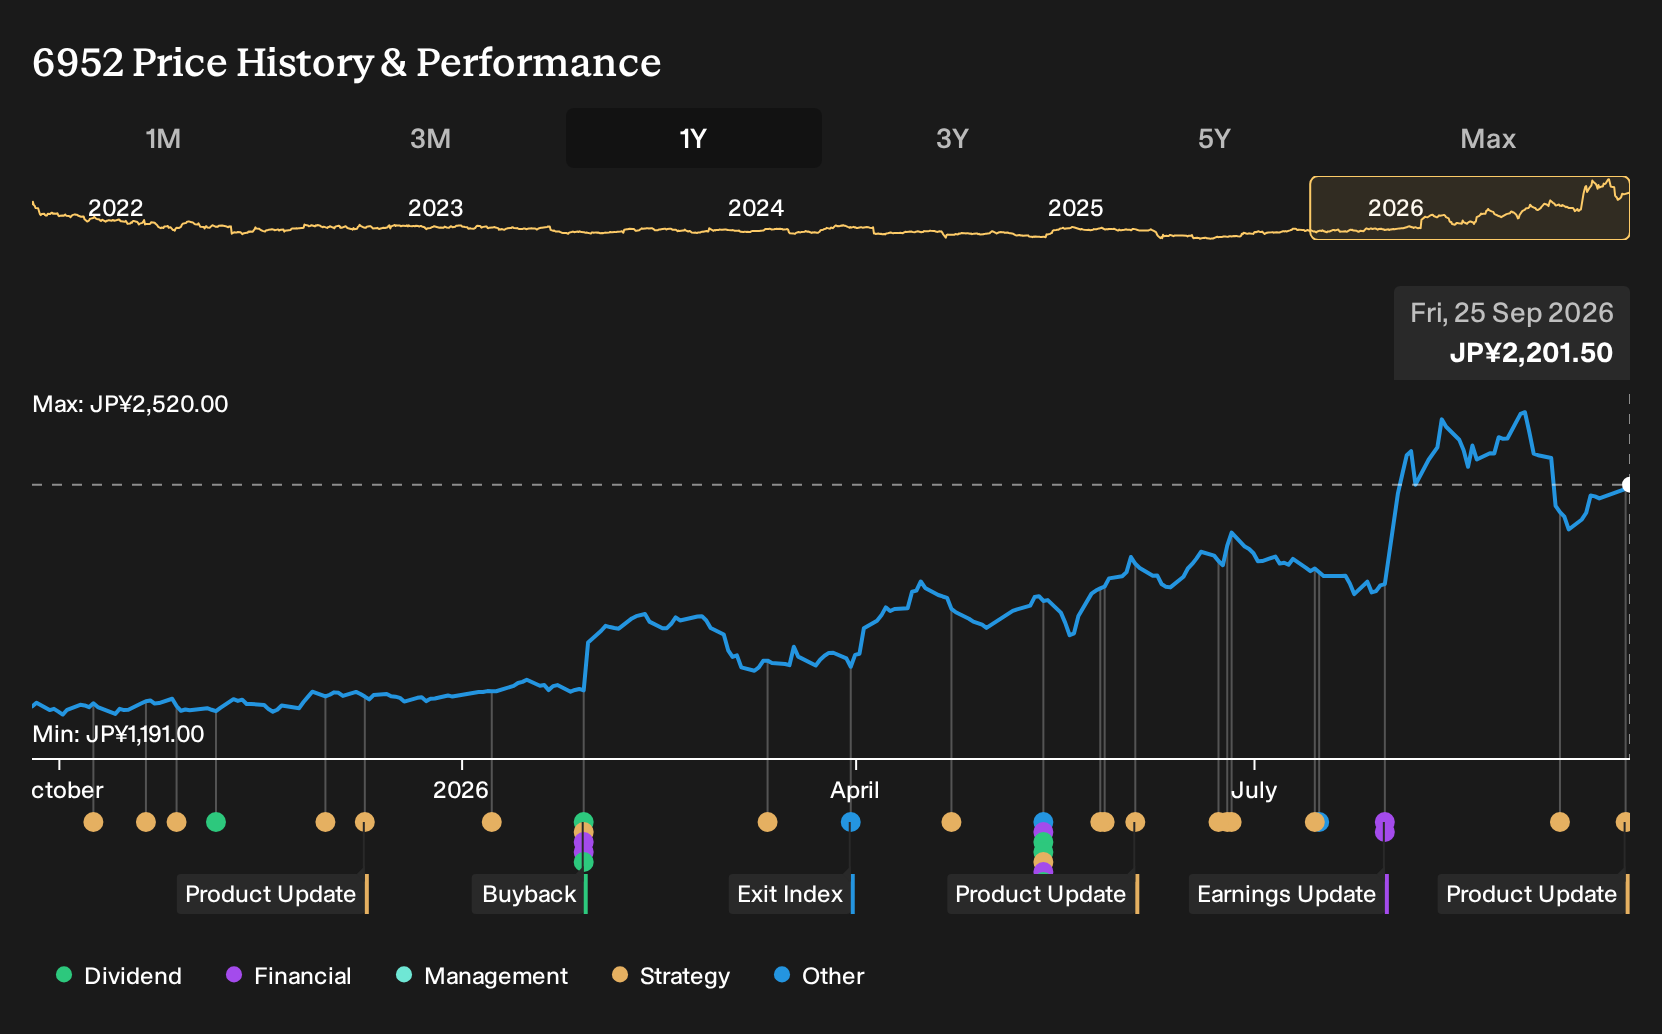
Exploring Other Perspectives
For Casio Computer Ltd, the most optimistic analysts focus on a catalyst that barely appears in the baseline narrative. They lean on faster e-commerce and direct to consumer rollout, and had already pencilled in revenue of ¥352.4b and earnings of ¥34.4b by 2029. The new MR-G release could nudge those expectations again, in either direction, so it is worth comparing several viewpoints before you decide what feels reasonable.
Explore another Casio ComputerLtd fair value estimate, including one that suggests as much as 26% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Casio ComputerLtd research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Casio ComputerLtd. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Casio ComputerLtd's overall financial health at a glance.
Looking For More Ideas Beyond Casio ComputerLtd?
If the Casio ComputerLtd story has you thinking about portfolio upgrades, it can help to compare it with other companies that share similar strengths like pricing power, balance sheet resilience, or income potential. The Simply Wall St Screener lets you jump straight to shortlists that match those themes, so you spend less time trawling and more time weighing real options.
- If you want potential value with quality fundamentals, scan a curated set of 18 high quality undervalued stocks that combine strong business profiles with prices that may not fully reflect them yet.
- For investors who care most about resilience, narrow your search to a 21 resilient stocks with low risk scores that targets companies with lower risk scores and steadier financial profiles.
- If balance sheet strength is non negotiable for you, start with a list of solid balance sheet and fundamentals (22 results) that filters for robust finances and healthier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com