
Is RLI (RLI) Undervalued After Its Pullback And Catastrophe Risk Concerns?
RLI (RLI) is back in focus after fresh commentary on specialty insurers highlighted the role of players like RLI, Kinsale, Palomar and Skyward Specialty in covering complex risks that traditional carriers often avoid.
Recent trading tells a mixed story for RLI. The share price is down 14.1% over the past month and 10.9% year to date, while the 5 year total shareholder return of 37.8% still points to a materially stronger long run record. This suggests enthusiasm has cooled in the short term as investors reassess growth potential and risk in specialty insurance after a strong multi year run.
Compare RLI with a curated group of specialty and niche insurers by scanning the 30 resilient stocks with low risk scores that have held up better on quality and balance sheet resilience.
RLI now trades modestly below both analyst targets and some fair value estimates after that sharp pullback. Is the market correctly pricing in slower momentum, or is caution starting to look excessive as the valuation resets?
Most Popular Narrative: 8% Undervalued
RLI last closed at $55.69, while the most followed narrative pegs fair value at $60.75 using a 7.1% discount rate. This frames the recent pullback as a potential mispricing rather than just sentiment fatigue.
The softening of the commercial property insurance market, driven by increased competition from MGAs and admitted carriers as well as significant new entrants, is expected to suppress top-line premium growth and potentially erode underwriting margins if RLI is unable to maintain current pricing discipline, ultimately pressuring revenue and net margins.
Elevated frequency and severity of natural catastrophe events, combined with increasing catastrophe-related claims and ongoing exposure to hurricane and earthquake risk, may require RLI to set aside higher capital reserves and could lead to greater earnings volatility and reduced net profitability in the longer term.
See why 3 investors see RLI as 8% undervalued.
Result: Fair Value of $60.75 (UNDERVALUED)
Still, this narrative can unravel quickly if catastrophe losses swing higher or if technology and acquisition spending keep expense ratios elevated and squeeze RLI margins.
Find out about the key risks to this RLI narrative.
Another View on RLI’s Valuation
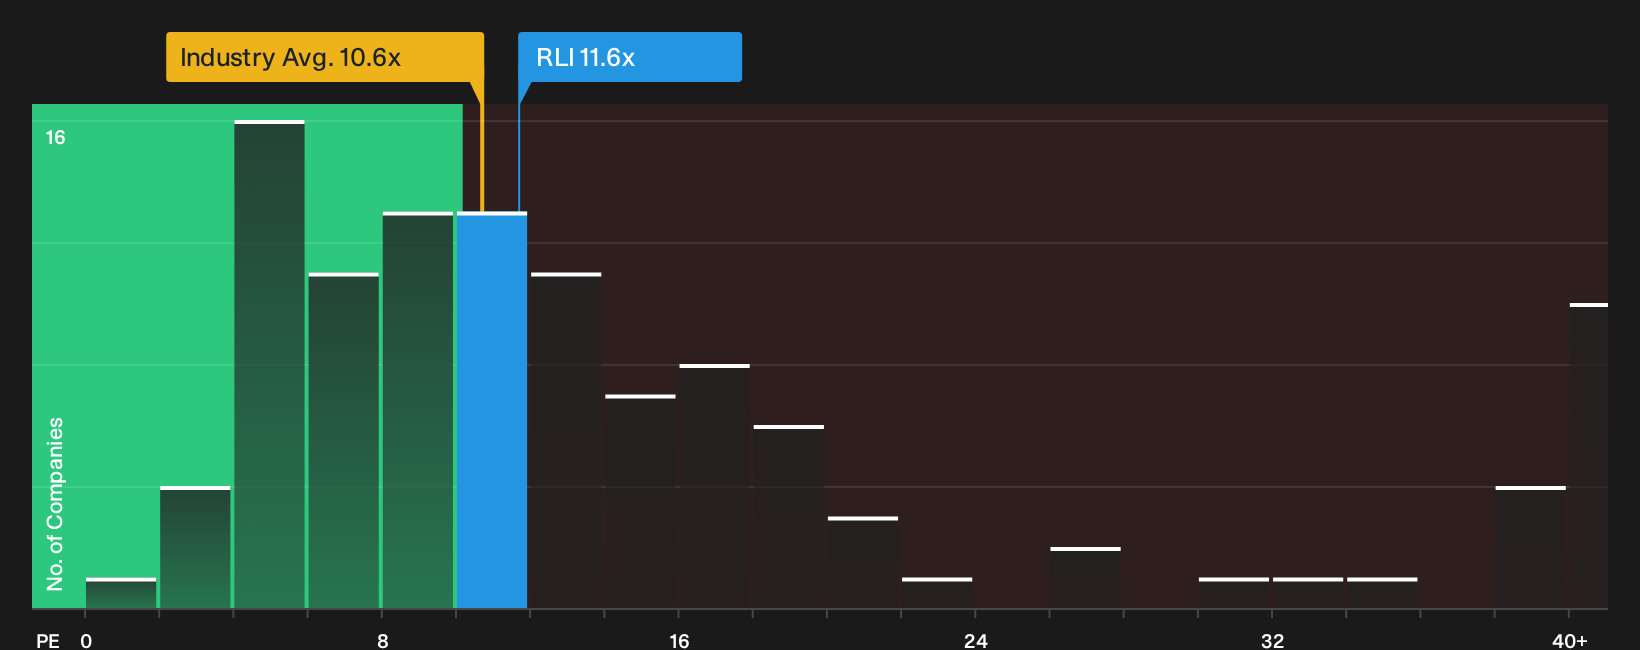
RLI looks slightly cheap on fair value estimates, yet its P/E of 11.6x is higher than both the US Insurance industry at 10.6x and a fair ratio estimate of 8.3x. That lifts valuation risk. Is the discount to fair value enough to offset paying above these benchmarks?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around RLI can feel messy, so move quickly, look through the headlines, and weigh both sides by checking the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond RLI?
If you only stop at RLI, you risk missing other opportunities that fit your style, so put the Simply Wall Street Screener to work for you.
- Target resilient balance sheets by reviewing the list of solid balance sheet and fundamentals (24 results) that pair stronger financial foundations with disciplined fundamentals.
- Hunt for mispriced quality through the 31 high quality undervalued stocks that combine robust business profiles with potentially attractive entry points.
- Build a cash flow focused watchlist using the 8 dividend fortresses that offer higher yields while still aiming for staying power.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com