
NIKE (NKE) Could Be 3% Undervalued As Board Change Tests Its Reset
NIKE (NKE) has expanded its board to twelve directors and appointed Alexandre Arnault, a senior executive at LVMH’s Moët Hennessy unit. This move introduces fresh luxury and branding experience at a challenging moment for the stock.
Recent trading tells a tough story for NIKE. The share price has slipped about 7% over the past month and about 44% year to date, while the 1-year total shareholder return is down about 47% and the 5-year total shareholder return has declined about 73%. This shows momentum has been fading despite occasional short bursts of strength, such as the small gain over the past week.
Spot opportunities while NIKE works through its reset and scan a curated set of 31 high quality undervalued stocks that currently combine quality fundamentals with depressed share prices.NIKE is now trading well below both its recent peaks and many analyst targets, with the stock around a 31% discount to the consensus and a smaller gap to intrinsic value estimates. The question is where fair value really sits within that spread.
Most Popular Narrative: 3% Undervalued
On the numbers, NIKE’s latest narrative fair value of $36.83 sits just above the recent $35.75 close, leaving only a narrow discount and a very tight margin of error for investors to work with.
Nike runs with a solid operating margin above the ~10% mark, which shows it still has some competitive advantage over competitors, even with the maturity of its business and a highly competitive industry. Despite currently having a flat revenue growth, its projections point to a slightly below economy growth rate of ~3% over the next couple of years.
See why 16 investors see NIKE as 3% undervalued.
According to andre_santos, the most followed narrative blends several valuation tools into that $36.83 figure, with discounted cash flow, earnings per share projections and historical EV/EBITDA all feeding into the assessment. That framework sits on a 10.05% discount rate, which is the cost of capital used to bring NIKE’s expected cash flows back to today’s dollars.
The narrative highlights that the discounted cash flow work lands below the market price used in that analysis at $28.77 per share, while the earnings projection method clusters closer to the trading level and the EV/EBITDA view points higher. Those three lenses give very different fair values, so the blended outcome near the current $35.75 quote leaves NIKE looking only modestly mispriced rather than clearly cheap or expensive.
The same write up notes that Monte Carlo simulations around the cash flow and EPS inputs can swing the implied value band quite widely, which underlines how sensitive NIKE’s worth is to small shifts in growth, margin or discount rate assumptions. That is why anchoring solely on any single fair value figure carries risk, particularly when the share price has already fallen sharply and sentiment is fragile.
Result: Fair Value of $36.83 (ABOUT RIGHT)
Still, the narrative could be upset if NIKE’s projected 3.09% revenue CAGR or 6.22% EPS growth rate prove too optimistic in a tougher competitive backdrop.
Find out about the key risks to this NIKE narrative.
Another View on NIKE’s Valuation
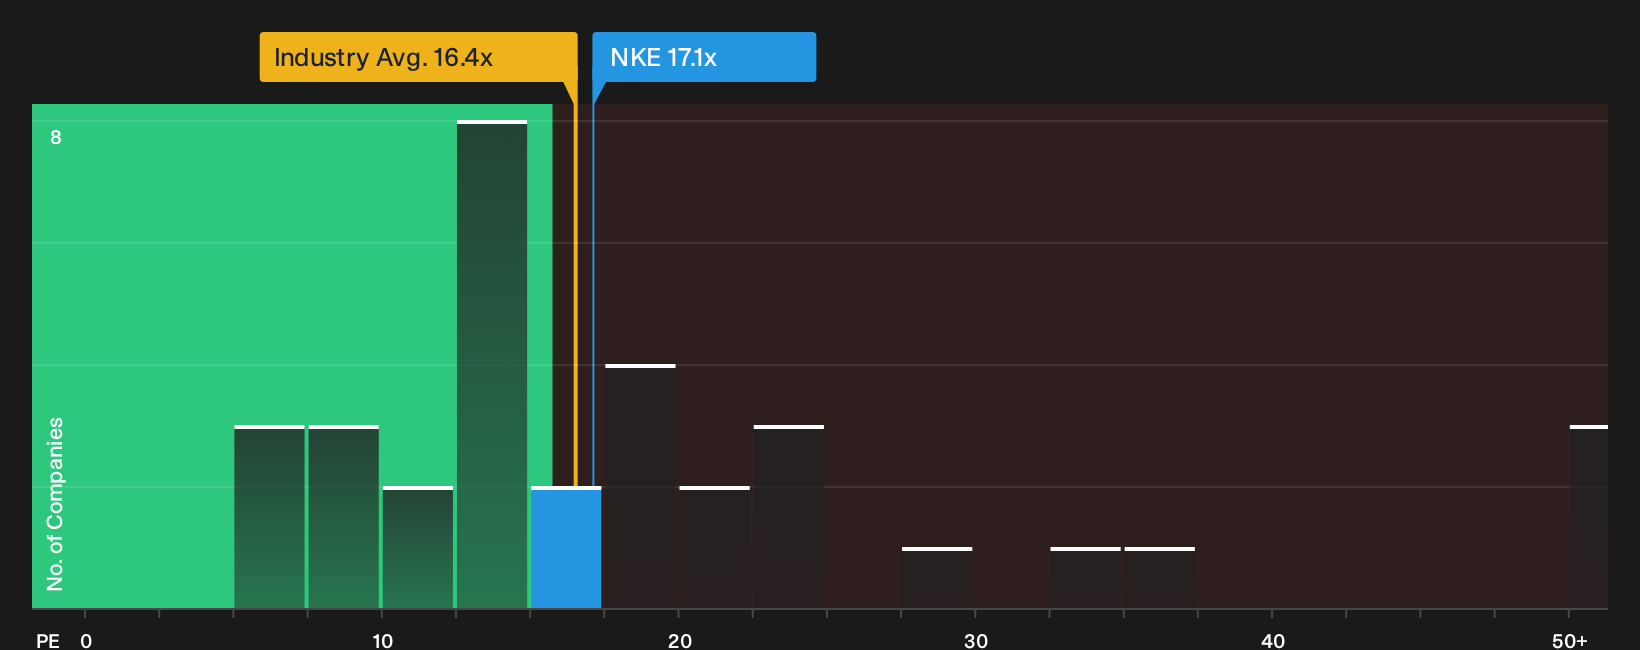
The earlier narrative leans heavily on a blended fair value around $36.83, yet the preferred P/E view sends a different signal. NIKE trades on 17.1x earnings, which is richer than both peer averages at 14.3x and the US Luxury sector at 16.4x, while the fair ratio sits higher at 22.1x. That gap leaves you weighing whether today’s discount to the fair ratio is a potential opportunity or simply compensation for slower growth and recent share price weakness.
For a closer look at the numbers behind this earnings multiple view, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on NIKE’s value story. If you want to move quickly and make your own call, start by weighing its 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond NIKE?
If NIKE’s reset has you rethinking your watchlist, broaden your search and put some structure around how you find your next opportunity.
- Target dependable cash generators and stress test your downside using a curated 30 resilient stocks with low risk scores that focuses on resilience rather than excitement alone.
- Hunt for quality on sale by scanning a focused 16 high quality undiscovered gems that many investors may not be watching yet.
- Strengthen your core holdings by reviewing a list of solid balance sheet and fundamentals (24 results) that prioritizes cleaner finances and sturdier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com