
CEVA Stock What Ziv Hammer’s New Leadership Role Could Mean
- Ceva, Inc. recently appointed Ziv Hammer as Executive Vice President, Connectivity & Sensing, a new role that unifies its connectivity, sensing and CTO functions under one leader reporting to CEO Amir Panush.
- This consolidation gives Ceva a single executive responsible for Wireless IoT, Mobile Broadband and Sensing & Audio Software, which may influence execution on more integrated Physical AI system solutions for customers.
- We will examine how Ceva's investment narrative is affected by this unified connectivity and sensing leadership structure and its market positioning.
Scan how CEVA's leadership shift fits into a wider Physical AI trend by reviewing our hand picked 87 AI infrastructure stocks shaping the next wave of connected hardware and silicon IP.
CEVA Investment Narrative Recap
To own CEVA, you need to believe the business can turn its IP portfolio in connectivity, sensing and Edge AI into steadier royalty streams, despite current losses and margin pressure. The short term swing factor is execution on new design wins, especially in consumer IoT and Wi Fi 6, where shipments have already reached record highs.
The biggest risk is still end market softness and customer concentration. Weakness in low end smartphones, industrial IoT and Bluetooth, combined with heavy R&D spend and dependence on a few large OEMs, keeps earnings fragile. The new EVP role looks helpful for coordination but does not materially change that near term risk reward balance by itself.
The most relevant announcement is CEVA bringing Ziv Hammer in to run Connectivity & Sensing and the CTO office under one umbrella. That remit covers Wireless IoT, Mobile Broadband and Sensing & Audio Software, which are the same areas analysts flag as the engines for higher royalty intensity and broader Edge AI adoption.
For you as a shareholder, the question is whether this tighter leadership link between IP roadmaps and customer system needs can support the catalysts already on the table, such as automotive, V2X and data center edge deals. Execution under Hammer will matter for how quickly CEVA converts those design wins into real scale and whether operating leverage starts to show up against rising costs.
CEVA's current revenue path is anchored to analyst expectations for 12.8% yearly top line expansion. Earnings today are at a loss of $11.8 million, and consensus earnings of $7.2 million are forecast for 2029, which implies an earnings swing of about $19 million. To line up with that view, investors are being asked to underwrite a 2029 outcome of $161.3 million in revenue and $7.2 million in earnings.
Uncover why CEVA's fair value indicates a 35% potential upside to its current price that could narrow quickly.
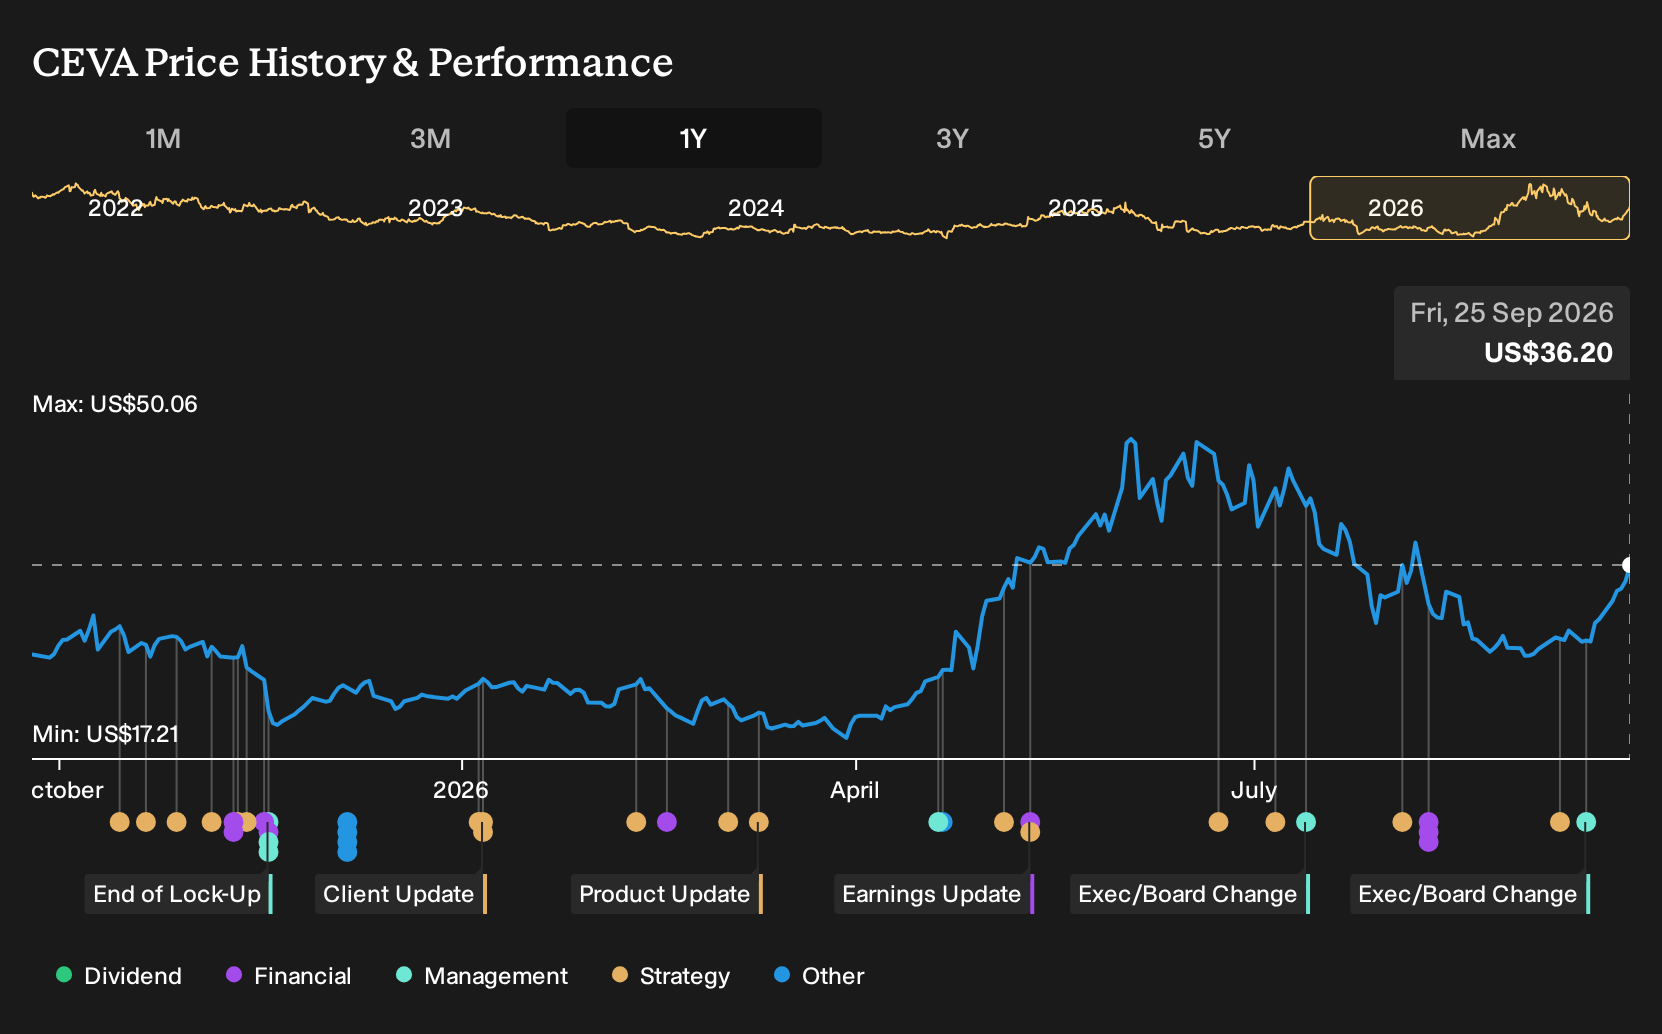
Exploring Other Perspectives
One alternate CEVA story leans hard into the data center AI catalyst. The most optimistic analysts were already penciling in revenue of about $167.1 million and earnings of $9.2 million by 2029, well above the baseline. Those views came before Hammer's appointment, so you may see forecasts shift as opinions adjust.
Explore 5 other CEVA fair value estimates, including one that suggests as much as 66% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CEVA research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CEVA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CEVA's overall financial health at a glance.
Looking For More Ideas Beyond CEVA?
If the CEVA story has sharpened your thinking and you want to stress test your thesis against other opportunities, the Simply Wall St Screener can help you quickly filter stocks that fit your risk and return preferences.
- If capital protection comes first for you, start with a basket of companies that score well on resilience using our 30 resilient stocks with low risk scores as a filter for your watchlist.
- If you care most about quality at a sensible entry point, sort for businesses that pair strong fundamentals with what our models flag as attractive pricing by running the 31 high quality undervalued stocks for comparison.
- If income is your priority, focus on sturdier payout profiles and use the 8 dividend fortresses to look for candidates with higher yields backed by fundamentals rather than story alone.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com