
What Corning (GLW)'s Multicore Fiber Spec Means For Shareholders
- Corning was involved in two recent AI-focused connectivity efforts, including a planned ECOC 2026 die-to-die optical interconnect showcase with Lumentum and Qualcomm and a released multicore fiber specification for short-reach links in AI data centers and campus networks.
- The completed SDM4 multicore fiber agreement and Corning’s role in high-density optical links highlight how its glass and fiber platforms are being positioned as core plumbing for AI scale-up architectures and advanced packaging environments.
- We will look at how Corning's investment narrative around AI-driven optical demand is shaped by its new multicore fiber standardization work.
Scan beyond Corning to spot other AI infrastructure players that are pushing bandwidth and connectivity limits with our hand picked 87 AI infrastructure stocks.
Corning Investment Narrative Recap
Owning Corning means believing its Springboard plan and AI optical push can translate into higher sales and better margins across Optical Communications and Solar, while the broader business absorbs macro and competitive pressure. In the short term, the key swing factor remains how consistently AI data center orders and solar demand show up in actual contracts and volume, not just announcements.
The main near term risk is that Corning leans heavily on non GAAP metrics while carrying meaningful debt, at a time when tariffs, macro slowdowns, and more aggressive rivals could compress pricing. The latest AI connectivity news is directionally helpful for the narrative but not a clear, stand alone catalyst yet.
The SDM4 multicore fiber specification ties directly to Corning’s pitch around Gen AI data centers. A standard that targets short reach links inside AI facilities reinforces the idea that multicore glass could sit inside customer roadmaps for denser, higher count connections. That aligns with management’s comments about optical demand as a Springboard growth pillar.
For you as a shareholder, the practical question is execution. Corning now has a published, multi vendor framework that can support interoperability, potential international standards work, and eventually transceiver specifications. That helps reduce technical risk but not commercial risk. Orders, pricing, and capex discipline across this product set will matter more than specification wins alone.
Corning's current earnings are reported at US$1.9b and analyst consensus points to US$5.5b by 2029, which implies an increase of about US$3.6b in profit, alongside forecast revenue of US$29.4b and an assumed 20.1% yearly top line growth rate over the next three years.
Uncover why Corning's fair value indicates a 22% potential upside to its current price, which could narrow quickly.
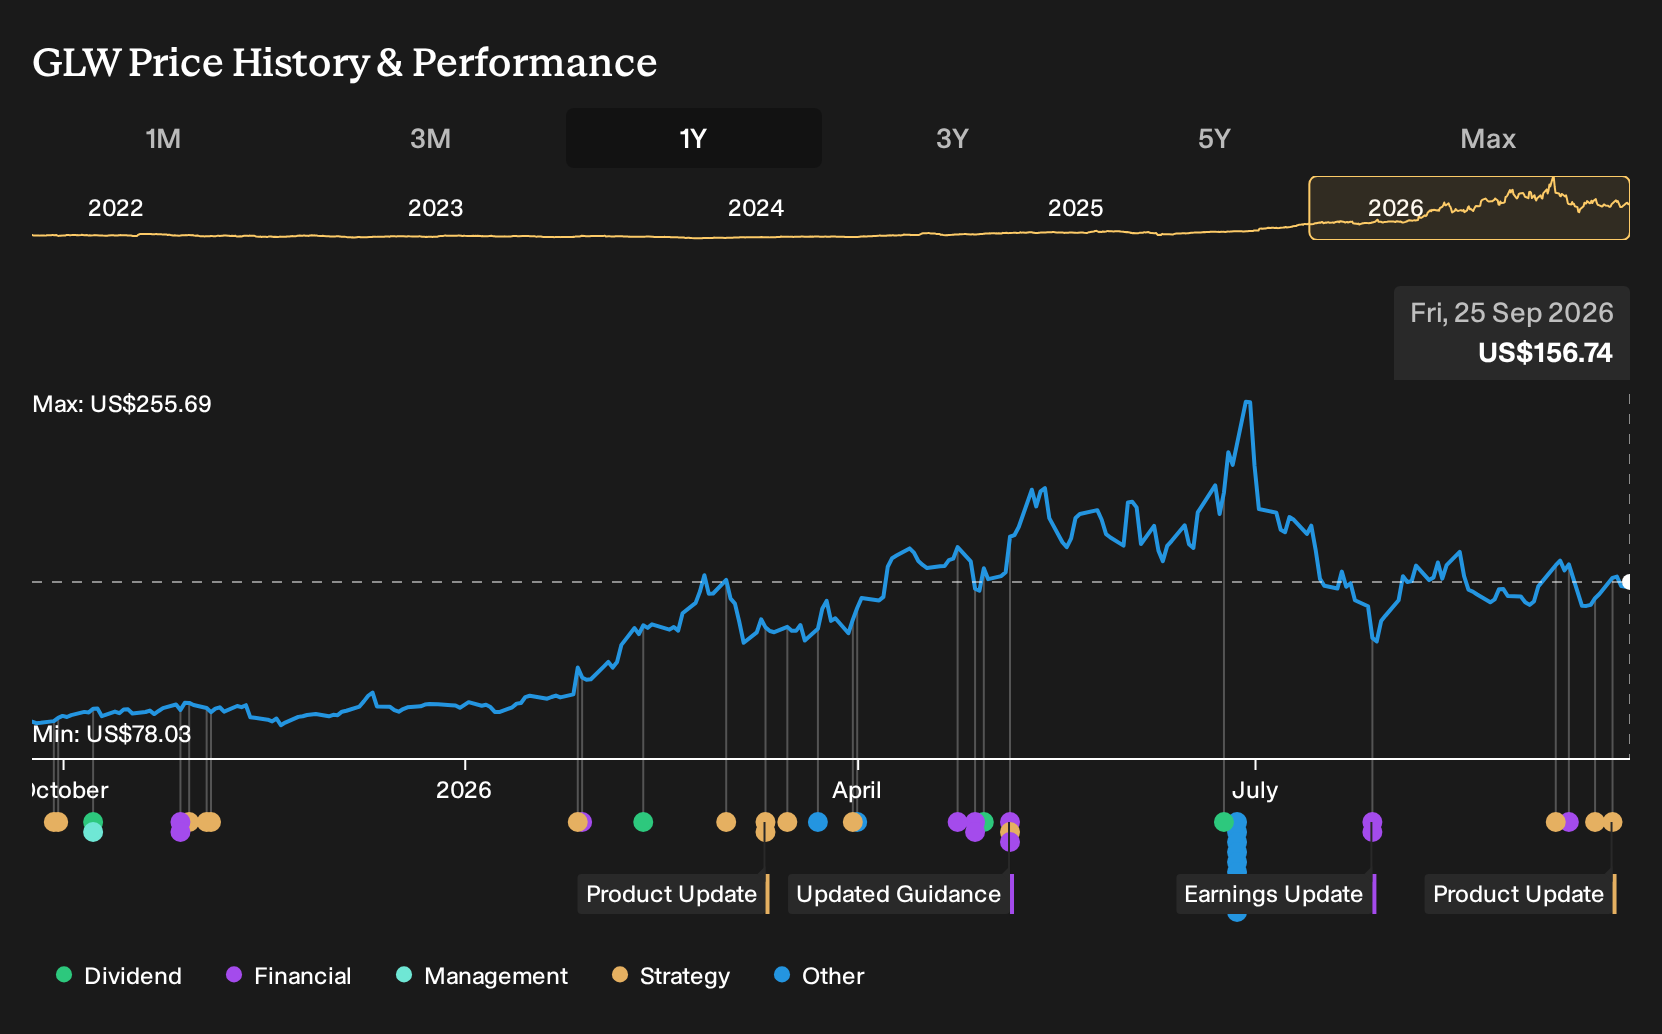
Exploring Other Perspectives
Not every analyst leans on Corning’s AI optical story as the key swing factor. The most optimistic forecasts already had revenue reaching about US$33.0b and earnings around US$7.0b by 2029, compared with consensus at US$29.4b and US$5.5b. Those views may change as this new connectivity work is more fully considered.
Explore 7 other Corning fair value estimates, including one that indicates as much as 52% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Corning research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Corning. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Corning's overall financial health at a glance.
Looking For More Investment Ideas Beyond Corning?
Once you have a view on Corning, it can help to compare it with other businesses that fit different risk and income profiles, using structured screeners rather than hunches.
- If you want potential upside with tighter risk controls, scan through 30 resilient stocks with low risk scores that aim to pair resilience with steadier fundamentals.
- For investors who care about balance sheet strength first, filter for companies in our list of solid balance sheet and fundamentals (24 results) and see which ones match your quality bar.
- If you are hunting for underappreciated opportunities, cast a wider net with our 16 high quality undiscovered gems and compare their profiles to Corning.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com