
Stifel Financial (SF) Could Be 21% Below Fair Value As AI And Rate Themes Build
Stifel Financial (SF) is drawing fresh attention after a cluster of interest rate sensitive trends, new AI spending plans, and senior hires in its Venture Banking unit converged to reshape the story.
Recent trading tells a mixed story for Stifel Financial. The share price is around US$70.35 after falling 12.9% over the past 30 days and 17.8% year to date. However, total shareholder return over three and five years is up 81.6% and 65.9% respectively, which points to longer term holders still sitting on sizeable gains even as near term momentum has faded and investors reassess interest rate sensitivity, AI spending and the push into Venture Banking.
Capitalize on the same interest rate and AI themes driving attention to Stifel Financial by scanning a hand picked set of 16 high quality undiscovered gems with similar business profiles and strong fundamentals.After a near 18% year to date slide, the question around Stifel Financial is simple: Does that setback already reflect the interest rate, AI spend, and Venture Banking risks, or does patience offer a better entry point as valuation comes into focus next?
Most Popular Narrative: 21% Undervalued
Stifel Financial's most followed narrative sets a Fair Value of $89 against the recent $70.35 close. This frames the current pullback as a valuation gap tied directly to adviser productivity, AI deployment, and the build out of venture and fund banking.
The main factor that needs to work in the company’s favor is that adviser recruitment, AI driven productivity tools, and the venture and fund banking ecosystem continue to support asset growth, client deposits, and fee pools at a faster pace than any legal and operational risks erode them.
See why 1 investors see Stifel Financial as 21% undervalued.
Result: Fair Value of $89 (UNDERVALUED)
Still, Stifel Financial’s story can crack if legal costs from broker cases climb further, or if weaker balance sheet metrics restrict loan growth and AI or venture banking investment.
Find out about the key risks to this Stifel Financial narrative.
Another View: DCF Points The Other Way
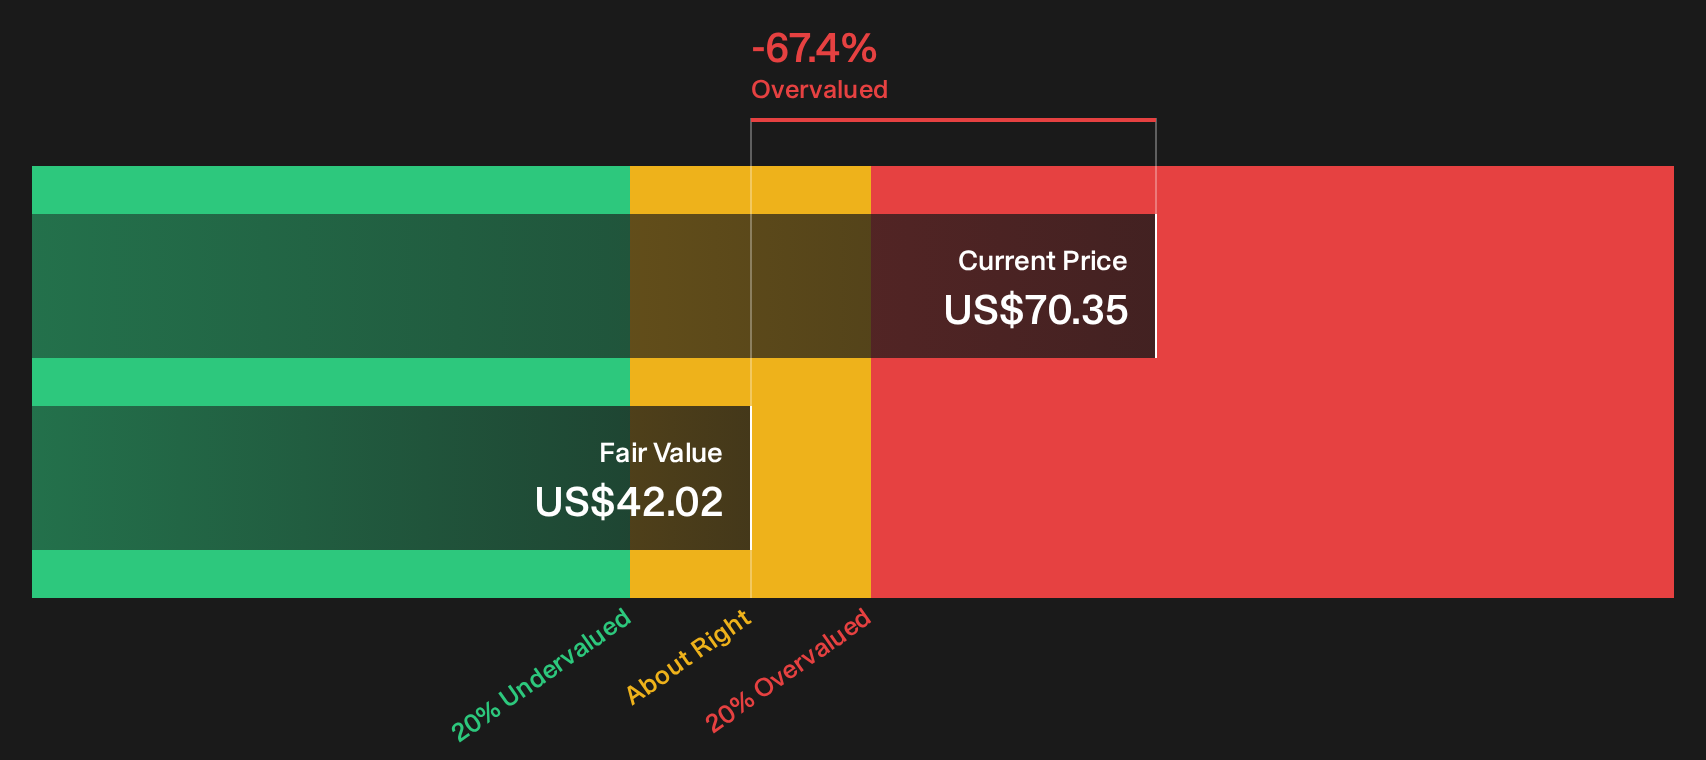
The popular Stifel Financial story leans on a Fair Value of $89, yet the SWS DCF model tells a different story. On that cash flow view, SF at $70.35 trades above an estimated future cash flow value of $42.03, which flags the shares as overvalued rather than cheap.
That kind of gap can matter in practice, because it suggests investors are paying a higher price today than the cash flow model supports, even while earnings based metrics and analyst targets lean the other way. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Stifel Financial for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Stifel Financial is split, which is exactly when fresh data can help most. Move quickly, review the upside factors and weigh the 5 key rewards.
Looking for more ideas beyond Stifel Financial?
If Stifel Financial has you thinking harder about risk, reward, and timing, consider expanding your watchlist to help sharpen your decisions.
- Zero in on resilient payouts and cash returns by scanning a curated set of 8 dividend fortresses that might suit income focused portfolios.
- Hunt for potential value opportunities by reviewing a targeted 31 high quality undervalued stocks that combine quality traits with pricing that some investors may find appealing.
- Stay on the front foot by checking a 30 resilient stocks with low risk scores that filters for businesses with steadier risk scores when markets feel unsettled.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com