
How Sector Weakness At ACM Research Shares Has Changed Its Investment Story
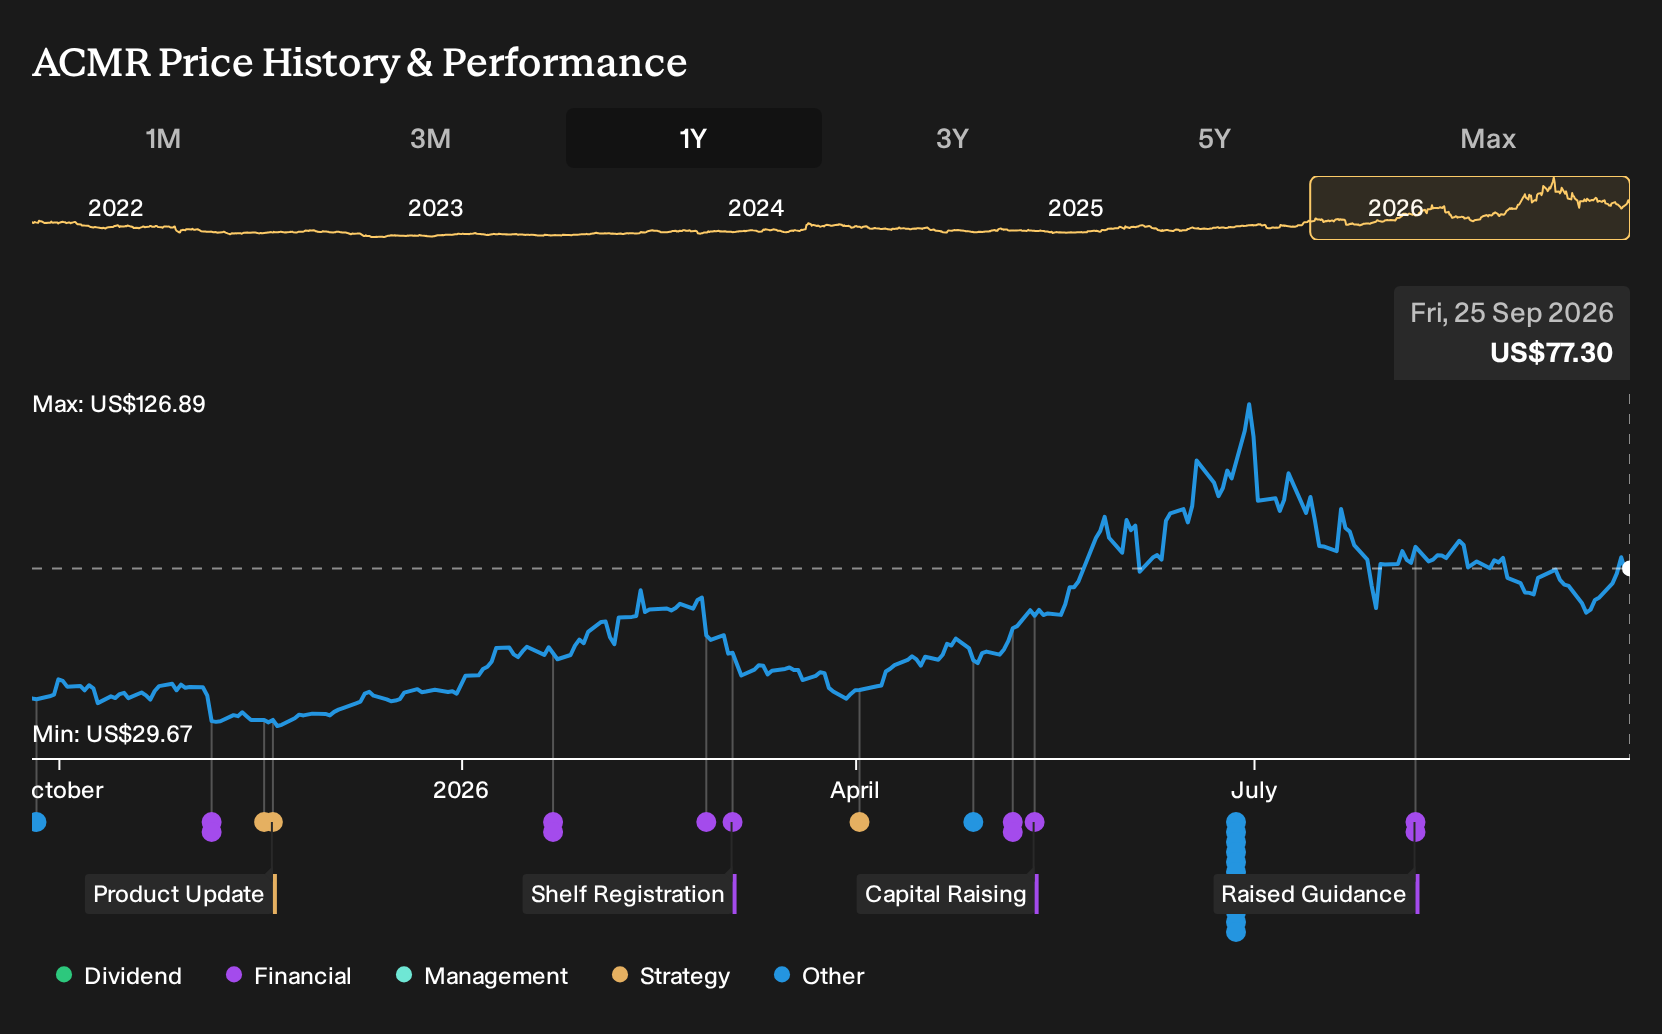
- ACM Research recently saw its shares fall more sharply than the broader semiconductor equipment group as sector-wide concern over chipmaking demand and capital spending weighed on investor sentiment.
- The selloff highlights how exposed ACM Research is to swings in wafer fab investment cycles, even as expectations for upcoming earnings remain constructive.
- We will now look at how ACM Research's investment narrative could be affected by sector-wide concern over semiconductor equipment demand.
Scan how ACM Research fits into the wider chip equipment story by comparing it with hand picked 87 AI infrastructure stocks that could also be exposed to similar spending swings.
ACM Research Investment Narrative Recap
Owning ACM Research means believing that demand for its cleaning, plating, and packaging tools can remain healthy enough for fabs to keep ordering through capital spending swings. The recent share pullback on sector worries points to how tightly the stock is tied to wafer fab budgets, rather than to any disclosed change in ACM Research's order pipeline or product set.
The near term swing factor is the next earnings report, where investors will focus on order trends, China exposure, and how well recent capacity investments are being absorbed. The key risk remains heavy reliance on the China wafer fab equipment market alongside export control uncertainty, which could quickly affect visibility on revenue and cash flow.
The most relevant update is the market focus on ACM Research's upcoming earnings release, with analysts expecting year over year growth in earnings per share and revenue. That event lines up directly with the recent sector wide selloff, because it should give investors fresh data on whether wafer fab spending cuts are spilling into ACM Research's backlog and shipments.
For you, the practical question is whether those results confirm that investments in Lingang, Oregon, and advanced tools are translating into sustainable demand, or whether working capital and inventory risk are building. Analyst optimism, including a strong Zacks rank, only matters if the earnings print and order commentary support the idea that ACM Research can handle a choppy equipment cycle without stressing liquidity or margins.
ACM Research's current analyst narrative points to revenues of $2.0b and earnings of $316.0 million by 2029, based on 24.4% yearly revenue growth and an earnings increase of about $165.8 million from $150.2 million today.
Uncover how ACM Research's fair value indicates a 49% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One big swing factor that bullish analysts highlight for ACM Research is earnings power. The most optimistic forecasts before this selloff were built on revenue reaching about US$2.2b and earnings of roughly US$455.2 million by 2029, far above the lower end near US$261.4 million. Those projections may shift as the recent drop and upcoming results reshape expectations, so treat them as moving targets and consider both the more optimistic and the more cautious scenarios before making your own assessment.
Explore 3 other ACM Research fair value estimates, including one that suggests as much as 49% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your ACM Research research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ACM Research. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ACM Research's overall financial health at a glance.
Looking for more investment ideas beyond ACM Research?
Once you have a view on ACM Research, it can help to widen the lens and compare it with other stocks that fit clear, rules based criteria using the Simply Wall St Screener.
- If capital preservation is high on your list, start with a set of companies that screen well on debt, liquidity, and balance sheet strength via the list of solid balance sheet and fundamentals (24 results).
- For readers hunting for quality at a reasonable price, scan a curated pool of potential mispriced opportunities using the 31 high quality undervalued stocks.
- If you are more interested in growth potential that the market may be overlooking, broaden your watchlist with a focused group of 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com