
What iQIYI Stock's 350 Title AI Slate Means For Shareholders
- In September 2026, iQIYI used its iJOY Conference in Shanghai to present over 350 new titles for 2026 to 2027 and outline deeper use of AI across long and short-form content, including dramas, micro-dramas, and animation.
- The firm spotlighted NadouPro and AIGC projects such as Immortals Over Mortal Love and The Ferry Man as proof points that AI tools, digital asset marketplaces, and data driven marketing can reshape how content is produced, scaled, and monetized on the platform.
- We will look at how iQIYI's investment narrative is affected by its All in AI push, anchored by the NadouPro ecosystem.
iQIYI Investment Narrative Recap
To own iQIYI, you need to believe the platform can turn its deep content library and AI capabilities into steadier subscription and advertising cash flows, despite recent revenue pressure and ongoing losses of CN¥836.8 million. The near term swing factor remains whether a busier slate actually lifts member growth and ad budgets after a period of softer demand.
The biggest risk is still content economics. iQIYI depends on hit dramas while facing high production costs and heavy competition from both long and short video platforms. The new AI heavy slate helps address cost and volume, but it does not remove the need for consistently popular shows or reduce exposure to China focused advertising cycles.
The launch of the hybrid AI drama “Immortals Over Mortal Love” on NadouPro ties directly into that near term catalyst. It is a test of whether large scale AI supported production can deliver attractive engagement while keeping spending in check, which matters for both margin improvement and the ability to keep funding a broad slate.
At the same time, the success of AIGC projects like “The Ferry Man,” which recouped production costs within a week and generated over RMB 8 million in the first month, shows that AI driven titles can already carry commercial weight. For you as an investor, the question is whether iQIYI can repeat that playbook across enough projects to smooth earnings volatility without allowing content costs to climb faster than revenue.
iQIYI's current earnings sit at a loss of CN¥683.0 million, with analysts expecting earnings of CN¥728.7 million by 2029. This implies an earnings swing of about CN¥1.41b and forecast revenues of CN¥27.0 billion in that same year, while assuming revenue remains broadly flat from today.
Uncover why iQIYI's fair value indicates a 51% potential upside to its current price that could narrow quickly.
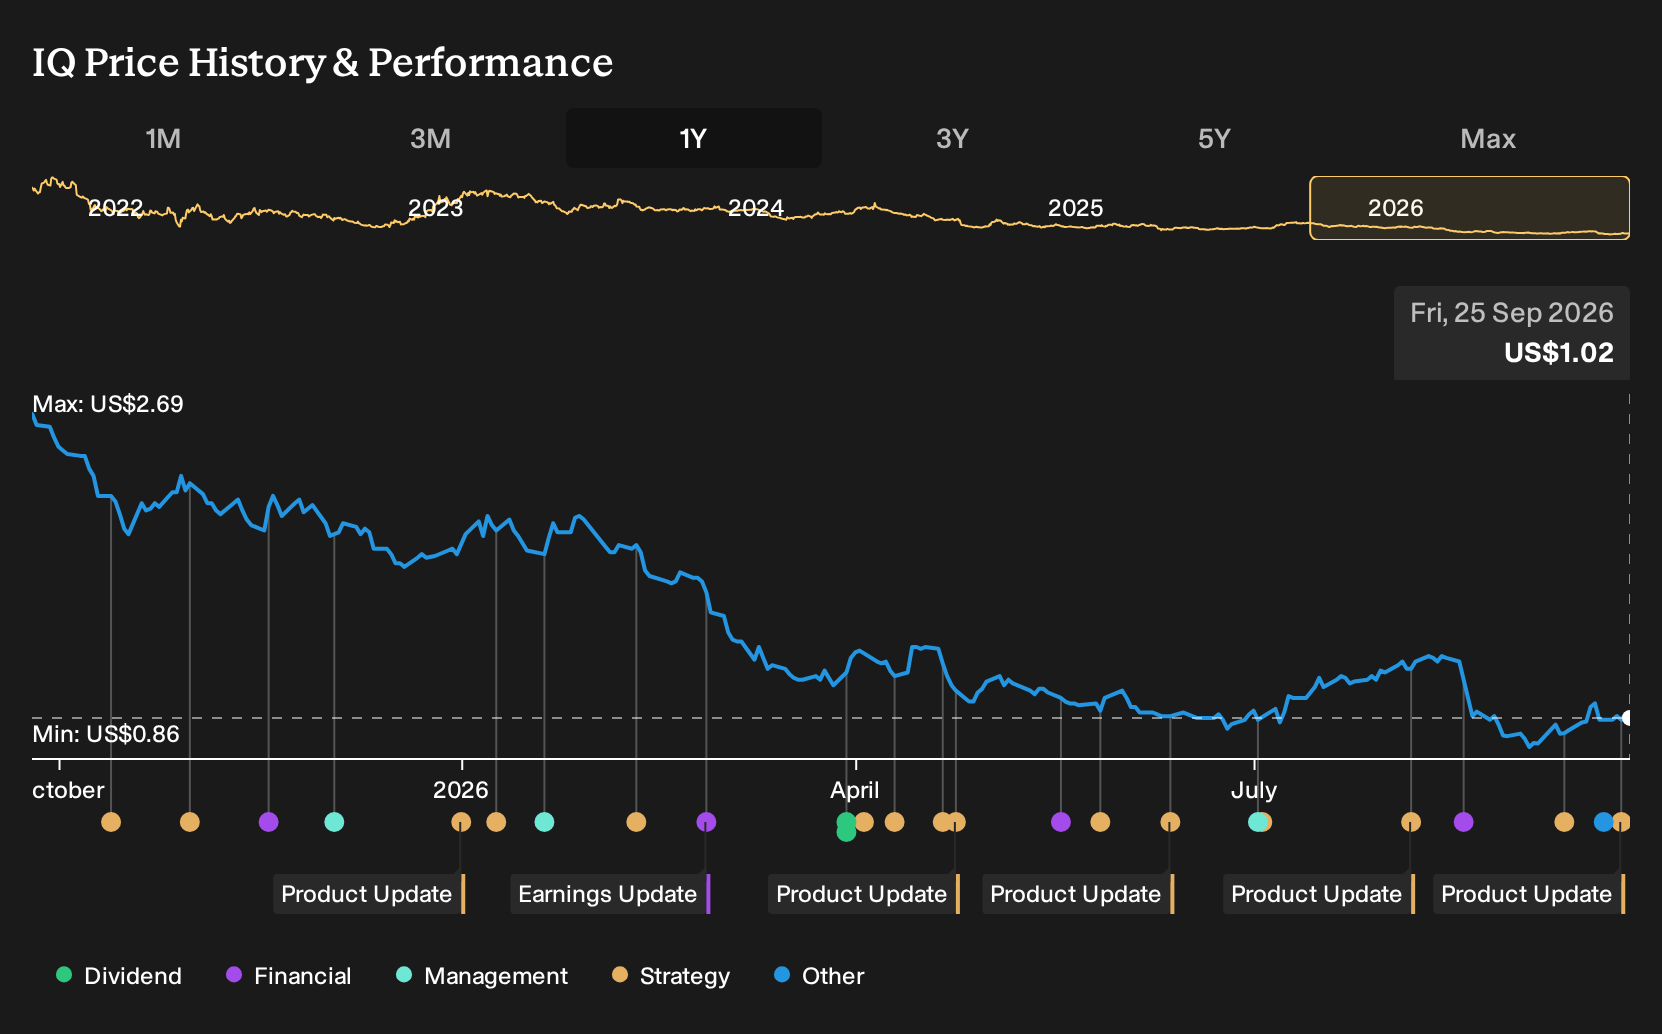
Exploring Other Perspectives
For the most optimistic analysts, the real catalyst is earnings power rather than today’s AI headlines. Before this iQIYI news, the bullish camp was modeling CN¥28.8b of revenue and CN¥1.4b of earnings by 2029, far above consensus. That gap shows how widely opinions can differ and why you may want to explore multiple viewpoints.
Explore 3 other iQIYI fair value estimates, including one that suggests as much as 199% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your iQIYI research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for iQIYI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate iQIYI's overall financial health at a glance.
Looking for more ideas beyond iQIYI?
If you want to put iQIYI in context, it helps to scan a broader field of potential opportunities and compare quality, risk, and income profiles side by side. The Simply Wall St Screener lets you do that quickly without getting buried in raw spreadsheets.
- For investors who care most about resilient balance sheets and solid fundamentals, start by reviewing a list of solid balance sheet and fundamentals (24 results) that can help anchor a more defensive portfolio.
- If you are hunting for mispriced quality, filter for companies on our 31 high quality undervalued stocks where fundamentals and valuation checks both look compelling.
- Income focused investors can zero in on yields that matter by scanning a curated set of 8 dividend fortresses that prioritize both payout strength and durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com