
Did Weak Q2 Results Just Shift Parsons (PSN) Stock Investment Narrative?
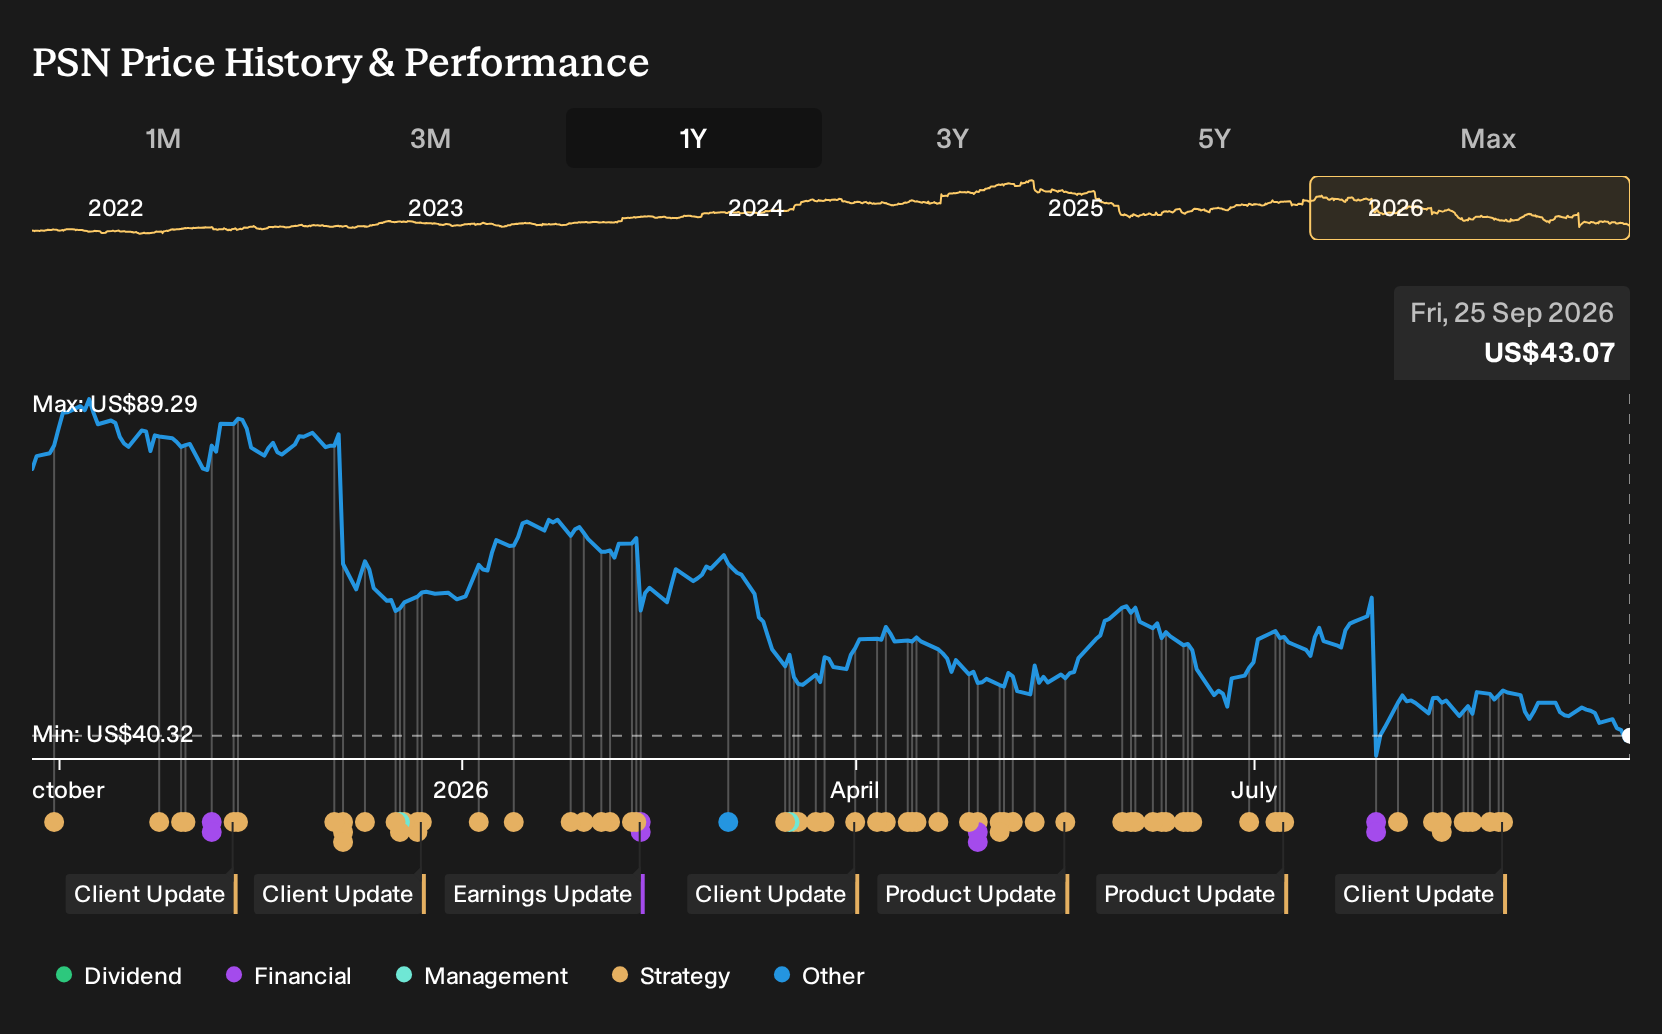
- Parsons reported Q2 revenue of $1.58b, which was flat year on year and came in 1.9% below analyst forecasts, alongside full-year revenue and EBITDA guidance that trailed expectations.
- The results marked the weakest performance versus estimates among its defense contractor peers. This highlighted pressure on Parsons' execution and outlook across both growth and profitability.
- We will now examine how Parsons' weaker-than-expected Q2 results and guidance could reshape the longer-term investment narrative around the business.
Parsons Investment Narrative Recap
For Parsons, the long-term story still hinges on confidence in recurring work from U.S. federal agencies and critical infrastructure clients, together with the shift toward higher margin, tech-enabled services. The weak Q2, with flat revenue at $1.58b and guidance below expectations, calls the pacing of that shift into question but does not rewrite the core thesis by itself.
The more immediate issue is execution on existing contracts and backlog so that earnings quality improves and margins stop slipping. That is the key near term catalyst. The biggest risk remains heavy dependence on government budgets and lumpy programs, where any contract loss or delay can quickly show up in both revenue and EBITDA.
Among recent developments, the most relevant backdrop to this Q2 miss is the earlier termination of a confidential Federal Solutions contract, which was linked to a 19% year-on-year segment revenue drop and a 35% decline in segment EBITDA. That episode already highlighted how concentrated and unpredictable some Parsons programs can be.
Given that history, the latest flat quarter and softer guidance keep the spotlight on how effectively management replenishes and diversifies the project mix in Federal Solutions and Critical Infrastructure. The key question from here is whether Parsons converts its reported backlog and pipeline into steadier cash generation while managing debt and keeping project risk in check.
Parsons' narrative projects US$7.2b revenue and US$407.1m earnings by 2029. This corresponds to 4.7% yearly revenue growth and an earnings increase of about 2.6x from the US$157.4m reported today.
Uncover why Parsons' fair value indicates a 36% potential upside to its current price, a gap that could narrow quickly as sentiment resets.
Exploring Other Perspectives
The most bearish analysts focus on cash flow risk at Parsons. Before this Q2 update, they were only pencilling in about US$6.9b of revenue and US$328.9m of earnings by 2029, far below the consensus of US$7.2b and US$407.1m. That gap shows how sharply opinions can differ, so treat this miss as a prompt to explore both stories in detail.
Explore 3 other Parsons fair value estimates, including one that suggests it could be worth just $58.55!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Parsons research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Parsons. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Parsons' overall financial health at a glance.
Looking For More Investment Ideas Beyond Parsons?
Parsons is only one piece of a much bigger opportunity set. If this Q2 update has you reassessing your exposure to contractors and project risk, it can be useful to line it up against other businesses with very different balance sheets, income profiles, and payout policies using the Simply Wall St Screener.
- If capital preservation is your first filter, start with a 31 resilient stocks with low risk scores that have held up well when conditions turn choppy.
- If you want income on top of potential price gains, scan for 8 dividend fortresses that aim to combine meaningful yields with resilient cash flows.
- If you are hunting for under-the-radar opportunities, compare Parsons with 16 high quality undiscovered gems that show strong fundamentals but attract far less attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com