
Why Edwards Lifesciences (EW) Is Getting Attention Today
Edwards Lifesciences (EW) is drawing investor attention after hiring Ganesh Mayya from GE HealthCare to lead a new digital product engineering group focused on connected, AI-enabled structural heart technologies.
Recent trading has been choppy for Edwards Lifesciences, with the share price slipping over the past month and quarter despite a modest year to date gain. At the same time, the 1 year total shareholder return of 13.17% and 3 year total shareholder return of 24.55% indicate longer term holders have still seen positive results, even as the 5 year total shareholder return declined 23.15%. This backdrop makes the new AI focused structural heart push look like an effort to refresh the growth story and potentially shift how investors view the company’s risk and opportunity mix.
Scan how Edwards Lifesciences fits into the broader medical technology shift by comparing it with 38 healthcare AI stocks that are also leaning into AI driven healthcare tools.
Edwards Lifesciences now has a clear story as a specialized structural heart leader that is leaning into AI, yet the share price near US$86 raises a simple question: Is that quality on offer or already fully charged in?
Most Popular Narrative: 14.5% Undervalued
On the most followed view, Edwards Lifesciences carries a fair value of about $100.96 per share, which sits above the recent $86.29 close and frames current trading as a discount to that narrative.
The path to at least US$2b of TMTT revenue by 2030, supported by recent guidance of US$760 to US$780 million in 2026 TMTT sales, points to further mix shift into higher growth transcatheter therapies that could contribute to overall revenue and EPS expansion.
The long term clinical durability data for SAPIEN and RESILIA valves, along with outcomes for EVOQUE and PASCAL, strengthens Edwards Lifesciences positioning with physicians and payers and may help sustain pricing and share, which can support both revenue and net margins.
See why 28 investors see Edwards Lifesciences as 15% undervalued.
Result: Fair Value of $100.96 (UNDERVALUED)
Still, the Edwards Lifesciences narrative can wobble if tariff related cost pressure squeezes margins or if the JenaValve injunction and compliance requirements restrict future deals.
Find out about the key risks to this Edwards Lifesciences narrative.
Another Look At Edwards Lifesciences Valuation
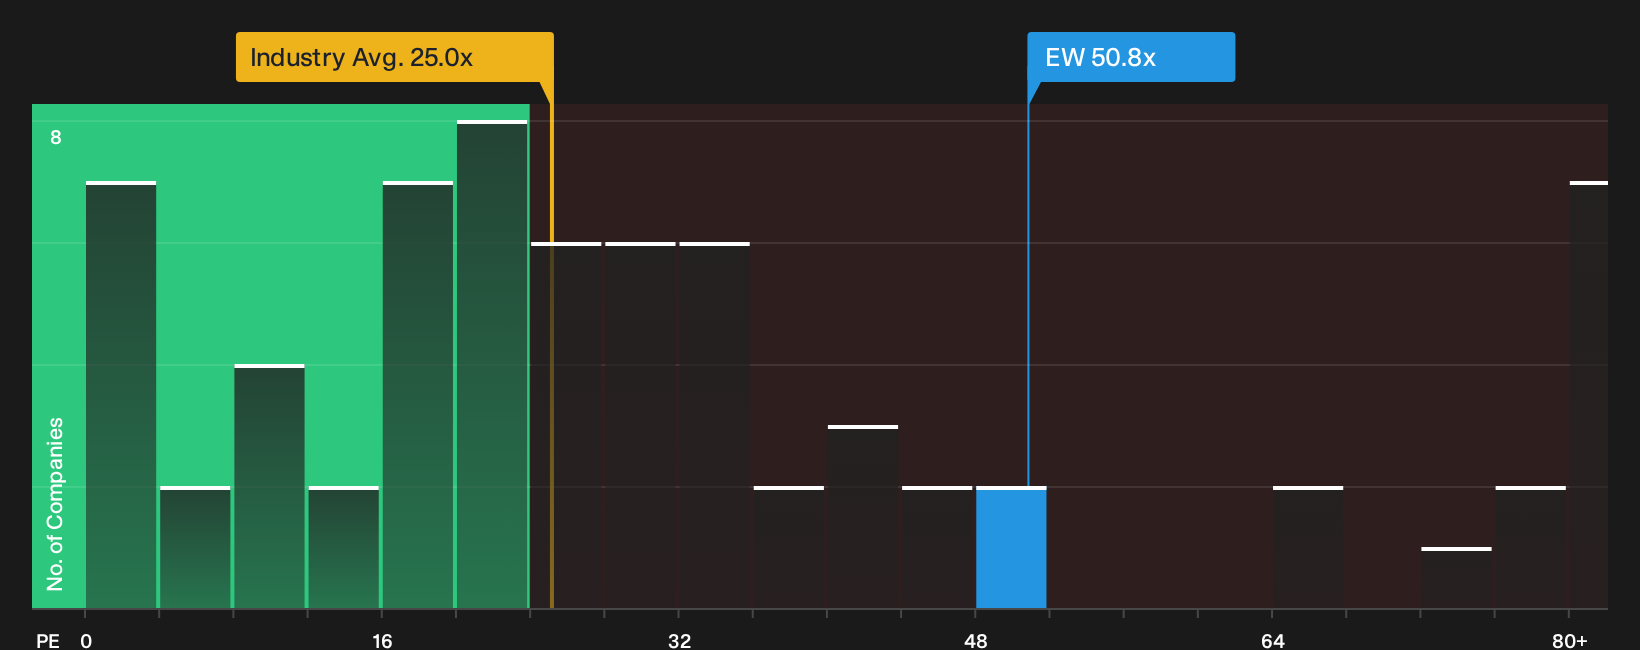
The first view frames Edwards Lifesciences as about 5.1% below an estimated fair value. On a P/E basis, however, the shares trade on 50.8x earnings versus a 25x US Medical Equipment average, a 26.1x peer group and a 34.3x fair ratio, which points to rich expectations baked into the current price. Which signal should investors focus on when real cash flows eventually show up?
For a closer read on what this earnings multiple gap could mean for future valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
So far, there are mixed signals on Edwards Lifesciences. If you want to move quickly and make your own decision, consider both perspectives by reviewing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Edwards Lifesciences?
If Edwards Lifesciences has your attention, do not stop here. Fresh opportunities are only a few clicks away when you scan the wider market with focused screeners.
- Start with quality and value by zeroing in on companies that combine strong fundamentals with attractive pricing through the 31 high quality undervalued stocks.
- Prioritise resilience by filtering for businesses that carry robust balance sheets and solid financial footing using the list of solid balance sheet and fundamentals (24 results).
- Hunt for early stage potential by checking the 8 elite penny stocks with strong financials that already show stronger financial profiles than most in their bracket.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com