
Does Earnings Miss Change The Bull Case For Texas Pacific Land Stock?
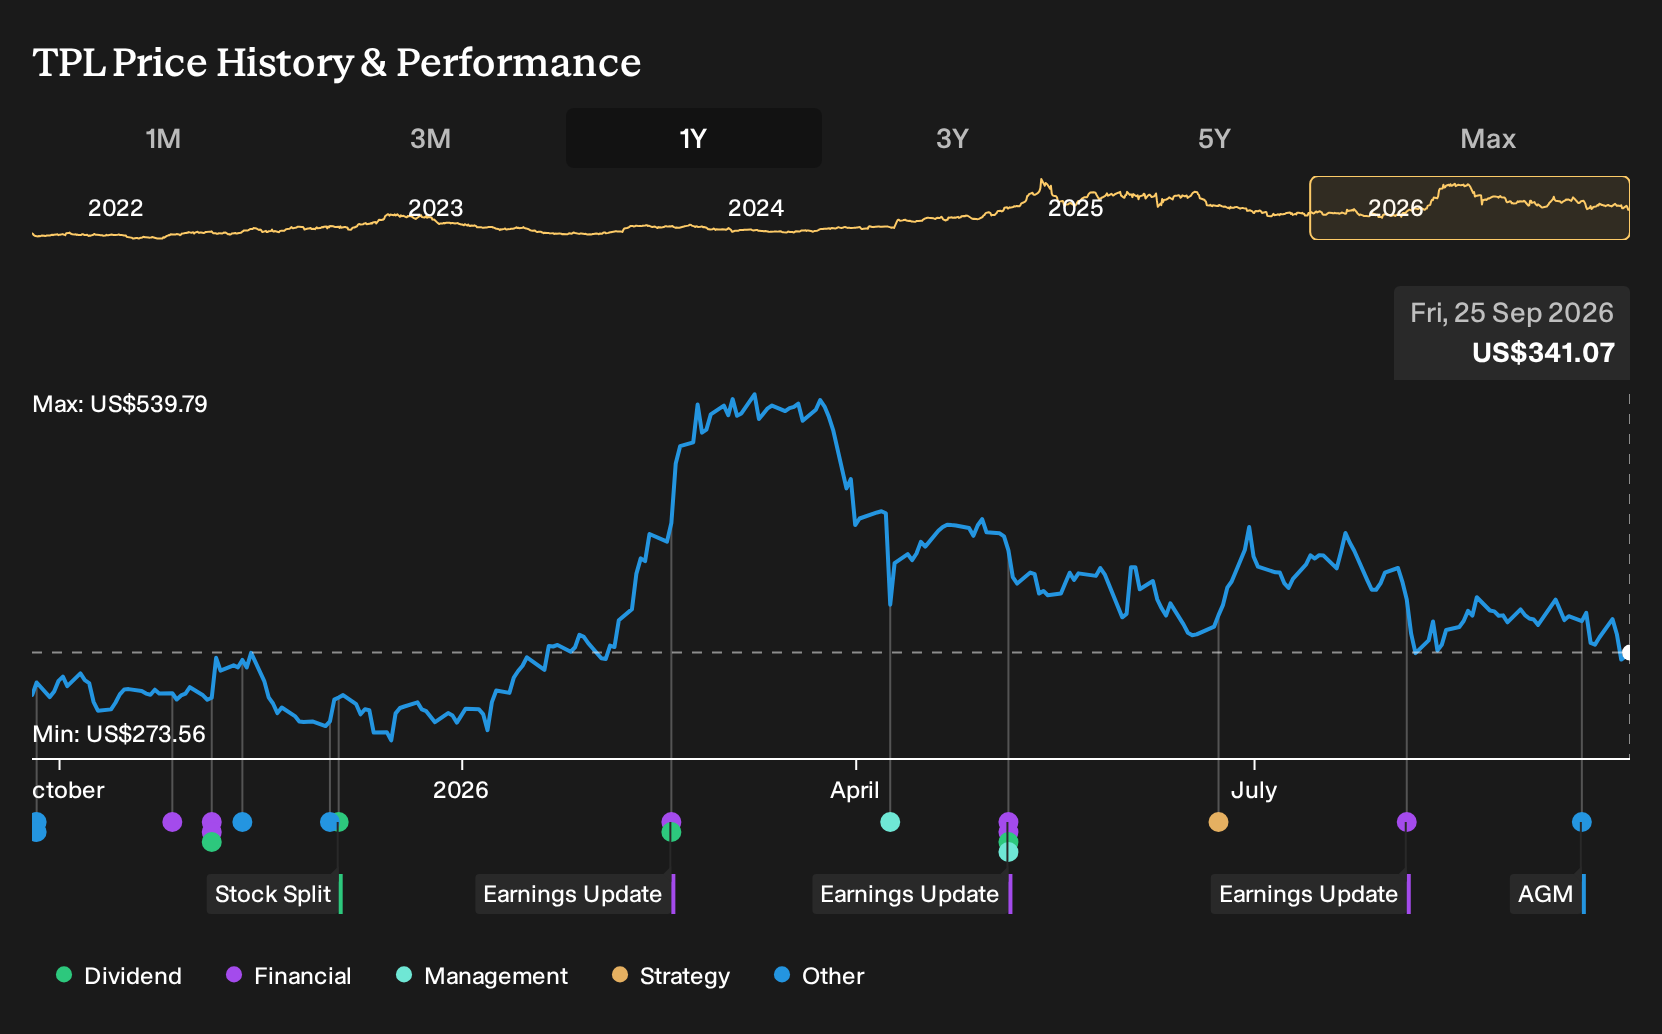
- Texas Pacific Land reported a recent quarter with 31.2% year-on-year revenue growth, but results came in below analyst expectations and the stock saw the weakest performance versus estimates among its peer group.
- The mixed report highlighted how heavily Texas Pacific Land’s fundamentals still hinge on Permian oil activity and water services, which exposes the business to commodity swings, regulatory pressure, and execution risk in its high-margin royalty and water operations.
- We will now explore how Texas Pacific Land's mixed quarterly performance and earnings shortfall interact with its existing long-term investment narrative.
Scan other asset-rich plays with similar risk and return trade offs by reviewing our curated list of 16 high quality undiscovered gems alongside Texas Pacific Land.
Texas Pacific Land Investment Narrative Recap
For a shareholder in Texas Pacific Land, the core belief is that Permian drilling and water handling stay active enough to keep royalty checks and water volumes healthy. The mixed quarter, with 31.2% revenue growth but a shortfall versus expectations, mainly pressures confidence in the near term. It does not fundamentally change that the key near term swing factor is operator activity on its acreage.
The biggest risk right now is how exposed Texas Pacific Land remains to commodity prices, local regulation and Permian specific issues, especially in its high margin water business. Any slowdown in water volumes or tighter rules on usage and disposal could matter more than a single quarter’s miss for the next couple of years.
The most relevant recent development is the same quarterly report that knocked the stock about 11% lower. Revenue expanded 31.2% year on year to about US$897.5 million over the last reported period, yet still came in below what analysts had penciled in, which raised questions about how much of the current growth run rate is repeatable.
For catalysts, that print refocuses attention on whether Texas Pacific Land can keep scaling water services and land easements while dealing with decarbonization trends and regulatory scrutiny. In the short term, investors are likely to watch execution in water infrastructure and any updates on operator activity in the Permian more closely than sentiment or target prices.
Texas Pacific Land's current analyst storyline points to revenue of about US$1.3b and earnings of US$837.1 million by 2029. That path assumes 17.2% yearly top line growth and an earnings increase of roughly US$333.5 million from the US$503.6 million reported today.
Uncover why Texas Pacific Land's fair value indicates a 30% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on Texas Pacific Land’s near term Permian swings and more on potential power and data center projects. Before this quarter, that group was modeling revenue at about US$1.5b and earnings near US$949.3 million by 2029. This is a much more upbeat storyline that may shift after this report.
Explore 5 other Texas Pacific Land fair value estimates, including one that suggests as much as 128% potential increase from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Texas Pacific Land research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Texas Pacific Land. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Texas Pacific Land's overall financial health at a glance.
Looking For More Investment Ideas Beyond Texas Pacific Land?
If the Texas Pacific Land story has sharpened your view on risk, cash generation and asset backing, use that same lens across a wider watchlist. The Simply Wall St Screener lets you quickly filter for businesses that fit your preferences on quality, volatility and balance sheet strength so you are not relying on a single stock to carry the whole thesis.
- If you want income that does more of the heavy lifting for your returns, scan for companies with resilient payouts and higher yields using 8 dividend fortresses.
- If capital preservation matters just as much as upside, narrow your search to businesses with cleaner finances and modest risk profiles through 31 resilient stocks with low risk scores.
- If balance sheet strength is your first filter, start with a curated list of solid balance sheet and fundamentals (24 results) so you are only comparing companies with financial foundations that look more robust from day one.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com