
Suburban Propane Partners (SPH) Looks Cheap On Earnings, Is The Deeper Discount Real?
Suburban Propane Partners (SPH) is back on investor radars after its recent trading performance, with the units now around $16.62. Readers are weighing distribution sustainability, recent returns, and the partnership’s long operating history.
The recent uptick in Suburban Propane Partners’ unit price sits against a wider pattern of pressure, with a 30-day share price return of 6.21% and a year-to-date share price return of 11.08% in the red, even as the 5-year total shareholder return of 54.34% shows that longer term holders have still seen solid income plus price gains.
Scan how Suburban Propane Partners compares with other income-focused utilities by reviewing a curated set of 8 dividend fortresses that pair yield with balance-sheet resilience.
Suburban Propane Partners has climbed off the lows yet still carries a patchy recent return record. Does that mix of income history, modest price target gap and current valuation still skew the risk and reward toward buyers?
Price-to-Earnings of 8.5x: Is it justified?
Valuation work on Suburban Propane Partners points to a low P/E of 8.5x at the recent $16.62 unit price, while the partnership is described as trading at good value against both peers and the wider Gas Utilities group.
The P/E ratio compares what you pay per unit with the earnings attributed to each unit. This matters a lot for a mature, income-heavy operator like Suburban Propane Partners. For a business with long-established propane and fuel distribution operations and positive net income of $130.7m on $1.39b of revenue, that earnings multiple becomes a simple yardstick for how much the market is charging for every dollar of profit.
Suburban Propane Partners is flagged as good value on several fronts, with its 8.5x P/E sitting below the peer average of 14.4x and below the Global Gas Utilities average of 13.8x. The ratio is also well under an estimated fair P/E of 15.2x. This indicates that the market valuation is lower than that estimate, although there is no certainty that it will converge toward that level.
Explore the SWS fair ratio for Suburban Propane Partners.
Result: Price-to-Earnings of 8.5x (UNDERVALUED)
Still, Suburban Propane Partners faces pressure from the recent year to date unit price decline, as well as from reliance on weather driven demand that can swing earnings.
Find out about the key risks to this Suburban Propane Partners narrative.
Another view on Suburban Propane Partners’ value
Suburban Propane Partners screens as inexpensive on earnings, yet the SWS DCF model paints an even starker picture. At $16.62, the units are described as trading about 60.9% below an estimated future cash flow value of $42.52. This points to a wide gap between price and modeled intrinsic value.
The contrast is clear. One method says the units look cheap next to peers. The cash flow model indicates that the discount is much deeper. That raises a simple question for investors: Is the market correctly pricing slow forecasts and funding risks, or is it overlooking a long-lived cash generator?
Look into how the SWS DCF model arrives at its fair value.
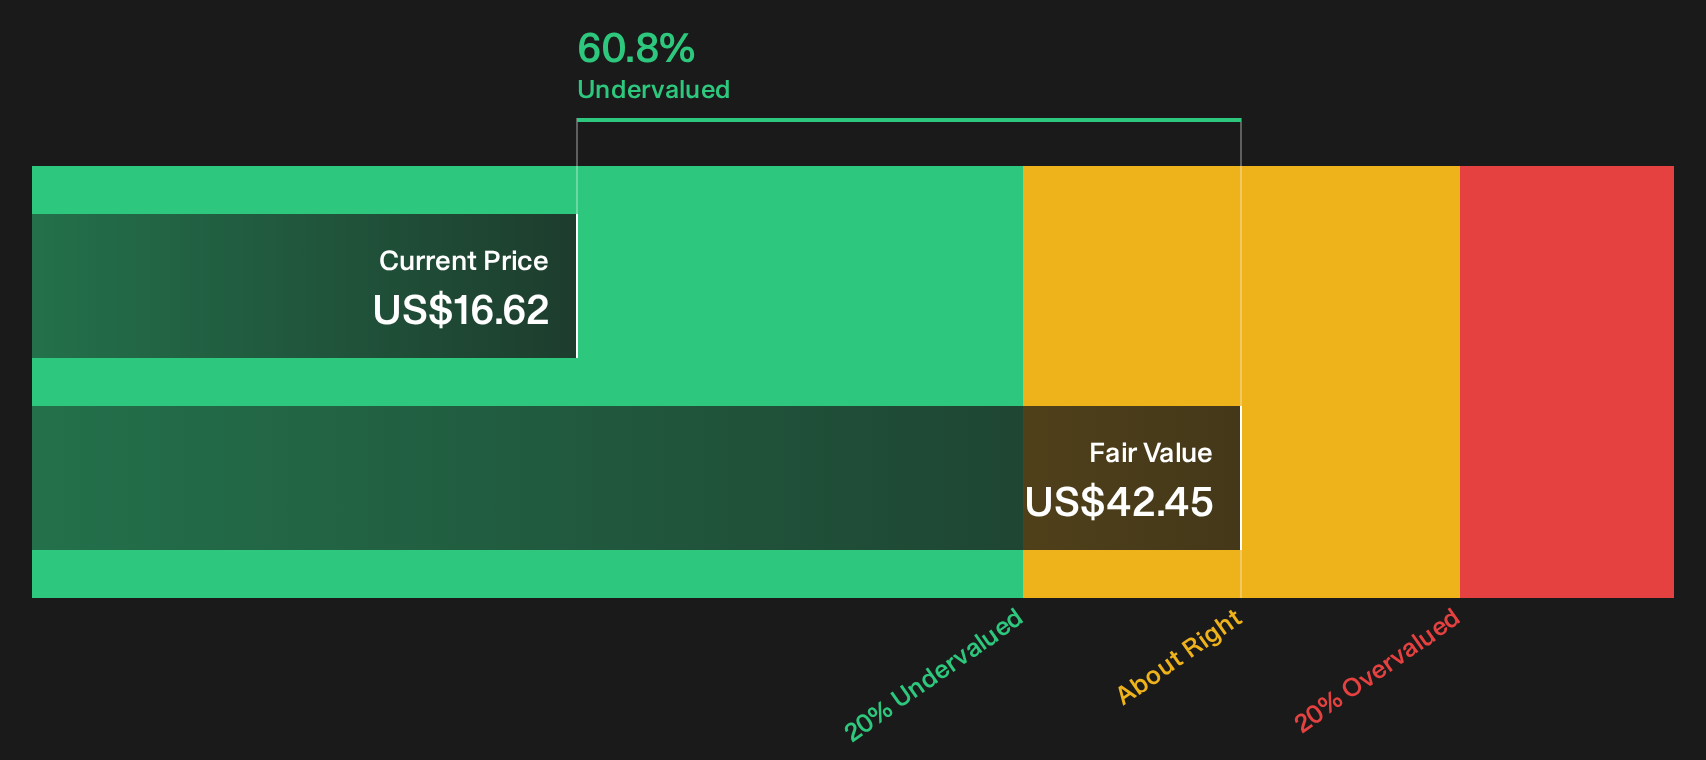
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Suburban Propane Partners for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Suburban Propane Partners can feel confusing, so move quickly from headline takes to your own verdict by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Suburban Propane Partners?
If Suburban Propane Partners has you thinking harder about value and income, do not stop here. Use targeted screeners to surface fresh candidates before the crowd moves.
- Target strong cash generation and sensible pricing by running through a curated set of 31 high quality undervalued stocks that combine quality fundamentals with compressed valuations.
- Prioritise staying power and capital preservation by filtering for a 31 resilient stocks with low risk scores that aims to keep balance sheets and volatility in check.
- Hunt for future leaders early by scanning a 16 high quality undiscovered gems that highlights under-followed businesses with robust financial foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com