
3 Stocks Riding The Friendshoring Shift In Global Supply Chains
Global supply chains are being rewired in real time as the US and China talk trade truce on one hand and tighten controls on technology and critical materials on the other. This mix of cooperation and rivalry creates potential openings for companies aligned with reshoring and friendshoring themes. In this article you will see three stocks exposed to these headlines and how this shifting map might matter for your portfolio decisions.
The three stocks below are just a sample, with the full screen surfacing 228 more companies whose reshoring and friendshoring stories are not covered here but may be just as interesting for a supply-chain themed watchlist. To go deeper and turn headlines into a working shortlist, head straight to the Supply-Chain Diversification and Friendshoring Beneficiaries screener to identify, filter, and analyze the highest-conviction plays linked to this theme.
TTM Technologies (TTMI)
TTM Technologies sits squarely in the friendshoring story, supplying complex PCBs, RF components, and mission systems that help electronics and defense customers shift critical production into US allied manufacturing hubs.
TTM Technologies manufactures advanced PCBs, RF components, and mission systems across commercial and aerospace and defense markets, generating about US$2.0b from Commercial operations and roughly US$1.4b from Aerospace & Defense, with a market value near US$13.6b.
Growing industry-wide emphasis on supply chain resiliency and secure domestic sourcing is likely to shift PCB market share toward North American providers such as TTM. This may result in relatively stronger revenue and free cash flow performance if customers increasingly prioritize domestic production.
The real swing factor is how pressure on cost structure and capacity utilization ultimately feeds through to earnings power.
That earnings sensitivity is exactly where the story gets interesting, and the full narrative for TTM Technologies shows how supply-chain rewiring and defense demand could reshape that earnings profile.

Lasertec (TSE:6920)
Lasertec supplies inspection and measurement tools to chip fabs and electronics manufacturers that are spreading capacity across Japan, Korea, Taiwan, the US, and Europe as supply chains diversify. It generated about ¥230,485 million (¥230.5 billion) from this equipment business and carries a market value near ¥3,666.8 billion.
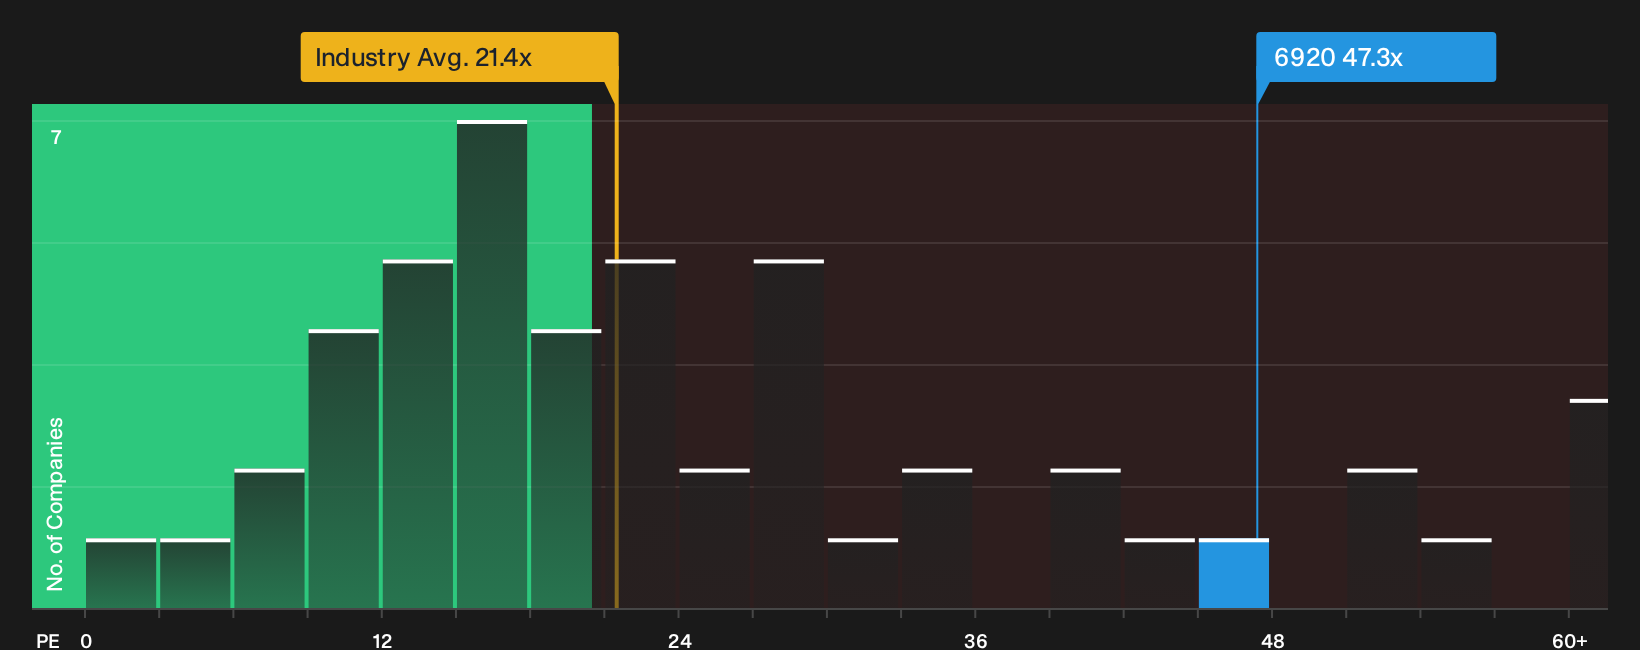
For investors focused on friendshoring, Lasertec plugs directly into semiconductor and advanced manufacturing capex across allied hubs. It has forecast double digit earnings and revenue growth, a high 31.4% ROE, and a 33.6% net margin. These figures contrast with a rich 47.3x P/E that leaves plenty riding on how one pressure point in the chip equipment cycle plays out.
That rich multiple leaves a lot to prove, so run through the 1 key reward and 2 important warning signs (2 are major!) to see whether Lasertec’s valuation premium masks upside or fragility.
Flex (FLEX)
Flex is a friendshoring heavyweight, running design, manufacturing, and supply-chain solutions for global brands while helping shift production into allied hubs. It generates about US$11.6b from Integrated Technology Solutions, US$10.5b from Regulated Manufacturing Solutions, and US$7.2b from Cloud and Power Infrastructure, with a market value near US$42.4b.
For investors focused on supply-chain diversification, Flex ties the theme together by using its global footprint to move complex hardware closer to end markets and turning trade friction into a service it can charge for.
The CPI Spin-Off Announcement (May 2026): Flex unveiled a plan to separate into two independent, public entities by spinning off its Cloud & Power Infrastructure (CPI) division.
The key question is how one underappreciated shift in the economics of high-power, AI-heavy manufacturing shapes Flex’s long run earning power.
That shift in earning power is exactly what the full narrative for Flex unpacks, showing how the CPI spin and AI hardware demand could re-rate Flex’s story.

Seeking Fresh Alternatives Before They Fly
Fresh themes often move first, and slow portfolios can get caught watching from the sidelines. Scan for quiet momentum while it still matters and build your next watchlist, act now.
- Spot stronger balance sheets before the crowd by scanning the list of solid balance sheet and fundamentals (24 results) and focus your attention on businesses that still look financially resilient and remain under the radar for now.
- Track the next leg of the AI buildout by following infrastructure enablers through the 87 AI infrastructure stocks and position your watchlist where capital spending pressure is building.
- Identify cash generative AI players, not just stories, by screening the 37 profitable AI stocks that aren't just burning cash and keep the focus on companies already turning algorithms into earnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com