
Has Novo Nordisk (CPSE:NOVO B) Fallen Far Enough To Look Cheap?
Novo Nordisk has seen its stock retreat over the past few years, which puts fresh attention on a simple question. Is the current share price in line with what the company is earning today and is expected to earn in the future.
- Over the past 3 years, Novo Nordisk shares have declined 57.2%, which puts a lot of weight on whether the underlying earnings story still supports the current valuation.
- Recent agreements in obesity, diabetes and cardiometabolic treatments, along with AI and drug discovery partnerships, may support expectations for future profit streams and influence what investors are willing to pay for each unit of earnings today.
- Your read on Novo Nordisk is one view; the desks covering it have another. See what analysts think Novo Nordisk's shares could be worth.
For investors, the debate is whether Novo Nordisk's current share price is justified by its earnings power when set against the Fair Ratio benchmark.
If you want a broader starting point while you reassess Novo Nordisk and its earnings, run the same question across 228 resilient stocks with low risk scores.
Is Novo Nordisk Still Cheap on Earnings?
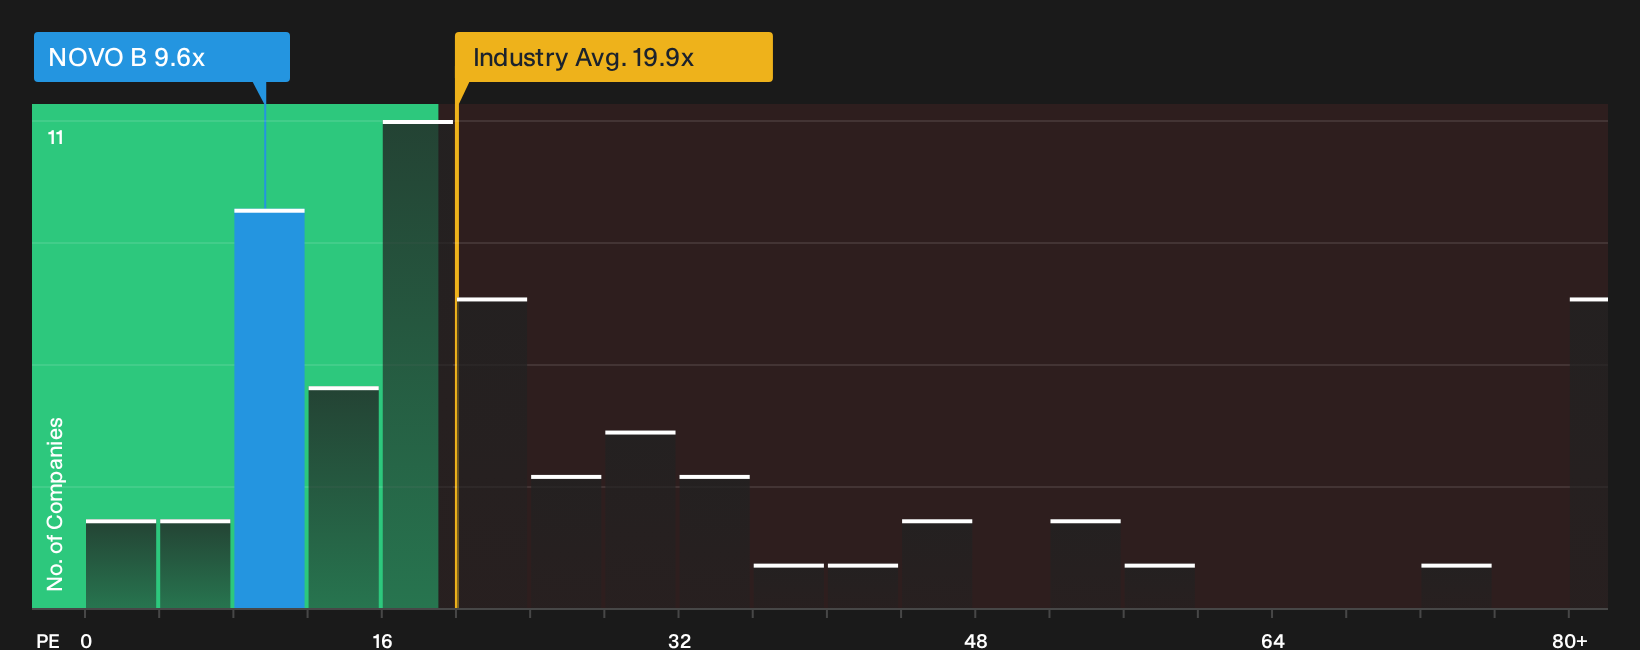
The P/E ratio is a useful lens for Novo Nordisk because earnings remain a key driver of how investors frame large pharmaceuticals. Right now, Novo Nordisk trades on a P/E of 9.6x, which is far below the Pharmaceuticals industry average of about 22.1x and also below peers at roughly 22.6x. That gap means the market is currently paying much less for each unit of Novo Nordisk earnings than it is for many comparable drug makers.
The Fair Ratio benchmark, which adjusts for factors like profitability profile, scale and sector risk, points to a higher P/E than where Novo Nordisk trades today. On this basis, the shares appear undervalued on earnings. Despite recent pressure on the story after the 2030 pipeline update and competitive concerns around GLP 1s, the current earnings multiple still prices Novo Nordisk at a sizable discount to what this model suggests investors might typically pay for a business with these characteristics. Explore the numbers behind Novo Nordisk's P/E valuation.
The Novo Nordisk Narrative: What Would Justify Today's Price?
Novo Nordisk Narratives on Simply Wall St pick up where the valuation puzzle leaves off. They explain which future paths for growth, margins and earnings would need to occur for the shares to be worth meaningfully more or less than today’s price. They also turn a single ratio or model output into a set of concrete expectations you can watch over time to see whether that story is still on track.
Community views on Novo Nordisk are split between those who see a powerful franchise temporarily mispriced and those who think key risks are still not fully factored in.
Bull case: 70% undervalued
"With the unexpected success of its obesity drugs, the company has effectively gained a highly profitable new business segment almost for free…"
Discover why this Narrative puts Novo Nordisk at 70% undervalued.
Bear case: 26% overvalued
"Heavy reliance on blockbuster therapies and looming patent expirations expose Novo Nordisk to revenue pressure from biosimilar competition and pricing headwinds…"
Explore why this Narrative puts Novo Nordisk at 26% overvalued.
Before acting on Novo Nordisk’s valuation, there is one more piece to examine
The people setting Novo Nordisk’s priorities and their pay structures can strongly influence how future profits are pursued, managed and shared with shareholders. However, that alignment has not been explored here. See who runs Novo Nordisk and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com