
How Argus Sell Downgrade Will Impact Sonic Automotive Stock Investors
- Argus cut Sonic Automotive to a SELL rating on 23 September 2026, highlighting concerns around the auto retailer’s operating outlook despite its large U.S. dealership footprint.
- The downgrade draws attention to how Sonic Automotive balances its capital intensive dealership model with execution on used vehicles, services, and digital retail initiatives.
- This article explores how Sonic Automotive's investment narrative around EchoPark, fixed operations, and digital retail intersects with Argus's recent SELL downgrade.
Broaden your watchlist beyond Sonic Automotive by reviewing a curated batch of auto retailers and related plays screened as 31 high quality undervalued stocks that may offer stronger risk and reward profiles after this downgrade.
Sonic Automotive Investment Narrative Recap
Sonic Automotive still appeals to shareholders who believe its mix of franchised dealerships, EchoPark used cars, and higher margin service work can generate steady cash flows as the industry leans further into digital retail. The near term story hinges on keeping EchoPark disciplined on costs while fixed operations stay resilient as a profit anchor.
The decision by Argus to cut its rating to SELL focuses attention on execution risk rather than changing the day to day mechanics of the business. The most immediate swing factor remains how Sonic Automotive manages inventory and pricing across new, used, and parts. The biggest risk sits in its high fixed cost footprint if volumes soften.
There have been no fresh company announcements tied directly to the Argus downgrade, so the most relevant reference point is still the existing operating profile. Sonic Automotive generated US$15.5b of revenue across its three segments, with the Franchised Dealerships arm contributing the bulk and EchoPark and Powersports forming smaller but meaningful pieces.
That mix matters when you think about catalysts. EchoPark is aimed at the used car market, where disciplined inventory management and financing income can influence profitability quickly. Franchised stores and service bays depend on recurring maintenance, parts, and warranty work. This ties back to the key risk that interest costs and high fixed expenses may remain elevated if unit throughput weakens.
What The Sonic Automotive Forecasts Assume
Sonic Automotive's forecast framework points to revenues of US$18.8b and earnings of US$298.4m by 2029. That profile builds on analyst assumptions of 6.6% yearly revenue growth and implies an earnings increase of about US$86.4m from US$212.0m today.
Uncover how Sonic Automotive's fair value indicates a 52% potential upside to its current price before the market closes that gap.
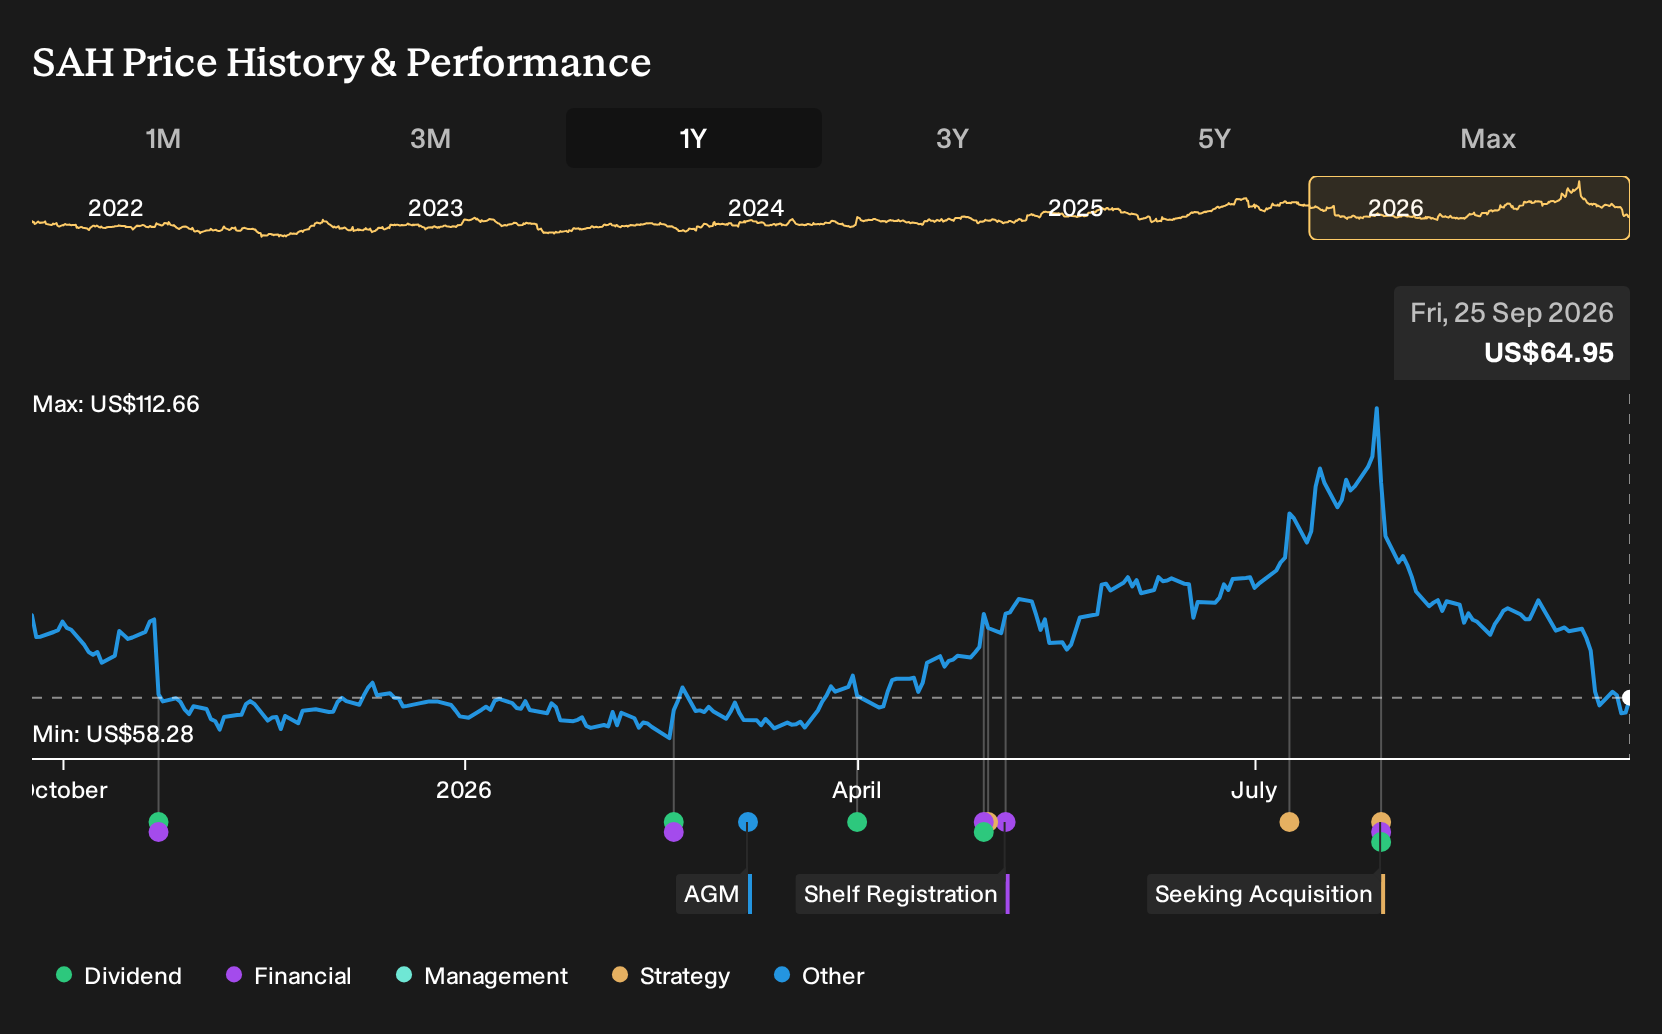
Exploring Other Perspectives
One alternate view puts Sonic Automotive’s physical expansion risk front and center. The most pessimistic analysts were only penciling in about US$16.8b of revenue and US$286.9m of earnings by 2029, on a lower 8.7x P/E. That is a far cooler story than consensus, and Argus’s new SELL call may push some forecasts closer to that camp. You do not need to pick a side today; however, it helps to read both versions and decide which assumptions feel more realistic to you.
Explore 4 other Sonic Automotive fair value estimates, including one that suggests as much as 34% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Sonic Automotive research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sonic Automotive. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sonic Automotive's overall financial health at a glance.
Looking for more Sonic Automotive sized ideas?
If this Argus downgrade has you reassessing Sonic Automotive, it can be useful to widen the search and compare it with other businesses that fit different risk and return profiles.
- If capital preservation ranks high for you, scan a set of companies with sturdier looking finances through the list of solid balance sheet and fundamentals (24 results).
- For investors hunting for mispriced opportunities, run through the 16 high quality undiscovered gems that pair quieter profiles with stronger underlying fundamentals.
- If lower volatility and steadier characteristics appeal more after this rating cut, filter for candidates using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com