
Hut 8 (HUT) Stock Looks Overvalued On Its $140 Million Texas Deal
Hut 8 has surged on the chart over the past year, and the question now is whether a business this tied to data centers and bitcoin mining is priced sensibly against its sales. With the share price moving quickly and new projects on the table, investors are left asking what the current valuation actually reflects.
- Over the past 12 months, Hut 8 has returned about 192.0%, which puts real pressure on the question of how much sales power is already priced in.
- The recent US$140 million agreement to acquire Poolin’s Texas data centers, along with new build outs in Texas and Louisiana, can reshape the company’s revenue base and the capital invested to support it.
- There is a second opinion on Hut 8 worth weighing. See what analysts think Hut 8's shares could be worth.
The issue now is whether Hut 8's current share price is justified by the sales the business is generating and investors expect it to produce.
If you are weighing Hut 8 against other ways to play the same theme, it can help to compare it with a wider set of 87 AI infrastructure stocks.
Has Hut 8 Run Too Far on Sales?
P/S fits Hut 8 because revenue is the cleaner yardstick for a business where earnings are volatile and heavily shaped by big build outs and digital asset swings.
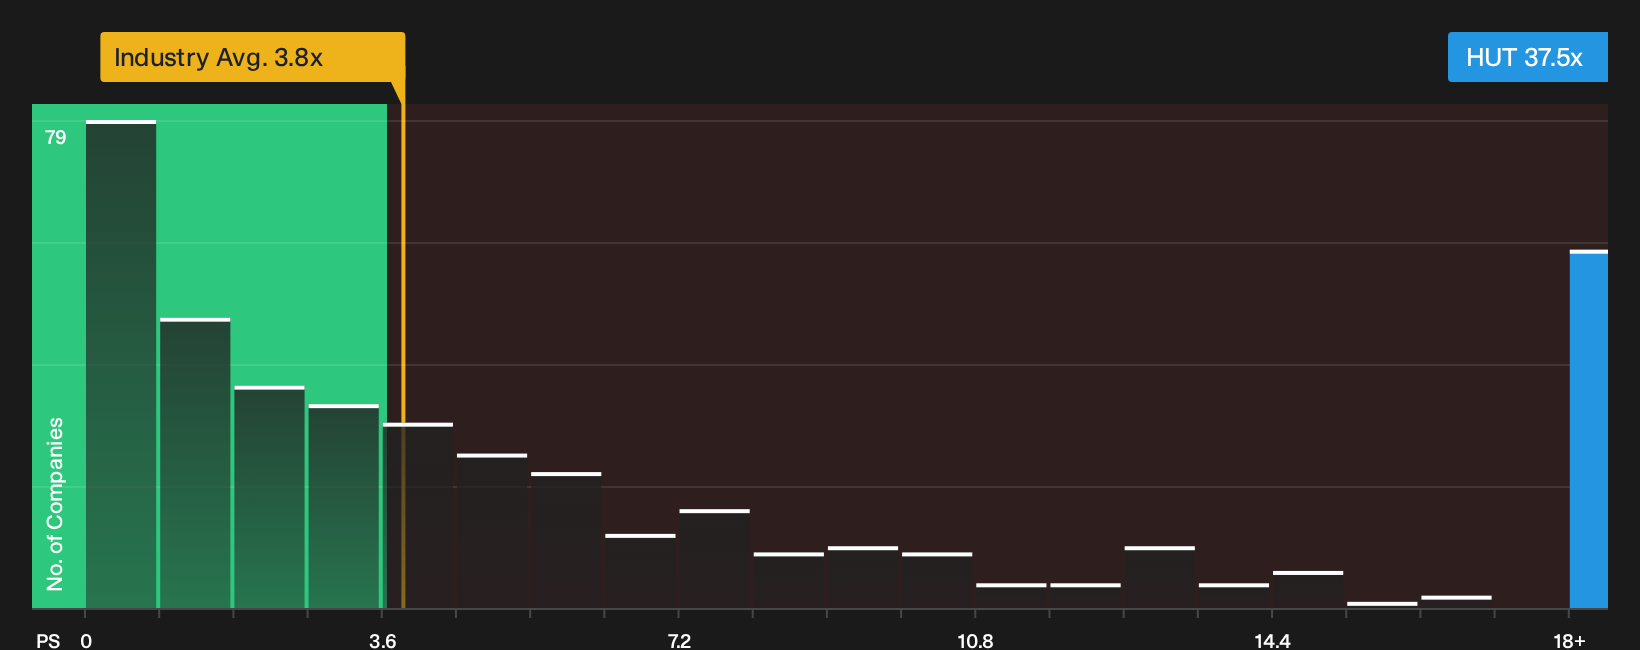
On that basis, Hut 8 trades at a P/S of 37.5x, which is far above both the wider software group on 3.8x and a peer set closer to 1.5x. The fair multiple implied by its own profile of growth opportunities, margins, size and risk sits well below that level, so the stock screens as overvalued on this framework. Because the recent US$140 million push into Poolin’s Texas assets has sharpened interest in Hut 8 as an AI and bitcoin infrastructure play, the current ratio suggests investors are already paying a sizeable premium for that expansion story. Explore the numbers behind Hut 8's P/S valuation.
The Hut 8 Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this Hut 8 valuation puzzle leaves off. They spell out which combinations of future growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today’s price. Each narrative ties a fair value to a specific set of potential catalysts and risks for Hut 8, so you can track over time which version of the story is coming through in the numbers.
One of the top community narratives on Hut 8: 19% undervalued
"The company's diversification into AI and data centers, longer-term contracts, and strategic partnerships positions it for steadier revenue and resilience..."
Discover why this Narrative puts Hut 8 at 19% undervalued.
One more Hut 8 check that belongs alongside the price tag
Before you stop at the chart and the P/S ratio, it is worth asking who is actually steering Hut 8 and how their pay pushes them to make certain choices over others. See who runs Hut 8 and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com