
Chewy (CHWY) Stock Looks Fully Valued Following Its 73% Five Year Slide
Chewy has seen a steep share price reset over the past several years, which puts a harsh spotlight on what investors are really paying for in terms of its earnings. With the stock now trading at US$18.27, the key issue is whether that valuation lines up with the profit power the business currently delivers.
- Chewy’s share price has fallen 72.9% over the past 5 years, which puts the focus firmly on whether the current earnings justify staying invested or starting a new position.
- The company’s model of recurring pet supplies and services may support more predictable earnings and cash generation, which is central to how much investors are prepared to pay for each dollar of profit.
- The analysts covering Chewy have run their own numbers. See what analysts think Chewy's shares could be worth.
The issue now is whether Chewy’s latest share price can be squared with what its earnings imply when set against the Fair Ratio benchmark.
If you are weighing whether Chewy’s earnings still justify today’s price, it can help to compare that question across a broader set of companies using 31 high quality undervalued stocks.
Is Chewy Getting Expensive on Earnings?
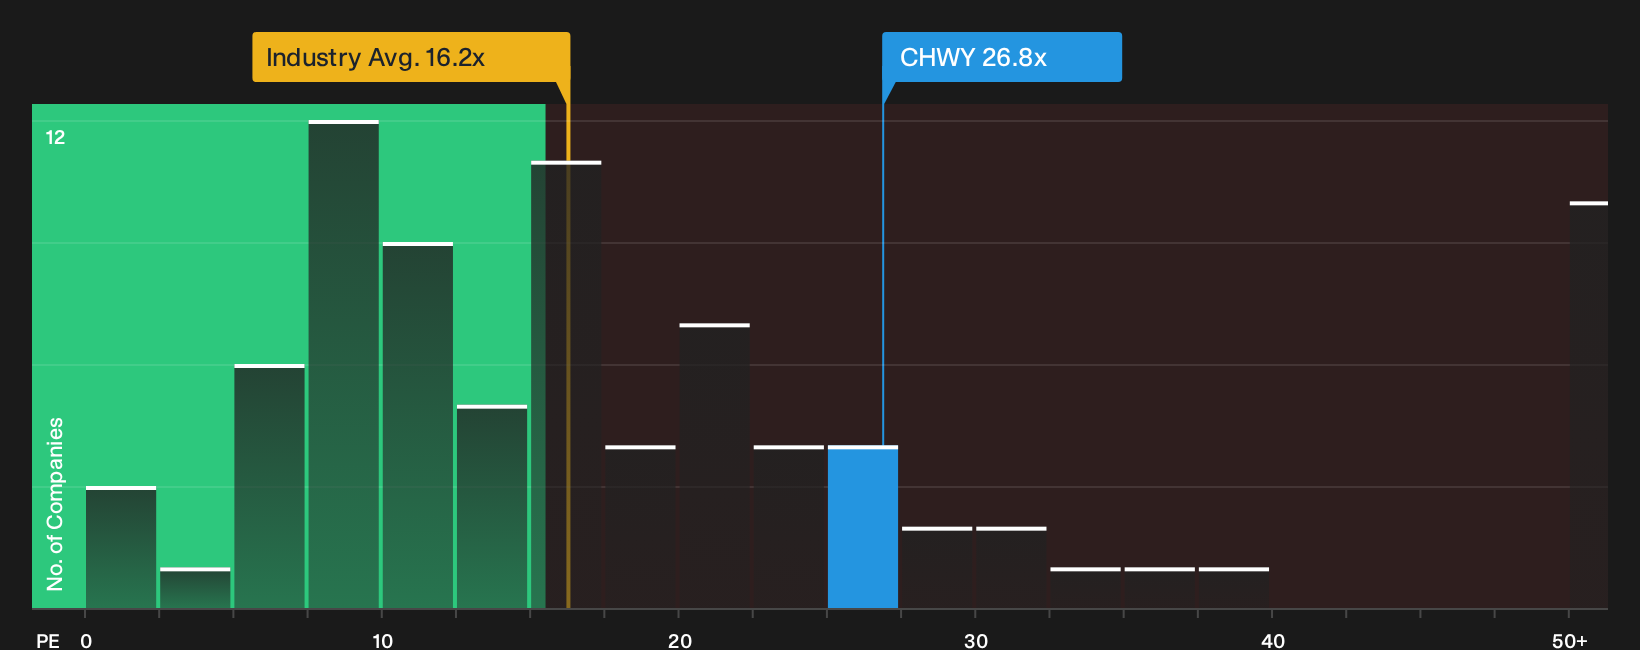
The P/E ratio works well for Chewy because the market tends to anchor on the earnings power of subscription like, repeat purchase models. Chewy trades on a P/E of 26.8x, while the broader Specialty Retail group averages about 16.2x and a peer set screens near 15.5x, so the ticker changes hands at a clear premium to both.
The Fair Ratio, which reflects what investors might usually pay for a business with Chewy’s mix of growth profile, margins, size and risk, sits below the current multiple, so the shares screen overvalued on this framework. That does not automatically make the stock untouchable; however, it does mean anyone buying in today is accepting a valuation that already prices in a healthy share of the company story. You would want to be comfortable that Chewy’s earnings quality and competitive position justify paying more per dollar of profit than the sector and peers. Explore the numbers behind Chewy's P/E valuation.
The Chewy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Chewy pick up directly from that valuation question and lay out what mix of future growth, profitability and earnings power would need to play out for the stock to be worth materially more or meaningfully less than today’s share price. They use a set of assumption driven views rather than a single multiple or model line so you can revisit those expectations against Chewy’s actual results over time on the Community page.
One of the top community narratives on Chewy: 37% undervalued
"The company's increased focus on innovation, such as the Chewy+ membership and mobile app improvements, is driving new customer acquisition and higher conversion rates..."
Discover why this Narrative puts Chewy at 37% undervalued.
The Chewy story is not complete without who is steering it
Price and earnings only tell you so much, because the next chapter for Chewy depends heavily on who is calling the shots and how their rewards line up with your interests. See who runs Chewy and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com