
Will Loan Mix Reset Change Flagstar Bank's (FLG) Narrative
- Flagstar Bank National Association has been reshaping its loan book and funding mix in response to recent interest rate cycles and rising Treasury yields, with the goal of widening net interest margins while operating under inflation pressures and competitive lending conditions.
- The shift away from weaker yielding assets toward higher spread commercial and industrial lending, along with efforts to refine funding costs, directly targets the profitability pressures reflected in Flagstar Financial’s historically low net interest margin and previously weaker earnings per share.
- We will now look at how Flagstar Bank’s loan and funding mix reset could reshape its investment narrative for long term investors.
See how Flagstar Bank National Association’s funding reset compares with peers by reviewing a curated list of list of solid balance sheet and fundamentals (24 results).
Flagstar Bank National Association Investment Narrative Recap
For a shareholder in Flagstar Bank National Association, the core belief is that the loan and funding reset eventually translates into a more resilient earnings profile. The big near term swing factor is whether the higher spread commercial and industrial book can offset still muted net interest margin and a history of weak earnings per share. The latest update on the funding mix mostly reinforces that this is a slow, operational grind rather than a sudden inflection.
The biggest near term risk sits in credit and funding discipline. Flagstar still carries a relatively high bad loan ratio of 4.6% and a low 31% allowance, so any credit shock or misstep on deposit pricing could pressure profitability again. The recent funding adjustments do not remove that risk; they just show management continuing to chip away at it.
There have been no major standalone corporate announcements tied directly to this reset, so the most relevant information comes from how Flagstar Bank National Association talks about its balance sheet repositioning. Management has highlighted nearly US$20b of wholesale funding reduction, a focus on relationship deposits, and the deliberate runoff of low coupon multifamily and commercial real estate loans.
Those actions matter because they sit next to the bank’s ambition for a higher spread commercial and industrial engine with a US$1.8b pipeline and quarterly commitments previously cited at US$2.4b. Execution on that rotation is the operational catalyst to watch. At the same time, the combination of high non performing loans and a modest 0.6% return on equity keeps credit quality and returns the key constraint for investors tracking the story.
Flagstar Bank National Association Forecasts and Implied Reset Expectations
Flagstar Bank National Association's narrative projects US$3.6b revenue and US$1.4b earnings by 2029. This projection is based on 21.9% yearly revenue growth and an earnings increase of roughly US$1.5b from a current loss of US$89.0m.
Discover why Flagstar Bank National Association's fair value indicates a 33% potential upside to its current price that could close more quickly than many investors expect.
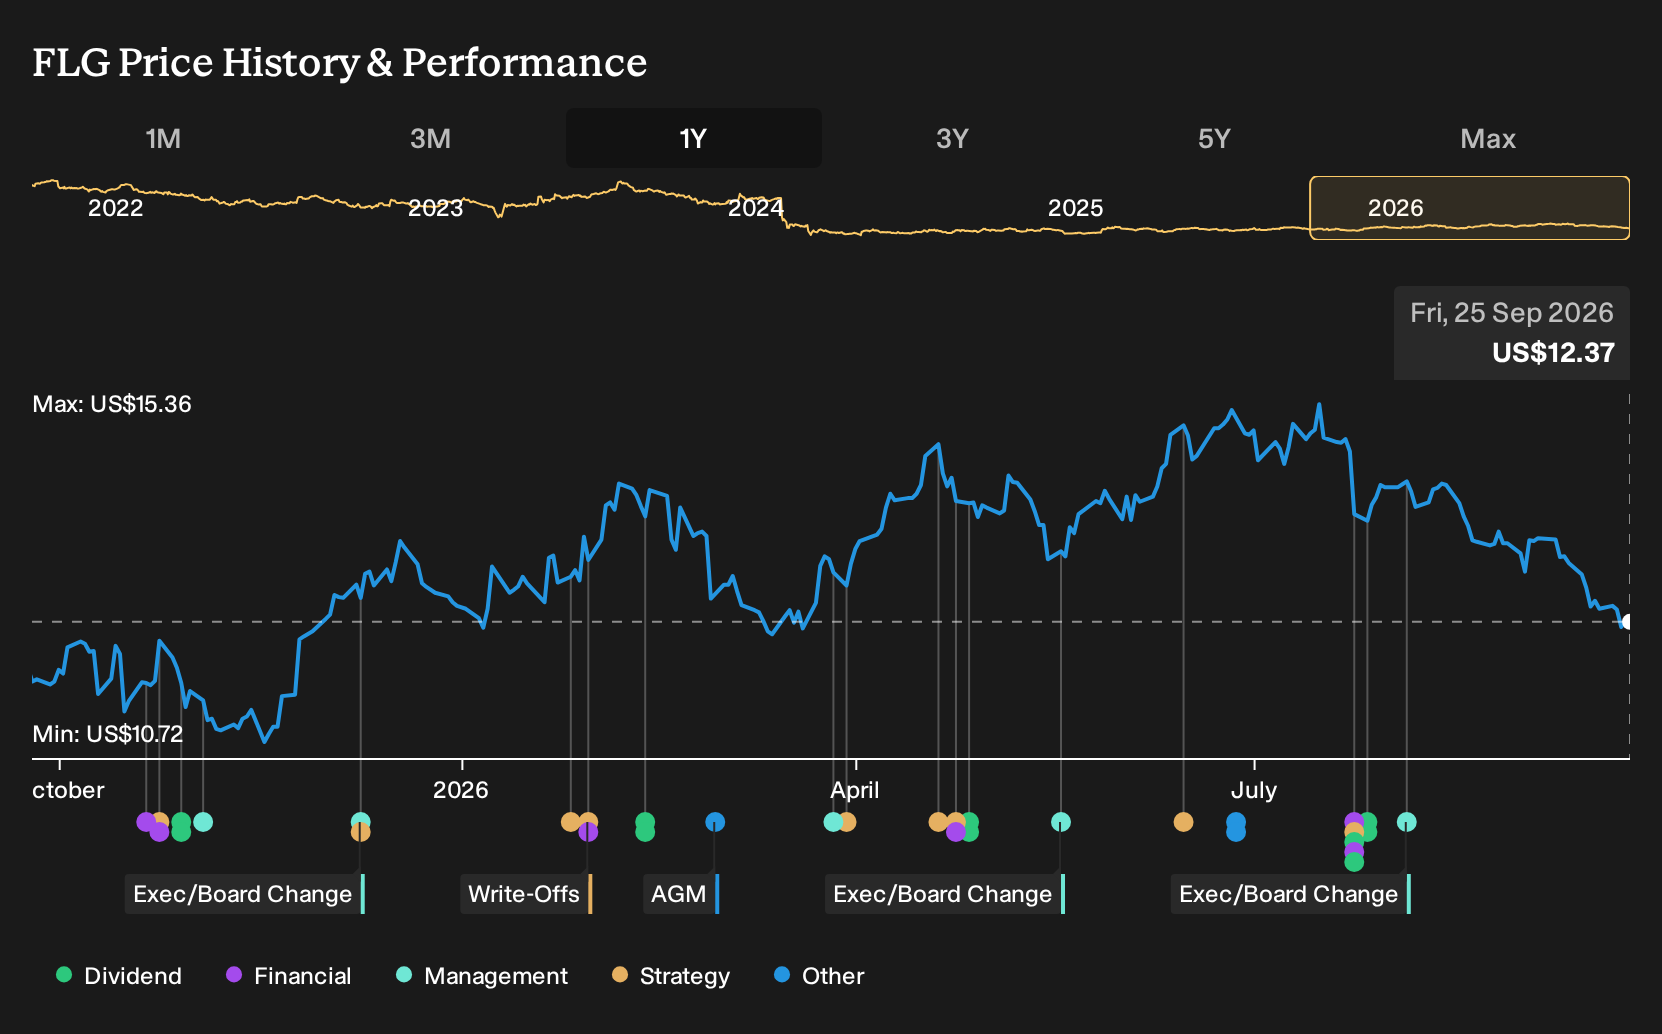
Exploring Other Perspectives
Fair value views on Flagstar Bank National Association from the Simply Wall St Community span roughly US$7.65 to US$16.47 across three separate estimates, so retail opinions already cover a wide valuation band. Set that against the ongoing loan book reshuffle and credit clean up, and you can see why opinions differ so sharply. Use these contrasting takes to pressure test your own thesis before acting.
Explore 2 other Flagstar Bank National Association fair value estimates, including one that suggests as much as 33% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Flagstar Bank National Association research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Flagstar Bank National Association. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Flagstar Bank National Association's overall financial health at a glance.
Looking for more Flagstar Bank National Association investment ideas?
If you want to cross check the Flagstar Bank National Association story against other opportunities, a quick pass through the Simply Wall St Screener can surface companies with different risk and income profiles that still match your style.
- If capital preservation and smoother ride potential matter most to you, start with a shortlist of 31 resilient stocks with low risk scores that score well on resilience.
- For investors who care about both value and balance sheet strength, compare Flagstar Bank National Association with a 31 high quality undervalued stocks that pair cash flow support with healthier fundamentals.
- If you want income on top of capital appreciation potential, scan a set of 8 dividend fortresses that focus on higher yields with sturdier payout profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com