
Veracyte (VCYT) Could Be 20% Undervalued After Fresh Decipher Study Spotlight
Veracyte (VCYT) drew fresh attention on 25 September 2026 after announcing that eight studies using its Decipher Prostate Genomic Classifier will appear at the 2026 ASTRO Annual Meeting, highlighting the test’s clinical applications.
Recent trading in Veracyte has been choppy, with the share price falling 6.41% over the past day but still up 14.16% on a 7 day basis and 7.17% year to date, even after a 24.90% decline over 90 days and a modest 2.57% 30 day share price gain. That near term volatility sits against a much stronger backdrop, as total shareholder return over the past year is 35.86% and the 3 year total shareholder return is 103.45%. This suggests long term holders have been rewarded even though the 5 year total shareholder return is slightly negative at 2.68% and recent news around the Decipher studies may be shifting how investors weigh growth potential against risk.
Scan other cancer diagnostics and genomics players showing similar momentum and research catalysts with the hand picked 38 healthcare AI stocks.
Veracyte looks like a solid cancer diagnostics business with active clinical data behind it, yet the recent share price swings raise a sharper question. Are investors now paying a fair price for that strength or stretching for it?
Most Popular Narrative: 20% Undervalued
On the most followed view of Veracyte, the narrative fair value of $56.55 sits above the last close at $45.43. This frames today’s volatility as investors debating whether the current price fully reflects the existing test portfolio and emerging pipeline.
Pipeline momentum with five major product launches and a pivotal clinical study (OPTIMA) completing in the next 18 months positions Veracyte to further diversify revenue, drive cross-selling, penetrate new markets (e.g., MRD in bladder cancer, Prosigna for breast cancer), and significantly expand addressable markets, supporting long-term topline acceleration.
See why 12 investors see Veracyte as 20% undervalued.
Result: Fair Value of $56.55 (UNDERVALUED)
Still, the bullish Veracyte narrative hinges on continued payer support for Afirma and Decipher, as well as on new tests avoiding delays in coverage or clinical adoption.
Find out about the key risks to this Veracyte narrative.
Another View on Veracyte’s Valuation
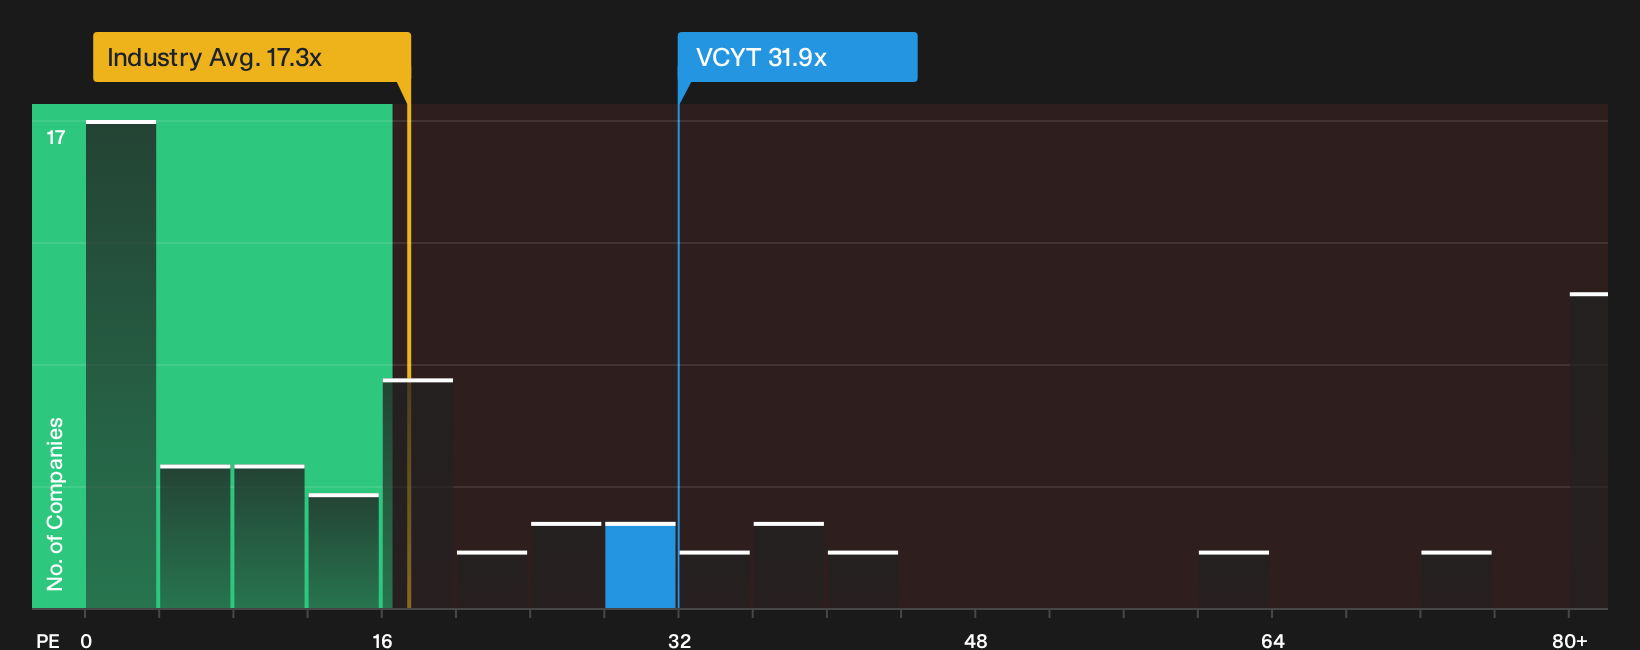
The story looks different when the focus shifts from fair value estimates to what the market is actually paying for Veracyte today. The stock trades on a P/E of 31.9x, while the fair ratio is 18.6x and the broader US Biotechs group trades around 17.3x.
That gap means buyers are accepting a much richer multiple than both the industry and the fair ratio suggest, even though Veracyte is described as trading 34.1% below an intrinsic value estimate. This raises the question of whether this is a mispriced opportunity or a sign that expectations already leave less room for error on execution.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of optimism threads through this Veracyte story, yet clear concerns also sit in the background. Move quickly, review the underlying data, and weigh both sides for yourself with 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Veracyte?
If the Veracyte story has your attention, broaden your watchlist with a few focused stock ideas that target different types of opportunity and risk.
- Target potential mispricings by reviewing companies that screen as high quality yet priced attractively through the 31 high quality undervalued stocks.
- Strengthen your defense by checking out businesses with robust finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for underfollowed opportunities by scanning a curated pool of stronger fundamentals with the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com