
Learn Why The Bull Case For Torex Gold Resources Stock Could Change Following Morelos Drilling Results
- Torex Gold Resources reported past drilling and exploration results from the Morelos Property, including high-grade intercepts along the San Miguel corridor, Media Luna, and ELG Underground that support its reserve growth and mine life extension strategy.
- The breadth of work, from resource conversion drilling at Media Luna and Media Luna North to early-stage programs at Atzcala and El Naranjo, indicates that the company is relying significantly on drilling activity to support future production planning and capital allocation at Morelos.
- The next step is to consider how Torex Gold Resources' investment narrative could be influenced by these San Miguel corridor drilling results.
Torex Gold Resources Investment Narrative Recap
To own Torex Gold Resources, you need to be comfortable with a single complex, the Morelos Complex in Mexico, driving essentially all activity. The recent San Miguel corridor and Media Luna drilling results feed directly into that story. They support the idea of reserve replacement and potential mine life extension, but they do not change the near term focus on stable execution and cost discipline.
The key short term swing factor is how smoothly Media Luna and ELG Underground continue to operate while new drilling is integrated into mine plans. The biggest risk remains cost and execution pressure during ongoing development, especially if all in sustaining costs stay elevated or infrastructure timelines slip.
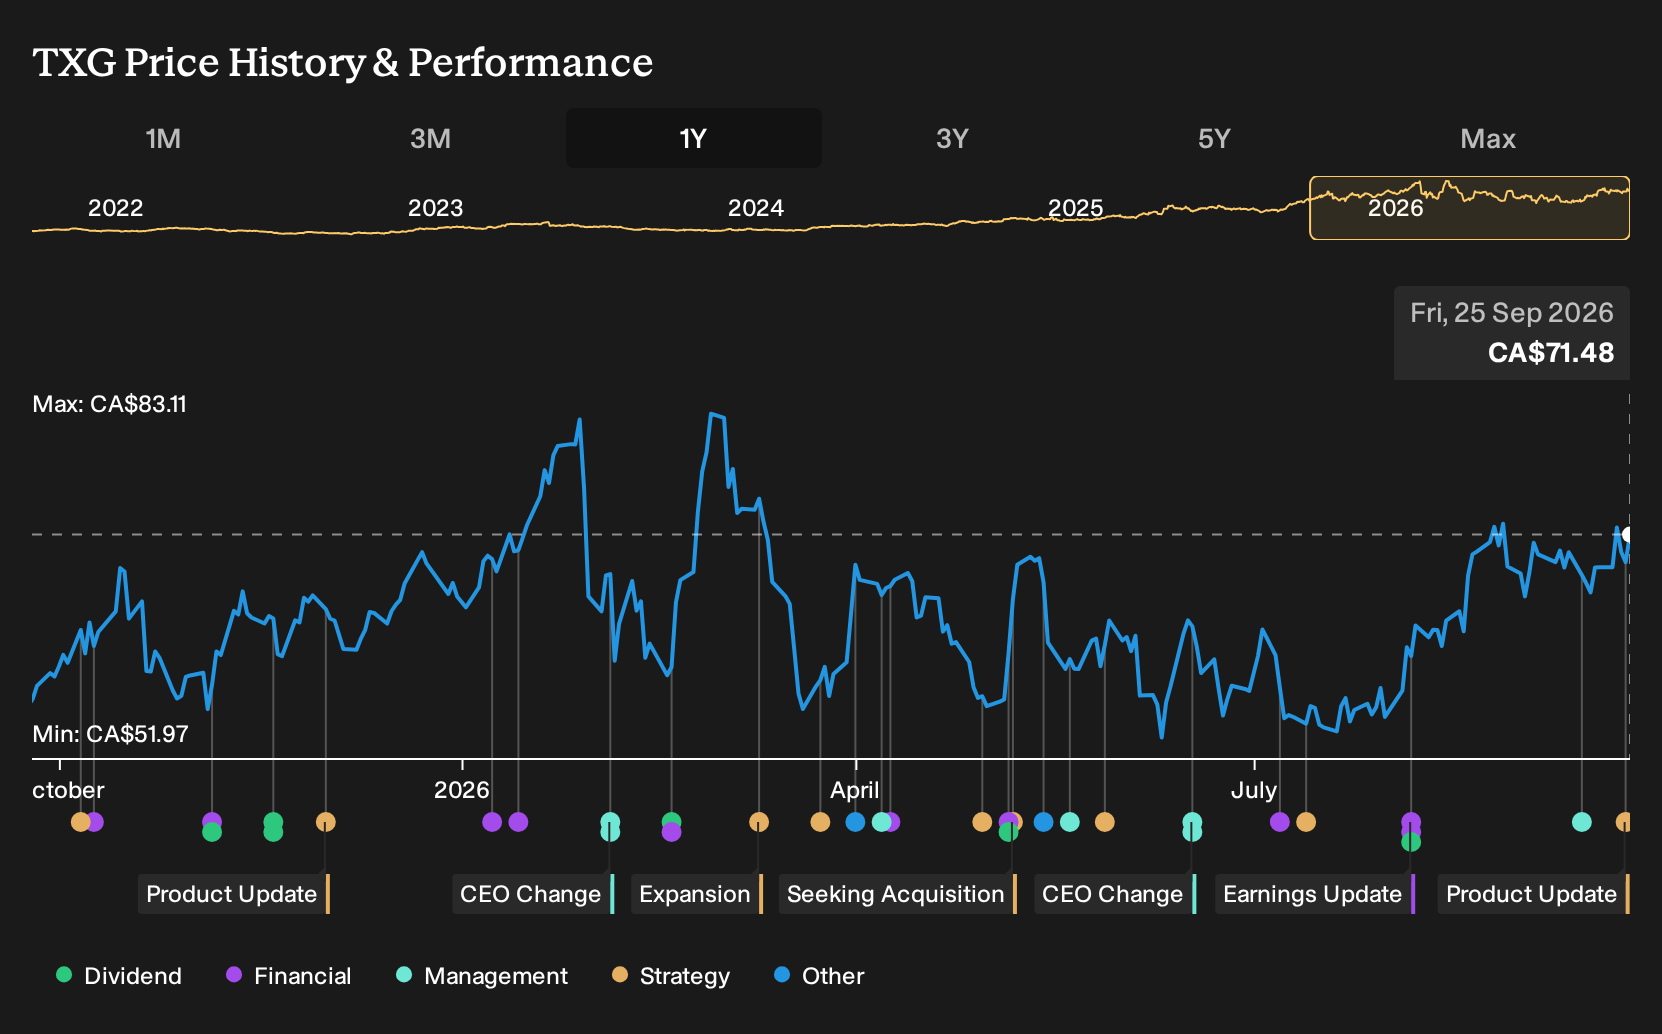
The latest Morelos drilling update matters most when set against Torex Gold Resources declaring commercial production at Media Luna in 2025 and reporting strong free cash flow with no debt and active buybacks in Q2 2026. In this context, you are looking at a miner that is already producing and is using ongoing drilling activity to help support its production profile.
That earlier step up to commercial production turned Media Luna from a project into a core operating asset. It now relies on programs such as the San Miguel corridor work and Media Luna North definition drilling to refine stope design and future scheduling. The same update sits alongside efforts to expand beyond Morelos through Los Reyes, which introduces new growth options but also adds jurisdictional and execution risk to weigh against these fresh Mexican drilling results.
Torex Gold Resources' current analyst narrative points to revenues of $2.2b and earnings of $712.5m by 2029, anchored on forecast revenue growth of 6.2% per year and an earnings increase of about $110m from today’s $602.5m base.
Uncover why Torex Gold Resources' fair value indicates a 23% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The Simply Wall St Community brings five fair value estimates on Torex Gold Resources that stretch from about CA$70.38 up to CA$98.63, so you are seeing a wide gap between the lowest and highest views. When you also consider the drilling update and execution risks around Media Luna, it becomes clear opinions can diverge sharply. Explore those competing narratives before firming up your own stance.
Explore 4 other Torex Gold Resources fair value estimates, including one that suggests it could be worth just CA$70.38.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Torex Gold Resources research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Torex Gold Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Torex Gold Resources' overall financial health at a glance.
Looking For More Investment Ideas Beyond Torex Gold Resources?
If Torex Gold Resources has sharpened your focus on quality and risk, broaden the search by using the Simply Wall St Screener to line up other candidates with traits that match your own goals.
- If you care most about quality businesses trading below what their financials suggest, start with 5 high quality undervalued stocks that already clear a high bar on fundamentals.
- If capital preservation and steadier risk profiles matter more to you than headline growth, filter for 8 resilient stocks with low risk scores that screen well on balance sheet strength and volatility metrics.
- If you like the idea of owning under-the-radar opportunities before they are widely discussed, scan through 9 high quality undiscovered gems that pair solid numbers with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com