
ALK-Abelló (CPSE:ALK B) Could Be 33% Undervalued As New EVP Appointment Lifts Interest
ALK-Abelló (CPSE:ALK B) drew investor attention after appointing Tina Abild Olesen as Executive Vice President for Corporate, Portfolio and Product Strategy, and shifting leadership responsibilities across its commercial and R&D functions.
Set against that reshuffle, ALK-Abelló’s 1-day share price return of 1.47% and 7-day gain of 0.60% sit in the context of a stock that has fallen 20.44% over 90 days and 5.00% over 30 days, while longer term total shareholder returns of 153.27% over three years and 50.95% over five years show a very different story. This suggests recent weakness contrasts with a strong multi year record.
Scan how ALK-Abelló compares with other healthcare names under pressure and spot potential rebound candidates in our hand picked 181 high quality undervalued stocks.
Analysts see ALK-Abelló well above today’s DKK199.70 price, yet one valuation model suggests only a slight discount. Is the market sensibly cautious after the pullback, or overlooking upside?
Most Popular Narrative: 33% Undervalued
Against ALK-Abelló’s last close of DKK199.70, the most followed narrative points to a fair value of DKK297.50, which frames recent share price weakness as a sizeable disconnect from its long term allergy immunotherapy thesis.
ALK's strong pipeline progress (for example, accelerating Phase II/III trials in peanut allergy and ongoing geographic expansion into Japan and China) leverages long-term trends in personalized and preventive medicine, increasing the likelihood of future product portfolio expansion, revenue diversification, and long-term earnings growth.
See why 21 investors see ALK-Abelló as 33% undervalued.
Result: Fair Value of DKK297.50 (UNDERVALUED)
Still, the ALK-Abelló narrative leans heavily on a concentrated allergy portfolio and smooth uptake of new launches. Slower adoption or competing therapies could quickly challenge that optimism.
Find out about the key risks to this ALK-Abelló narrative.
Another View On ALK-Abelló’s Valuation
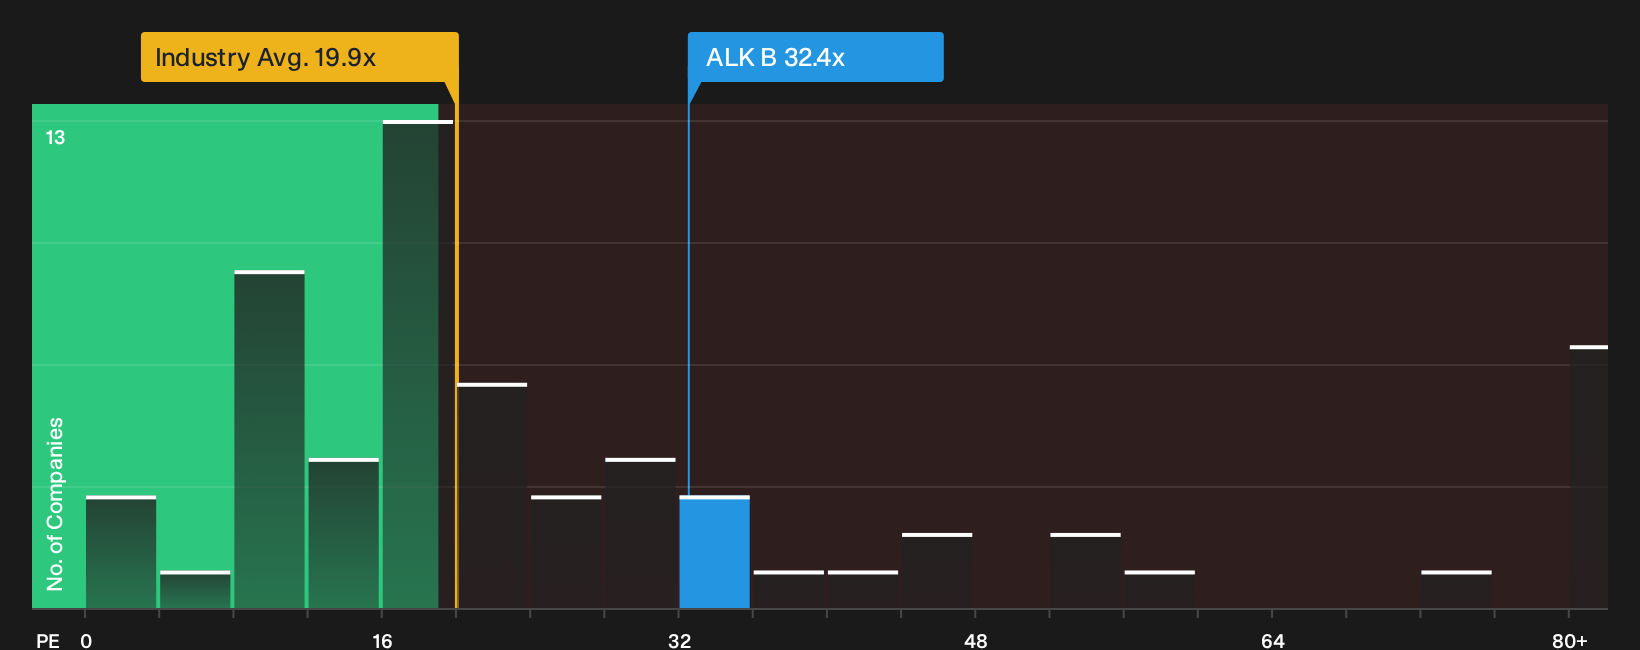
Analysts and the Simply Wall St fair value model see ALK-Abelló as undervalued around DKK297.50, yet the market is pricing the business on a rich P/E of 32.7x versus 19.9x for the wider European pharmaceuticals group and a fair ratio of 20.4x. That kind of gap suggests either a quality premium or valuation risk. Which side do you think it is?
To see how those earnings multiples stack up against detailed valuation work, review the breakdown in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Big valuation gaps can tempt or worry investors, so move quickly and stress test ALK-Abelló against your own assumptions by reviewing its 3 key rewards.
Looking for more ALK-Abelló investment ideas?
If ALK-Abelló has your attention, do not stop here. Broaden your watchlist with fresh ideas that match different risk levels and income goals.
- Target punchy upside potential by scanning specialist opportunities through the 129 elite penny stocks with strong financials.
- Strengthen your core holdings by filtering for companies with resilient finances using the list of solid balance sheet and fundamentals (202 results).
- Build reliable income streams by hunting for stocks that feature strong cash returns in the 162 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com