
Has Alcon (SWX:ALC) Fallen Enough To Look Less Expensive?
Alcon has seen its share price slip in recent years, which naturally puts the focus on whether today's valuation is still backed by its earnings power. For anyone tracking the stock, the question is how well the current market price reflects what the business is generating per share.
- The share price has fallen 26.8% over the past 5 years, which raises the issue of whether the earnings profile justifies where the stock now trades.
- The business model depends heavily on consistent demand for eye care products and the ability to convert that demand into stable margins, which can shape how reliable its earnings base looks to investors.
- Your read on Alcon is one view; the desks covering it have another. See what analysts think Alcon's shares could be worth.
The issue now is whether Alcon's current share price is appropriately aligned with the earnings that underpin it.
If you are weighing up whether Alcon's current valuation lines up with its earnings, it can help to benchmark it against a focused list of other companies using 181 high quality undervalued stocks.
Does Alcon Look Pricey on Earnings?
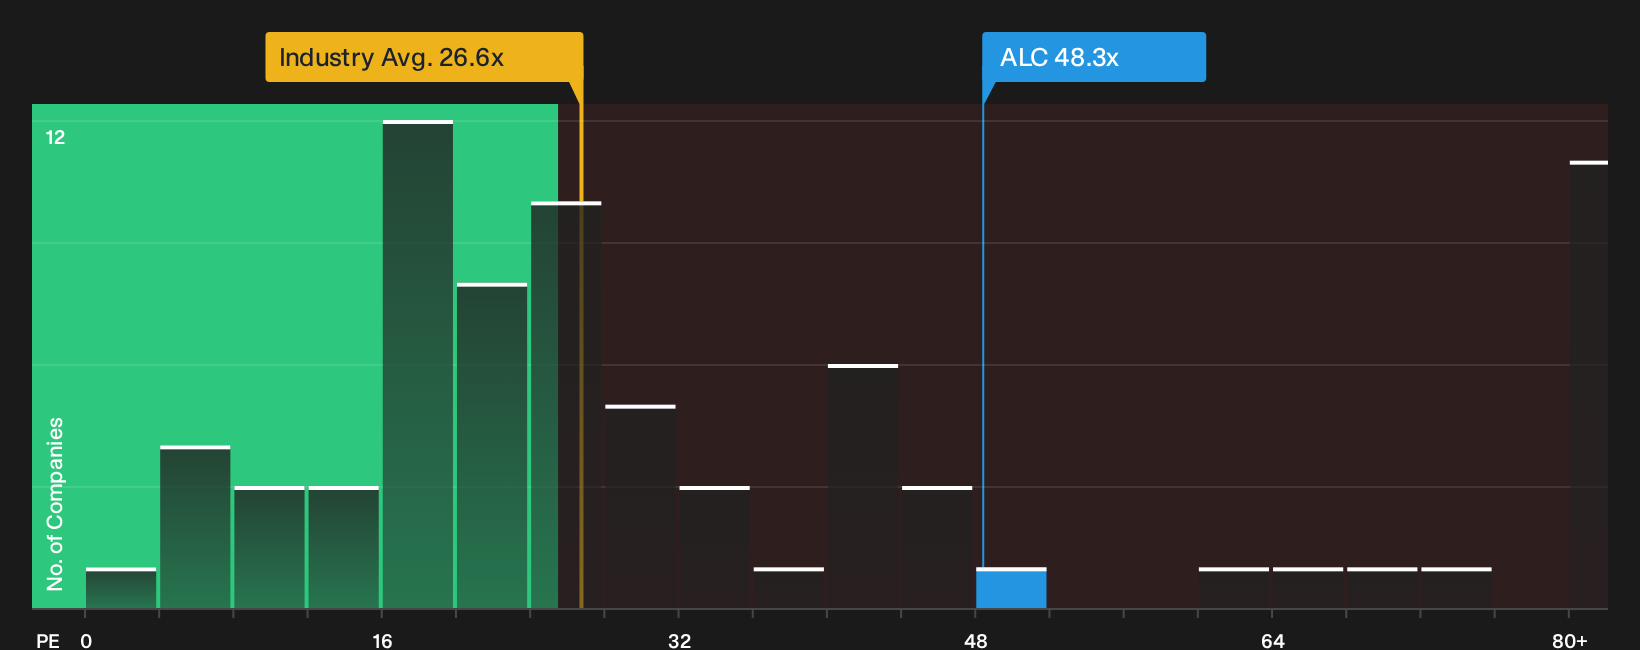
The P/E ratio works well for Alcon because earnings are a key lens for how investors usually price healthcare equipment businesses. On this metric, the stock trades on about 48.3x earnings, which is well above the Medical Equipment industry average of roughly 23.7x and also higher than the peer group at about 26.7x. That is a big gap for a company where investors are already paying a premium for each unit of profit.
The Fair Ratio, which reflects what you might expect given Alcon's sector, scale and risk profile, sits below the current P/E. This framework therefore points to the shares looking overvalued on earnings. For you as a shareholder or potential buyer, the key question is whether Alcon's earnings quality and business profile give enough comfort to justify paying almost double the sector multiple. Explore the numbers behind Alcon's P/E valuation.
The Alcon Narrative: What Would Justify Today's Price?
Alcon's current valuation raises a simple question for you as an investor: which future earnings story would need to play out for today's P/E to look either stretched or reasonable? Simply Wall St Narratives, found on the Community page, turn that question into clear scenarios about growth, margins and cash generation. Each narrative treats Alcon's fair value as a thesis you can track over time instead of a one off snapshot.
One of the top community narratives on Alcon: 28% undervalued
"Accelerated new product launches including Unity VCS, PanOptix Pro, Tryptyr and Precision7 provide significant near and medium term opportunities for share gain…"
Discover why this Narrative puts Alcon at 28% undervalued.
Before you move on Alcon still has questions to answer
Valuation only tells part of the story for Alcon, and the research checks also flag potential pressure points that might matter more to you than the headline multiple. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com