
Will Activist Push Change Knife River (KNF) Narrative
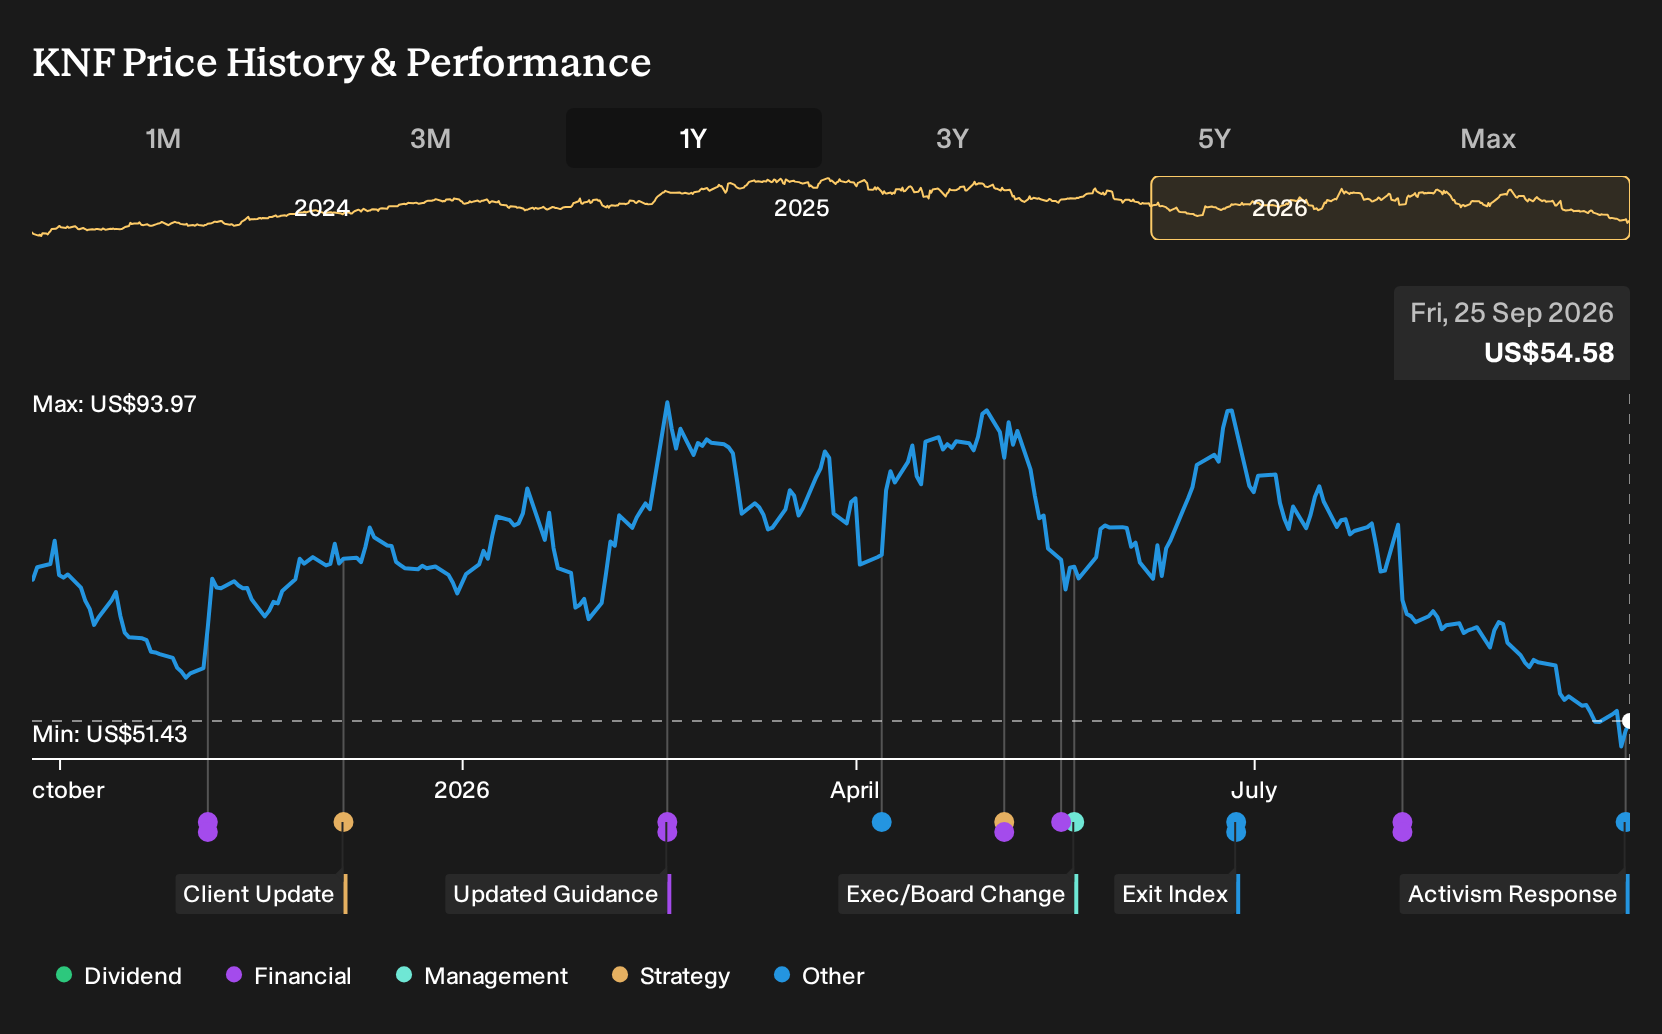
- Knife River said in September 2026 that it first learned of Starboard Value’s investment on September 22 and will engage with the activist to understand its views while continuing to pursue its existing EDGE initiatives and vertically integrated aggregates, concrete, asphalt, and contracting model.
- Starboard’s push for Knife River to consider strategic alternatives and deliver a clear EBITDA margin roadmap highlights underlying questions about execution, cost discipline, and how effectively the business is converting its infrastructure exposure into profitability.
- Attention now turns to how Knife River's existing investment narrative aligns or conflicts with Starboard's call for strategic alternatives and sharper margin targets.
Knife River Investment Narrative Recap
To own Knife River, you need to buy into a simple idea. A vertically integrated construction materials business with a large public infrastructure backlog can translate a steady flow of projects into better pricing, tighter execution, and healthier margins. The Starboard letter, and management’s response, put a spotlight on how quickly those margin ambitions show up in reported numbers.
In the short term, the key catalyst is whether Knife River can show visible progress on pricing and cost control while managing weather, Oregon funding uncertainty, and acquisition integration costs. The biggest risk is that higher trucking, labor, and energy costs, plus any project delays, keep margins soft and make the EBITDA debate feel justified.
The response Knife River issued on September 24 is the most relevant development here. Management reiterated confidence in its EDGE initiatives, which focus on pricing, operational performance, efficiencies, and margin expansion across aggregates, concrete, asphalt, and contracting. That framing matters because Starboard is effectively asking to see clearer, measurable delivery from these same levers.
For you as a shareholder, the question is execution speed. If EDGE and the vertically integrated model translate into steadier margins and better earnings conversion from the public DOT heavy backlog, that supports the existing investment case. If weather, funding delays, or integration costs keep chipping away at profitability, the risk is that activism intensifies and operational focus gets distracted.
What The Knife River Consensus Implies
Analysts are effectively sketching a roadmap for Knife River that depends on steady volume, firmer pricing, and tighter cost control turning today’s infrastructure exposure into higher profitability over time. Their models point to revenue growing at 5.6% a year for the next three years, with profit margins rising from 4.2% to 5.2% as current EDGE and integration efforts show through in the income statement. In addition, consensus calls for earnings to move from US$139.9 million today to US$201.2 million by 2029, while the more cautious forecasts sit closer to US$178.0 million.
That shift implies roughly a US$61.3 million step up in earnings to hit the US$201.2 million mark, which is a sizeable jump in absolute profit for a construction materials group that is still absorbing higher trucking, labor, and energy costs. To align that with the current analyst price targets, investors would also need to be comfortable with Knife River trading on a P/E of 31.4x those 2029 earnings, compared with 21.7x today and 18.7x for the wider US Basic Materials sector, while share count edges higher at a forecast 0.18% per year.
On the top line, the same consensus view anchors on Knife River reaching about US$3.9b of revenue by 2029 alongside the US$201.2 million earnings figure, using a 9.1% discount rate to translate those future numbers into a present value framework. That is the scaffolding behind the current Wall Street price target of US$85.38, bracketed by bullish and bearish ranges of US$118.0 and US$62.0 respectively, compared with a recent share price of US$53.37 on September 25, 2026.
Knife River's narrative projects revenues of about US$3.9b and earnings of US$201.2 million by 2029. This rests on 5.6% yearly revenue growth and an earnings increase of roughly US$61.3 million from current earnings of US$139.9 million.
Uncover why Knife River's fair value indicates a 56% potential upside to its current price before the market closes the valuation gap.
Exploring Other Perspectives
You can read Starboard’s activism as a test of the most optimistic Knife River narrative. The bullish analysts were sketching revenue around US$4.0b and earnings of US$264.9 million by 2029, well above the consensus path. Those estimates came before this letter, so some views may shift as the dialogue unfolds.
Explore another Knife River fair value estimate, including one that suggests there could be as much as 56% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Knife River research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Knife River. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Knife River's overall financial health at a glance.
Looking For More Investment Ideas Beyond Knife River?
If the Knife River story has sharpened your thinking about infrastructure, it can help to compare it with other opportunities that share some of the same financial traits. The Simply Wall St Screener lets you filter for the kind of balance sheet strength, income potential, or valuation profile that best matches your approach.
- If capital preservation comes first, focus on stability by scanning a basket of 30 resilient stocks with low risk scores that score well on resilience and risk controls.
- If income is a priority, aim for durability by reviewing a set of 8 dividend fortresses that pair higher yields with more robust fundamentals.
- If you want ideas that are not yet widely followed, broaden your watchlist through a curated group of 16 high quality undiscovered gems with stronger financial quality metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com