
How Walmart.com Launch Will Impact ADT (ADT) Investors
- ADT Inc. has expanded its ADT Blu DIY security system onto Walmart.com, adding to availability on ADT.com and giving customers contract free, self installed kits with app based controls and flexible professional or self monitoring options.
- This Walmart.com launch pushes ADT further into DIY security and could shift more business mix toward equipment sales and app centric engagement rather than technician led installs.
- We will now look at how ADT's investment narrative could be affected by ADT Blu's wider reach through Walmart's online channel.
ADT Investment Narrative Recap
To own ADT, you need to believe the business can shift more of its model toward app centric, smart home security while keeping churn in check and recurring monitoring revenue healthy. The Walmart.com launch supports that story by widening the funnel for ADT Blu and giving the firm another path to offset weaker dealer and affiliate activity.
The biggest near term watchpoint remains whether direct and DIY channels can compensate for softer bulk account purchases and any pressure on recurring monthly revenue. The key risk still sits with product reliability after prior ADT+ and ADT Blu issues, since any fresh missteps would hit brand trust and could slow adoption of higher value packages.
The Walmart.com listing for ADT Blu lines up directly with the existing catalyst around expanding the ADT+ and ADT Blu ecosystem and growing outright equipment sales. A broader retail shelf could help ADT push more self installed kits that feed into its ADT+ platform, which already accounts for roughly 30% of new customer additions.
For catalysts to matter, the operational follow through needs to be visible. That means smoother ADT+ and ADT Blu performance, clear evidence that DIY sales are supporting recurring monitoring revenue, and enough operating cash flow to handle higher cash taxes and interest that are expected from 2027. Without that, the current focus on free cash flow, deleveraging and capital returns becomes harder to sustain.
ADT's current analyst narrative points to revenues of US$5.6b and earnings of US$675.5m by 2029. These figures are built on an assumed 2.8% yearly rise in revenue and an earnings increase of about US$61.3m from US$614.2m today.
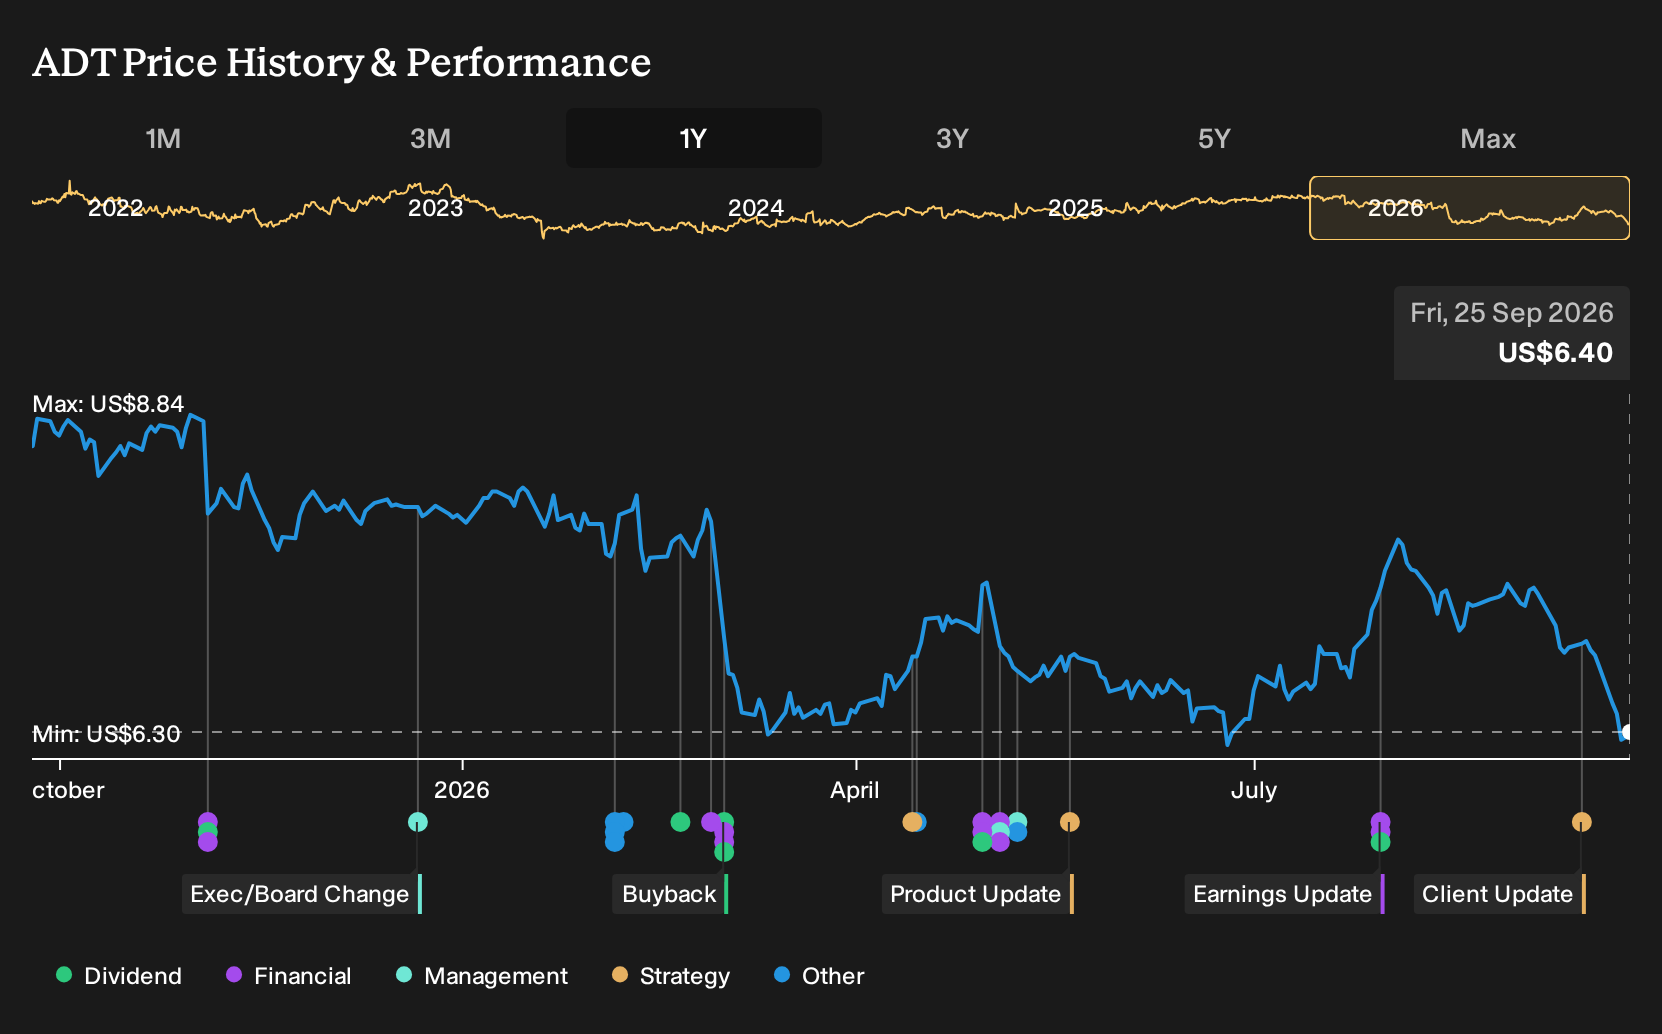
Uncover why ADT's fair value indicates a 29% potential upside to its current price, a gap that could narrow quickly once ADT's story gains traction.
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community range from US$8.21 to US$25.27 per share, indicating that private investors are not aligned on where ADT should trade. Those views do not yet reflect the Walmart.com rollout of ADT Blu, which could reshape expectations for app based DIY traction and future cash generation. Readers should treat this as a prompt to review several competing viewpoints rather than rely on any single forecast.
Explore 4 other ADT fair value estimates, including one that suggests as much as 295% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Consider your own analysis and judgment.
- A great starting point for your ADT research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ADT. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ADT's overall financial health at a glance.
Looking For More Investment Ideas Beyond ADT?
If the ADT story has sharpened your interest in security, cash flow and balance sheet strength, it can help to compare it with a wider set of businesses. The Simply Wall St Screener lets you filter by quality, valuation, income and risk so you can build a watchlist that fits your own approach.
- For investors hunting for mispriced quality, check out a curated group of companies that may trade below their fundamentals by scanning 31 high quality undervalued stocks.
- If steady income matters to you, focus on cash generating businesses with meaningful yields by reviewing our hand picked 8 dividend fortresses.
- For a focus on resilience, concentrate on companies with stronger finances and lower risk profiles by running our 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com