
Veidekke (OB:VEI) Just Gave The Market Something To Think About
Veidekke (OB:VEI) just added two fresh residential contracts to its pipeline: a NOK 190 million Bryggebyen phase in Arendal and a SEK 98 million Cederhuset build in Mölndal, both feeding into its Q3 2026 order backlog.
These fresh contracts arrive as Veidekke’s share price has increased, with a 30-day share price return of 5.34% and a year-to-date share price gain of 23.86%, alongside a 1-year total shareholder return of 46.12%.
Scan how Veidekke’s latest contract wins compare with other construction and infrastructure players by checking out our curated list of list of solid balance sheet and fundamentals (202 results)
Veidekke’s sharp 1-year total return and fresh housing contracts point to either a business quietly compounding its order book, or a market leaning harder into optimism. The valuation tells you which story you are really buying into.
Preferred P/E of 17.4x on Veidekke: Is it justified?
Valuation on Veidekke is being set by a P/E of 17.4x at a last close of NOK217, which is higher than both its peers and an internally estimated fair multiple. This indicates that the market is paying a premium for its earnings today.
The P/E ratio compares the current share price with earnings per share and helps you see how much investors are willing to pay for each unit of profit. For a construction and infrastructure group like Veidekke, this matters because earnings can be cyclical, and investors often adjust what they are willing to pay depending on contract visibility, order books and perceived earnings quality.
Veidekke is described as expensive on a P/E basis compared with both the European construction industry average of 15.5x and the peer average of 15.5x. The same assessment classifies the stock as pricey relative to an estimated fair P/E of 15.8x. This implies the current multiple is above a level the market could move towards if sentiment cools or earnings growth does not keep pace with expectations.
Explore the SWS fair ratio for Veidekke.
Result: Price-to-Earnings of 17.4x (OVERVALUED)
Still, Veidekke faces real pressure if construction demand slows or public infrastructure tenders get delayed, which could test both earnings quality and that premium P/E multiple.
Find out about the key risks to this Veidekke narrative.
Another view on Veidekke’s value
The P/E picture paints Veidekke as expensive, yet the SWS DCF model points in the other direction. At NOK217, the stock is described as trading below an estimated future cash flow value of NOK228.66, which frames today’s premium multiple as a potential entry point rather than a warning sign. Which lens do you trust more?
Look into how the SWS DCF model arrives at its fair value.
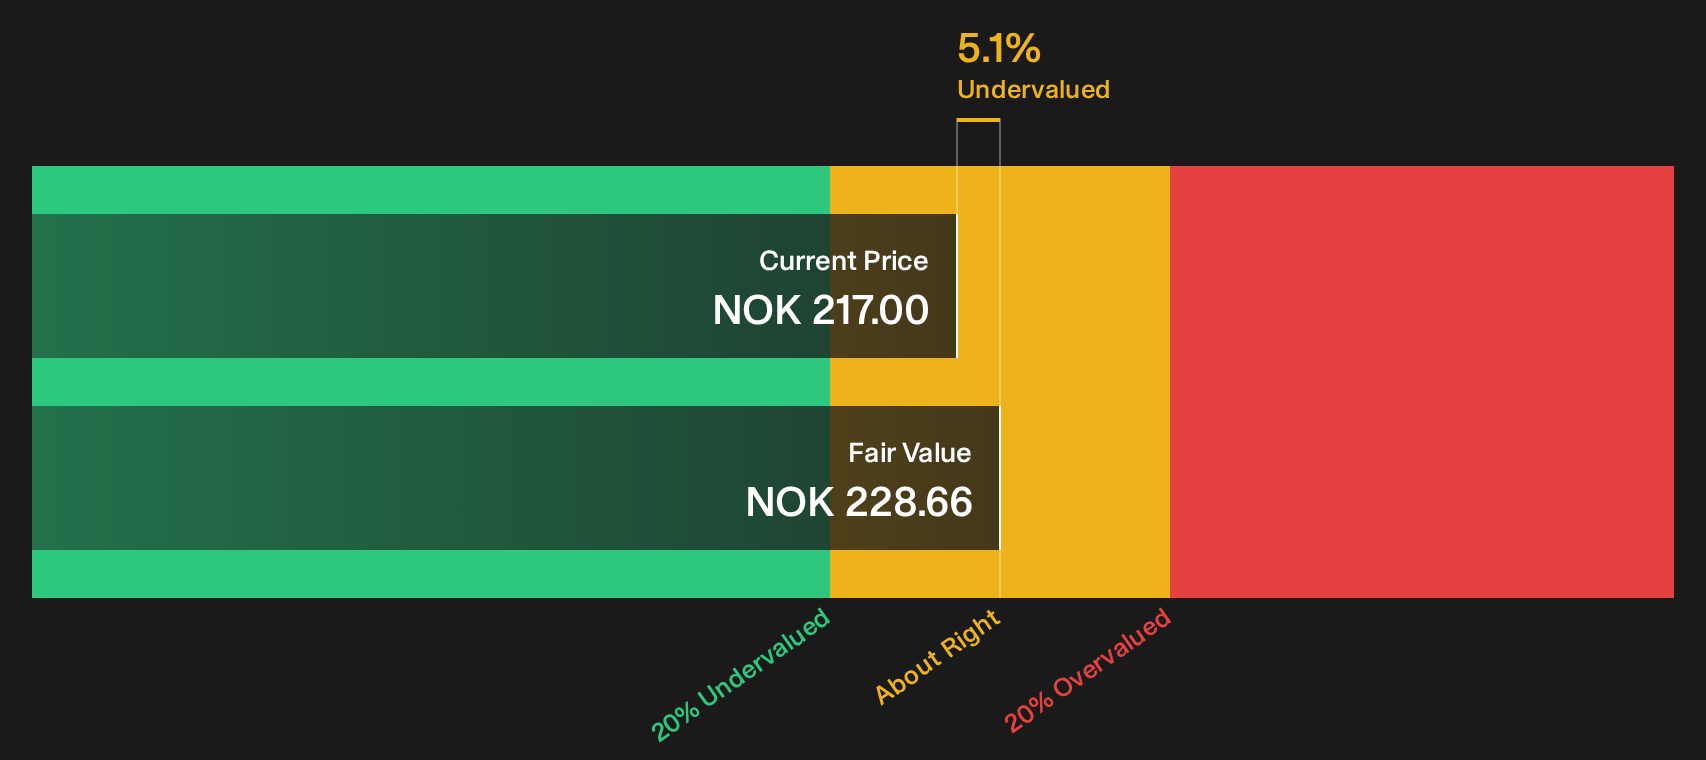
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Veidekke for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 181 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or clear opportunity for Veidekke? You will only know once you have seen the full picture yourself. Act quickly and weigh both sides by checking the 3 key rewards and 1 important warning sign
Ready for more ideas beyond Veidekke?
Once you have weighed Veidekke, do not stop there. Fresh opportunities often appear where strong balance sheets, steady dividends and overlooked quality quietly sit.
- Target resilient compounding potential by scanning a curated 162 dividend fortresses that focuses on income strength rather than headline stories.
- Hunt for mispriced quality by reviewing a hand picked 620 high quality undiscovered gems that screens for fundamentals the crowd has not focused on yet.
- Guard against downside risk by filtering a broad universe through the 228 resilient stocks with low risk scores so you only spend time on sturdier candidates.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com