
Workday (WDAY) Launches Total Benefits, Is The Discount Too Good To Ignore?
Workday (WDAY) is back in the spotlight after launching its AI driven Workday Total Benefits platform, which ties together benefits, payroll links and financial services through partners like Experian, Checkr and Block’s Cash App.
Investors have already reacted to the Workday Total Benefits reveal and a series of new partnerships, with a 90 day share price return of 52.52% pointing to renewed momentum, even as the year to date share price return is down 7.94% and the 1 year total shareholder return has declined 23.20%.
Scan how Workday’s AI push compares to other software players leaning into automation by reviewing a curated set of 37 profitable AI stocks that aren't just burning cash.
Workday now trades at a double discount, both to analyst targets and to one intrinsic value estimate, after a sharp 90 day rebound. Is that gap a market mispricing, or a warning that caution is warranted?
Most Popular Narrative: 65.6% Undervalued
According to one widely followed valuation narrative, Workday’s shares at $189.45 trade at a steep markdown to an estimated fair value of $550.10, and that gap is being framed around how the business converts backlog, cash flow and AI adoption into long term earnings power.
The core thesis is simple: three independent data sources, contracted backlog, realized free cash flow, and forward guidance, all moved in the same direction this quarter. That kind of triangulated confirmation is harder to dismiss than any single metric on its own. The market's repeated negative reaction to Workday's earnings, even on beats, suggests a sentiment-driven mispricing rather than one grounded in this quarter's actual disclosures.
See why 15 investors see Workday as 66% undervalued.
Result: Fair Value of $550.10 (UNDERVALUED)
Still, the Workday narrative can crack if AI agent uptake slows or if subscription backlog growth drops toward the low double digits and remains at that level.
Find out about the key risks to this Workday narrative.
Another View: What Workday’s P/E Is Telling You
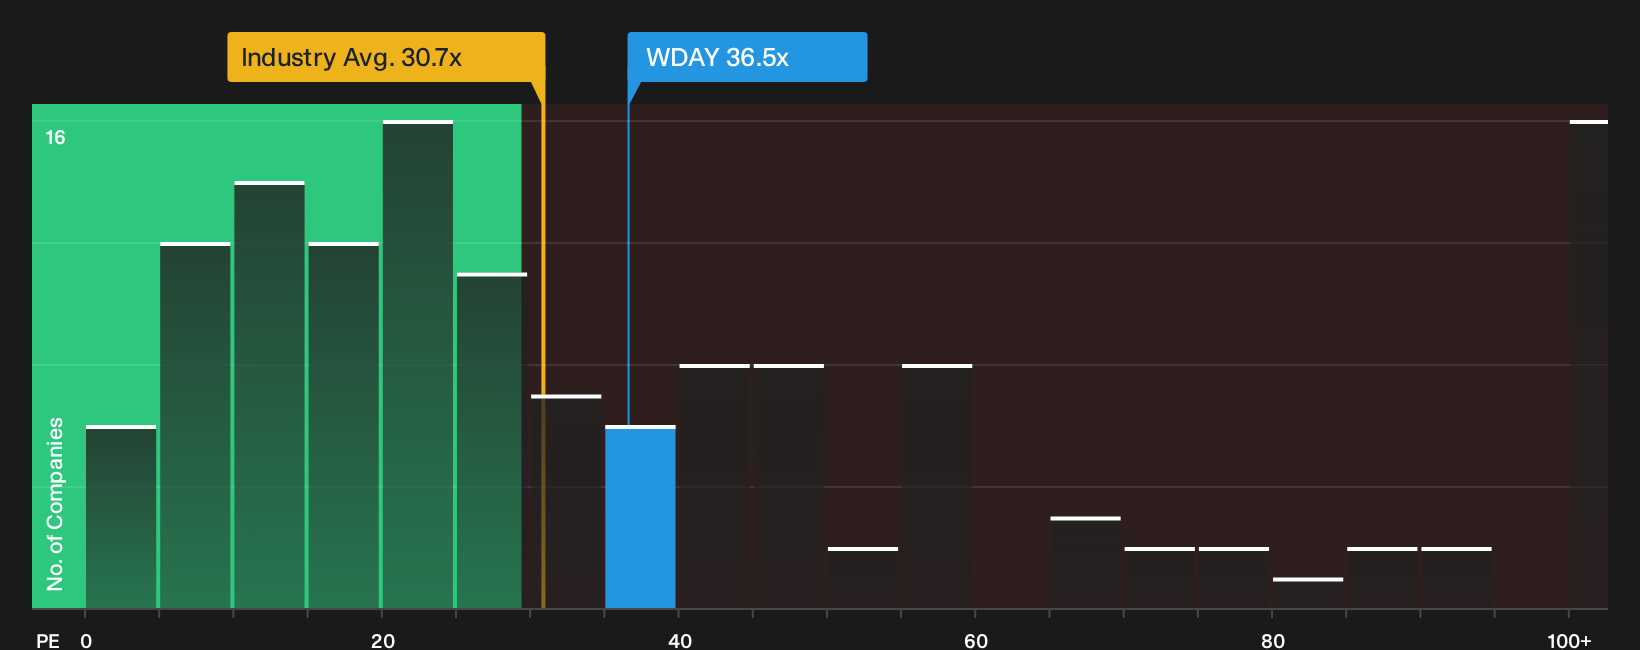
Workday may look inexpensive against one intrinsic value estimate, yet the P/E story points in a different direction. The stock trades on 36.5x earnings, compared with 30x for the wider US Software group and a fair ratio of 38.6x based on our model. That leaves a narrow margin between opportunity and overpaying if sentiment turns.
To see how that earnings multiple could adjust over time, and what it might mean for future pricing power, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed sentiment around Workday can be a useful signal if you are willing to look under the hood yourself and move early. To see which rewards analysts are most optimistic about, review the 3 key rewards.
Looking for more investment ideas beyond Workday?
If you want a broader view of where capital could work harder, use the Simply Wall Street Screener to spot other opportunities before they move without you.
- Target resilience in choppy markets by focusing on companies with robust finances and clean balance sheets through a list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced quality by zeroing in on businesses that combine strong fundamentals with appealing entry prices using a 31 high quality undervalued stocks.
- Build a cash flow focused portfolio by scanning for income ideas that aim for higher yields and staying power via a 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com