
Ezaki Glico (TSE:2206) Could Be 46% Below Fair Value Following Viome Partnership
Ezaki Glico (TSE:2206) entered the personalized health space on 14 September 2026 by partnering with Viome Life Sciences on mRNA HEALTH TRACKER, a gut microbiome service that links RNA analysis to tailored nutrition advice.
Against that backdrop, Ezaki Glico’s share price has moved to ¥5,050, with a 1-day share price return of 0.70% and a 7-day share price return of 0.24%. The 90-day share price return is down 7.63% and the 1-year total shareholder return is down 2.79%, pointing to softer recent momentum. This contrasts with a 3-year total shareholder return of 30.27% and a 5-year total shareholder return of 34.71%, which indicate a materially stronger longer-term record.
Scan beyond Ezaki Glico and identify other health focused consumer stocks targeting personalized nutrition with our curated 10 healthcare AI stocks list.
Ezaki Glico is pushing into higher margin health services while its share price has drifted over recent months. Strong story, softer momentum. Does that combination add up to a compelling valuation today or not?
Price-to-Earnings of 48.7x: Is it justified?
On simple headline numbers, Ezaki Glico trades on a P/E of 48.7x, which is a rich tag when set against a share price of ¥5,050 and recent share price softness.
The P/E ratio compares what you pay today for each unit of current earnings. For a consumer foods and health focused group like Ezaki Glico, a higher P/E often signals that investors are paying up for expected profit expansion rather than what the business is earning right now.
Forecasts point to earnings growth of 23.68% per year and revenue growth of 2.2% per year, alongside an expected Return on Equity of 4.5%. That combination points to stronger projected profit growth than top line progress, yet with a relatively low forecast return on equity and a current ROE of 2.3%. The current P/E of 48.7x is also well above an estimated fair P/E of 28.9x, a level the market could move toward if enthusiasm for the earnings outlook cools.
Against local peers, the contrast is even sharper. Ezaki Glico’s P/E of 48.7x is roughly three times the JP Food industry average of 16.6x and more than double the peer average of 20.3x, which signals the market is pricing in a much stronger earnings profile than sector and peer benchmarks.
Explore the SWS fair ratio for Ezaki Glico.
Result: Price-to-Earnings of 48.7x (OVERVALUED)
Still, Ezaki Glico faces clear risks if analyst targets at ¥3,900 influence sentiment or if projected earnings and revenue expansion fail to materialise as expected.
Find out about the key risks to this Ezaki Glico narrative.
Another View on Ezaki Glico’s Value
The P/E screen paints Ezaki Glico as expensive, yet the SWS DCF model tells a very different story. On that framework, the share price of ¥5,050 sits well below an estimated future cash flow value of ¥9,332.28, which points to the stock trading at a sizeable discount. Which lens should you trust more when both rely on different expectations about how profits compound over time?
Look into how the SWS DCF model arrives at its fair value.
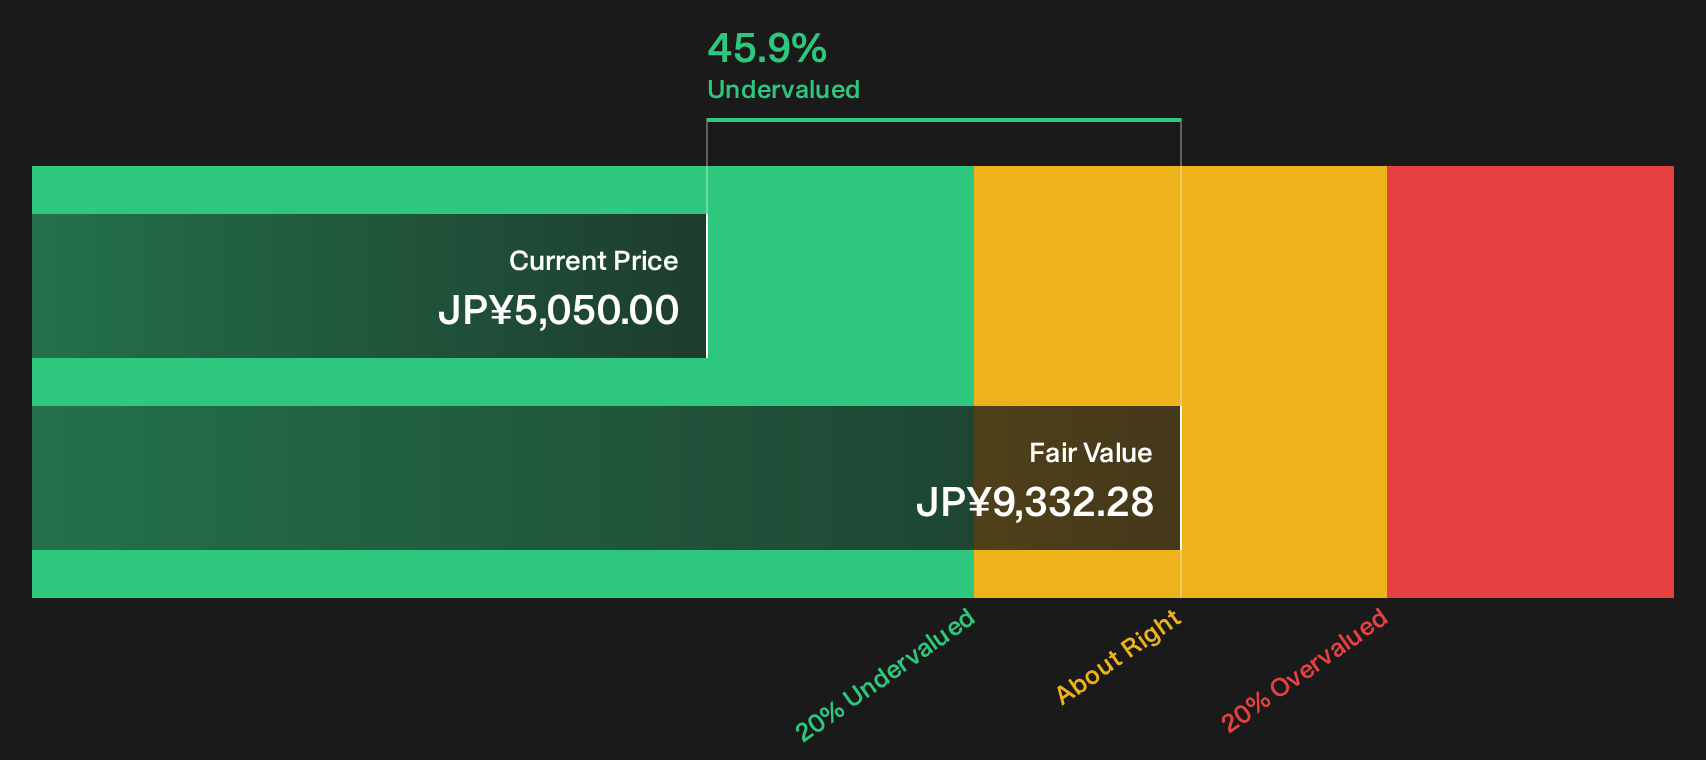
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ezaki Glico for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Ezaki Glico so far, with rich valuation metrics but also some clear positives in the story, mean you should move quickly and consider the trade off for yourself. To see both sides set out clearly, review the 2 key rewards and 3 important warning signs
Looking for more Ezaki Glico investment ideas?
If Ezaki Glico has caught your attention, now is the moment to widen your watchlist and spot other opportunities before the crowd focuses on them.
- Target quality at a discount by scanning companies that score well on fundamentals and valuation with our 18 high quality undervalued stocks.
- Put resilience first and narrow in on businesses with sturdier finances using the 21 resilient stocks with low risk scores.
- Hunt for underfollowed opportunities before they become crowded trades with the 74 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com