
Qualys Stock Faces An AI Test As Demand Growth Questions Persist
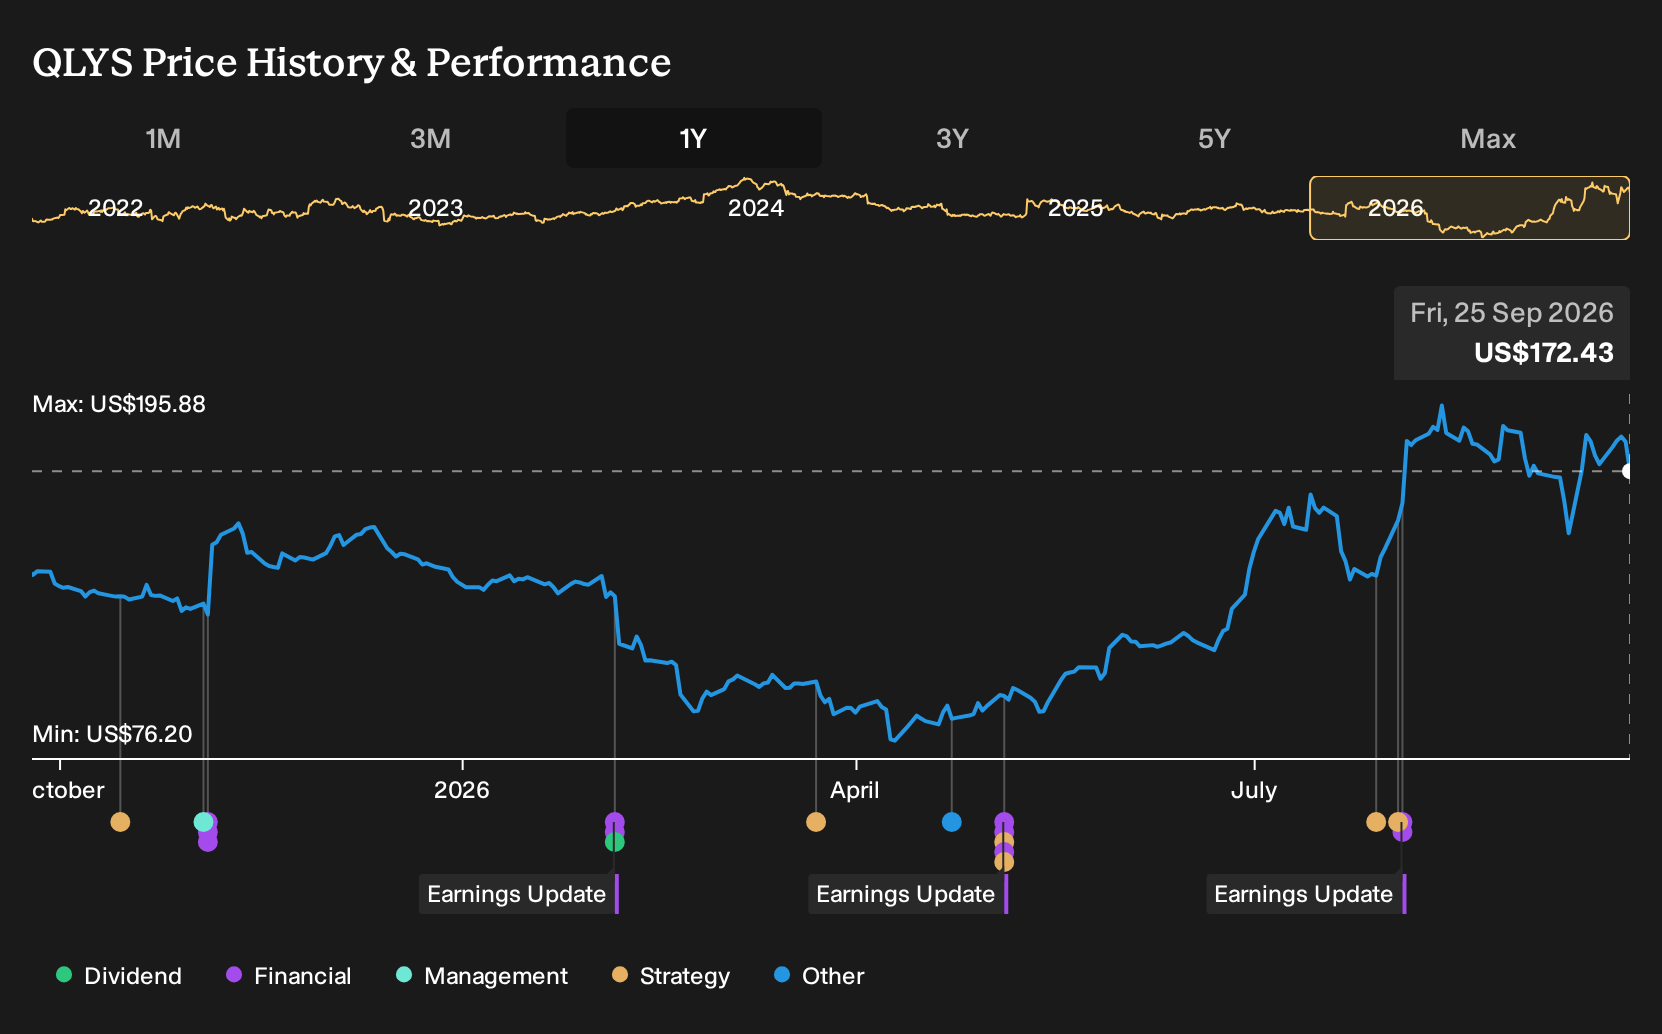
- Qualys is in the spotlight as its valuation is debated against discounted cash flow estimates, while the business contends with softer ARR trends and pressure around long term contracts and renewals.
- The launch of Qualys' cloud-native risk operations center and Agentic AI platform highlights a push to deepen pre breach risk management, despite concerns over near term demand.
- Investors are watching how Qualys' investment narrative is affected by softer ARR growth alongside its push into Agentic AI capabilities.
Scan beyond Qualys and compare how other security and AI focused platforms are priced against their fundamentals with our curated list of 31 high quality undervalued stocks.
Qualys Investment Narrative Recap
To own Qualys, you need to be comfortable with a story that pairs strong profitability with uneven demand. The business generates high margins and solid earnings, but softer ARR trends and pressure on long term contracts keep near term growth uncertain. The key short term catalyst is whether its newer risk and AI offerings can offset that softness. The biggest risk is that customers consolidate onto broader security suites faster than Qualys can deepen its own platform footprint.
Recent volatility around valuation does not materially change that near term setup. The debate over discounted cash flow value versus share price mostly affects how patient investors feel about waiting for execution. What really moves the needle over the next few quarters is whether renewals stabilize, Flex pricing beds down without hurting unit usage, and new bookings stop lagging in what management has already called a challenging environment for new business growth.
The launch of Qualys’ cloud native risk operations center and Agentic AI platform ties most directly into that catalyst story. If customers lean into these tools for pre breach risk management across both Qualys and non Qualys data, the platform could deepen its role inside existing accounts and help support higher average revenue per customer over time.
That opportunity comes with clear execution risks. AI security evolves quickly, so any lag in product quality or automation could see enterprises favor larger suites or more specialized rivals. For you as a shareholder, the question is whether Qualys can keep ROC and Agentic AI technically competitive while managing spending, converting its sales investments into pipeline, and proving that these launches offset the current drag from softer ARR and contract pressure.
Qualys' current analyst narrative points to revenues of $870.3 million and earnings of $225.2 million by 2029, built on 7.4% yearly revenue growth and an earnings increase of about $18.7 million from $206.5 million today.
Uncover why Qualys' fair value is essentially in line with its current price.
Exploring Other Perspectives
One alternate view puts consolidation risk front and center. The lowest analysts worry that embedded cloud security from hyperscalers could squeeze Qualys, with their pre news models pointing to about $865.7 million of revenue and $202.7 million of earnings by 2029. That is a much harsher setup. Use it as a prompt to compare several narratives and decide which assumptions feel more realistic, especially now that fresh news may change the story.
Explore 2 other Qualys fair value estimates, including one that suggests it could be worth just $171.74.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Qualys research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Qualys. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Qualys' overall financial health at a glance.
Looking For More Investment Ideas Beyond Qualys?
Once you have formed a view on Qualys, it can help to widen the lens and compare it with other opportunities that fit different portfolio roles, from growth to resilience to income.
- For investors hunting for earlier stage potential with strict financial filters, narrow your search to a focused set of 8 elite penny stocks with strong financials that already show stronger balance sheets and fundamentals than most peers.
- If you want to concentrate on quality at a reasonable price, use our valuation filters to surface a curated batch of 16 high quality undiscovered gems that combine solid fundamentals with relatively low market attention.
- If you prefer to keep risk in check and prioritise resilience, start with a pre filtered universe of 30 resilient stocks with low risk scores that aim to balance stability with meaningful return potential.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com