
Earnings Beat Might Change The Case For Investing In Salesforce Stock (CRM)
- Salesforce reported strong second quarter fiscal 2027 results, raised its full year revenue and non GAAP earnings guidance, and highlighted growing adoption of AI driven products like Slack, Agentforce, and Informatica, supported by solid cash generation and ongoing capital returns.
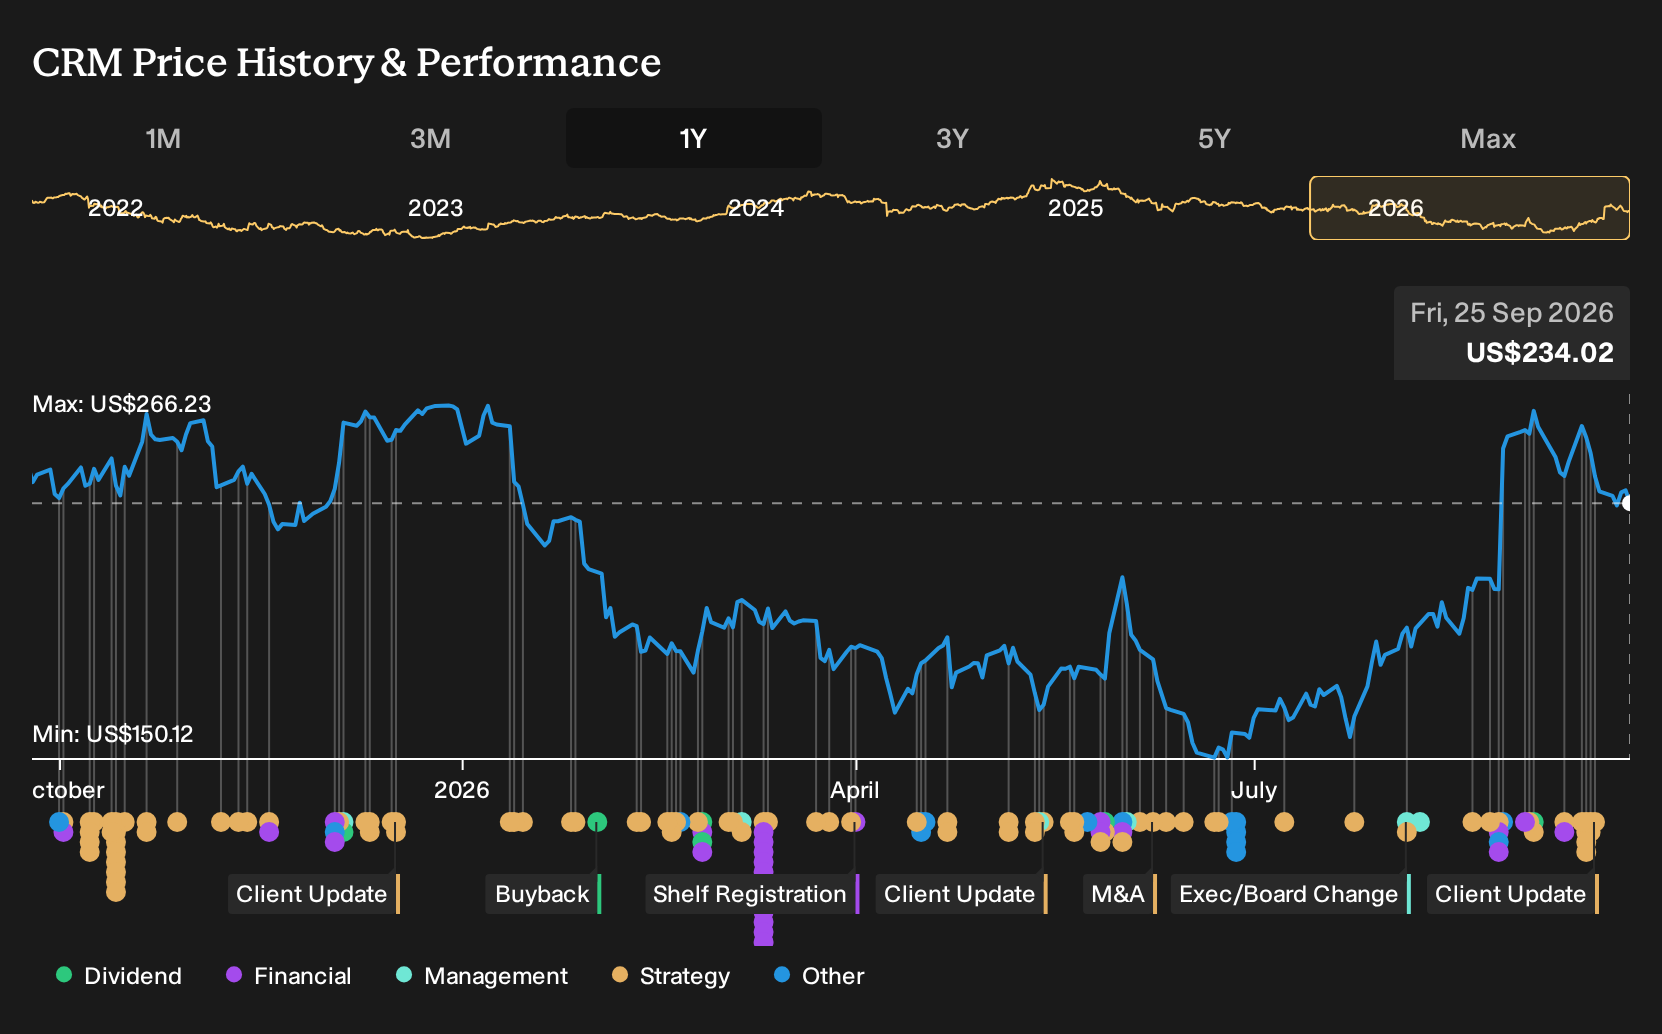
- The rebound in broader software stocks, together with Salesforce’s AI focused product momentum and investment gains, points to investors reassessing the durability of its CRM and AI platform as enterprises keep prioritizing data rich, workflow centric tools.
- We will now look at how Salesforce’s updated guidance and AI product traction reshape the investment narrative investors have been using.
Scan how Salesforce’s AI story compares with other platforms moving fast in enterprise automation by reviewing a curated list of 37 profitable AI stocks that aren't just burning cash that already turn AI demand into real earnings power.
Salesforce Investment Narrative Recap
To own Salesforce, you need to believe its bet on AI agents, Data 360, and cross cloud workflows keeps customers deeply tied to the platform and supports a steady stream of higher value use cases. The short term swing factor is whether that AI driven expansion offsets customers trimming traditional seat counts and pushing for more flexible pricing. The main risk still sits in execution. Salesforce is layering complex AI automation, security, and governance onto a large installed base while carrying meaningful debt and absorbing past one off gains. The latest ecosystem news does not materially change that near term risk reward balance. It mostly reinforces the existing direction. The most relevant update for this AI catalyst story is Koa, Salesforce’s new CRM reasoning model for Agentforce built on NVIDIA’s Nemotron. Koa is built to handle complex, multi step workflows while keeping customer data inside Salesforce’s trust boundary, which directly targets the concern that AI automation could commoditize CRM workflows instead of making them stickier. If Koa and related Nemotron powered models inside Missionforce work reliably for regulated and government clients, Salesforce gains a concrete reference point that its agentic platform can handle sensitive, high stakes processes. That would support the thesis that AI deepens switching costs, but it also raises the bar on security, compliance, and model quality, which remain key operational risks.Salesforce's current analyst storyline points to US$58.6b in revenue and US$10.7b in earnings by 2029, based on 10.1% yearly top line growth and an earnings increase of about US$1b from US$9.7b today.
Uncover why Salesforce's fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The optimistic camp thinks Salesforce’s AI alliances with partners like June AI and Stensul could turn Agentforce and Data Cloud into much larger businesses than consensus expects. Those analysts were already modeling revenue of about US$60.5b and earnings near US$11.5b by 2029. You can compare that bolder story with more cautious views, which may now evolve after this week’s announcements.
Explore 17 other Salesforce fair value estimates, including one that suggests up to 118% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Salesforce research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Salesforce. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Salesforce's overall financial health at a glance.
Looking For More Investment Ideas Beyond Salesforce?
Once you have a view on Salesforce, it can help to widen the lens and see how other listed companies stack up on quality, valuation, and risk using the Simply Wall St Screener.
- If you prefer stability and controlled risk, start with a curated set of 30 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- For investors hunting for mispriced quality, scan a focused group of 31 high quality undervalued stocks that combine solid fundamentals with room for a re rating.
- Income focused readers can narrow in on cash generators by reviewing a targeted 8 dividend fortresses that pay higher yields while aiming to keep payouts covered.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com