
NEC (TSE:6701), Why Is It Drawing Fresh Attention Now?
NEC (TSE:6701) is back in focus after a fresh look at its recent share performance, with the stock showing mixed returns over the past month, past 3 months, and year.
Recent trading tells a mixed story for NEC, with the share price climbing strongly over the past 3 months while the year to date share price return is still in decline, and a 5 year total shareholder return above 300% anchoring the longer term picture.
Scan how NEC's mixed share performance compares with other potential opportunities by zeroing in on hand-picked companies in our 18 high quality undervalued stocks universe.
After a sharp 90 day climb, but a weaker year to date return, NEC now asks a simple question of buyers: Does the current valuation still leave enough upside for the risk involved?
Most Popular Narrative: 22% Undervalued
On the most followed narrative, NEC screens as undervalued, with a fair value of ¥6,162.5 against a last close of ¥4,815. This puts the recent rally into sharper context for anyone weighing the next move.
Ongoing digital transformation "DX" initiatives across both public and private sectors are driving strong order intake and double-digit revenue growth for NEC's high-margin BluStellar unit. This is expected to lead to sustained revenue expansion and margin improvement. Increased demand for advanced IT infrastructure (including AI, cybersecurity, and public safety platforms) from government and municipal projects is supporting bookings and revenue, especially as smart city and urban modernization contracts ramp up.
See why 3 investors see NEC as 22% undervalued.
Result: Fair Value of ¥6,162.5 (UNDERVALUED)
Still, NEC's narrative includes real pressure points, such as expected declines in domestic IT and telecom services that could weigh on revenue, along with rising R&D and personnel expenses that may affect profitability.
Find out about the key risks to this NEC narrative.
Another View: NEC Through The Cash Flow Lens
The story looks different when NEC is valued using the SWS DCF model. On that approach, the estimated future cash flow value sits at ¥3,871.47 per share, which is below the current ¥4,815 price, pointing to a stock that screens as overvalued rather than cheap.
That clash between a higher fair value from the narrative model and a lower figure from cash flows raises a simple question for you as an investor. Which set of assumptions feels closer to how NEC will actually execute over the next few years, and how much uncertainty are you comfortable paying for?
Look into how the SWS DCF model arrives at its fair value.
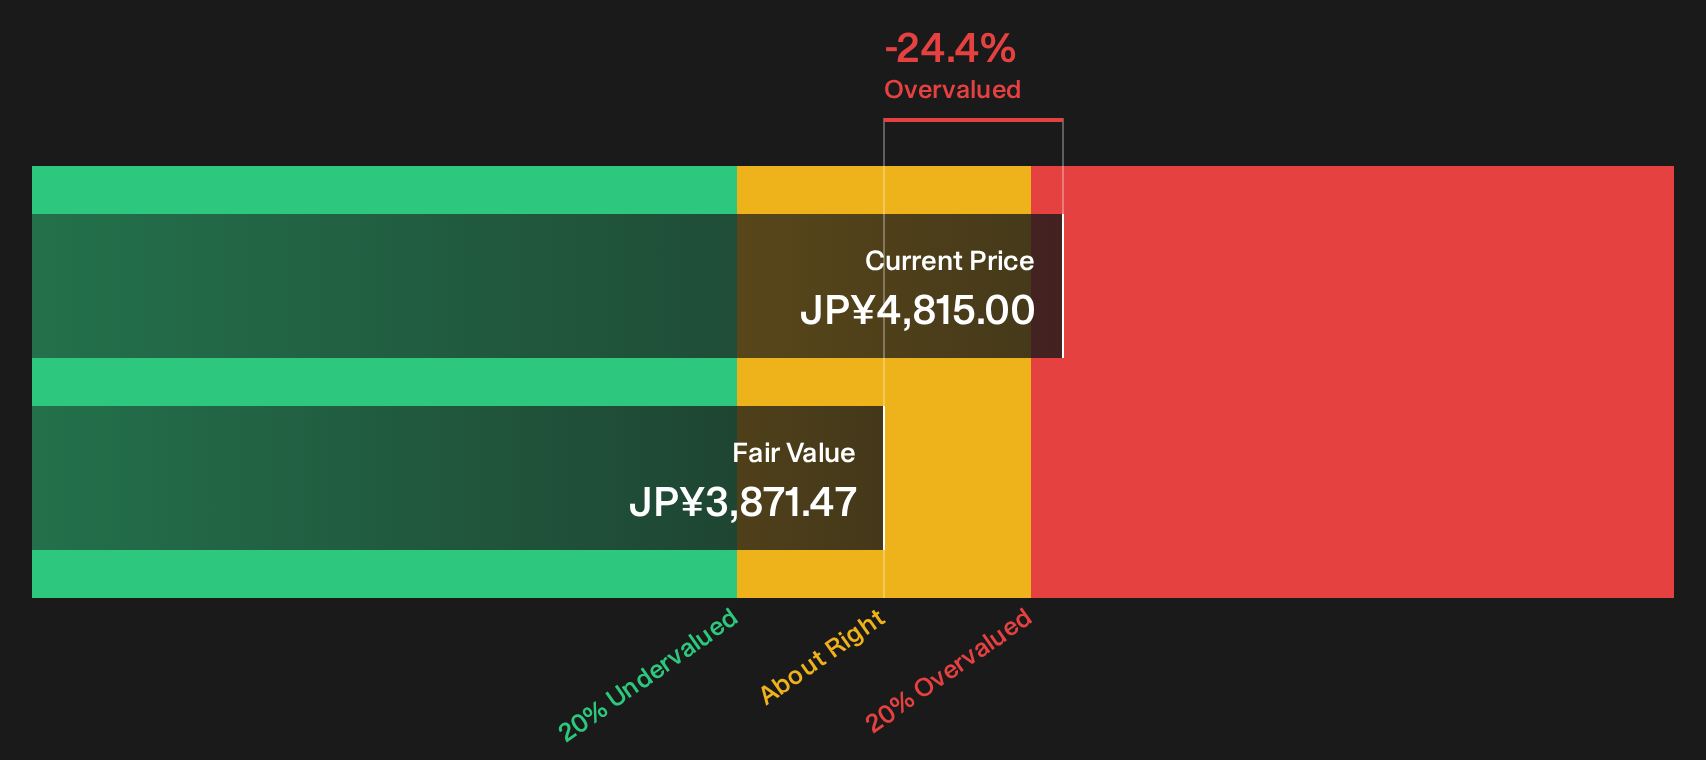
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NEC for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals across NEC's valuation models can feel unsettling, so move quickly to review the full picture and weigh it against your own risk tolerance. Then, ground your view in the balance of 3 key rewards and 1 important warning sign.
Looking for more NEC-sized opportunities?
If NEC has your attention, do not stop here. Let the Simply Wall St Screener surface a broader mix of ideas that could better match your goals.
- Target stronger value potential by scanning companies that screen as high quality and potentially mispriced using the 18 high quality undervalued stocks.
- Build resilience into your holdings by focusing on businesses with robust finances through the list of solid balance sheet and fundamentals (22 results).
- Hunt for future leaders before the crowd catches on by reviewing the 74 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com